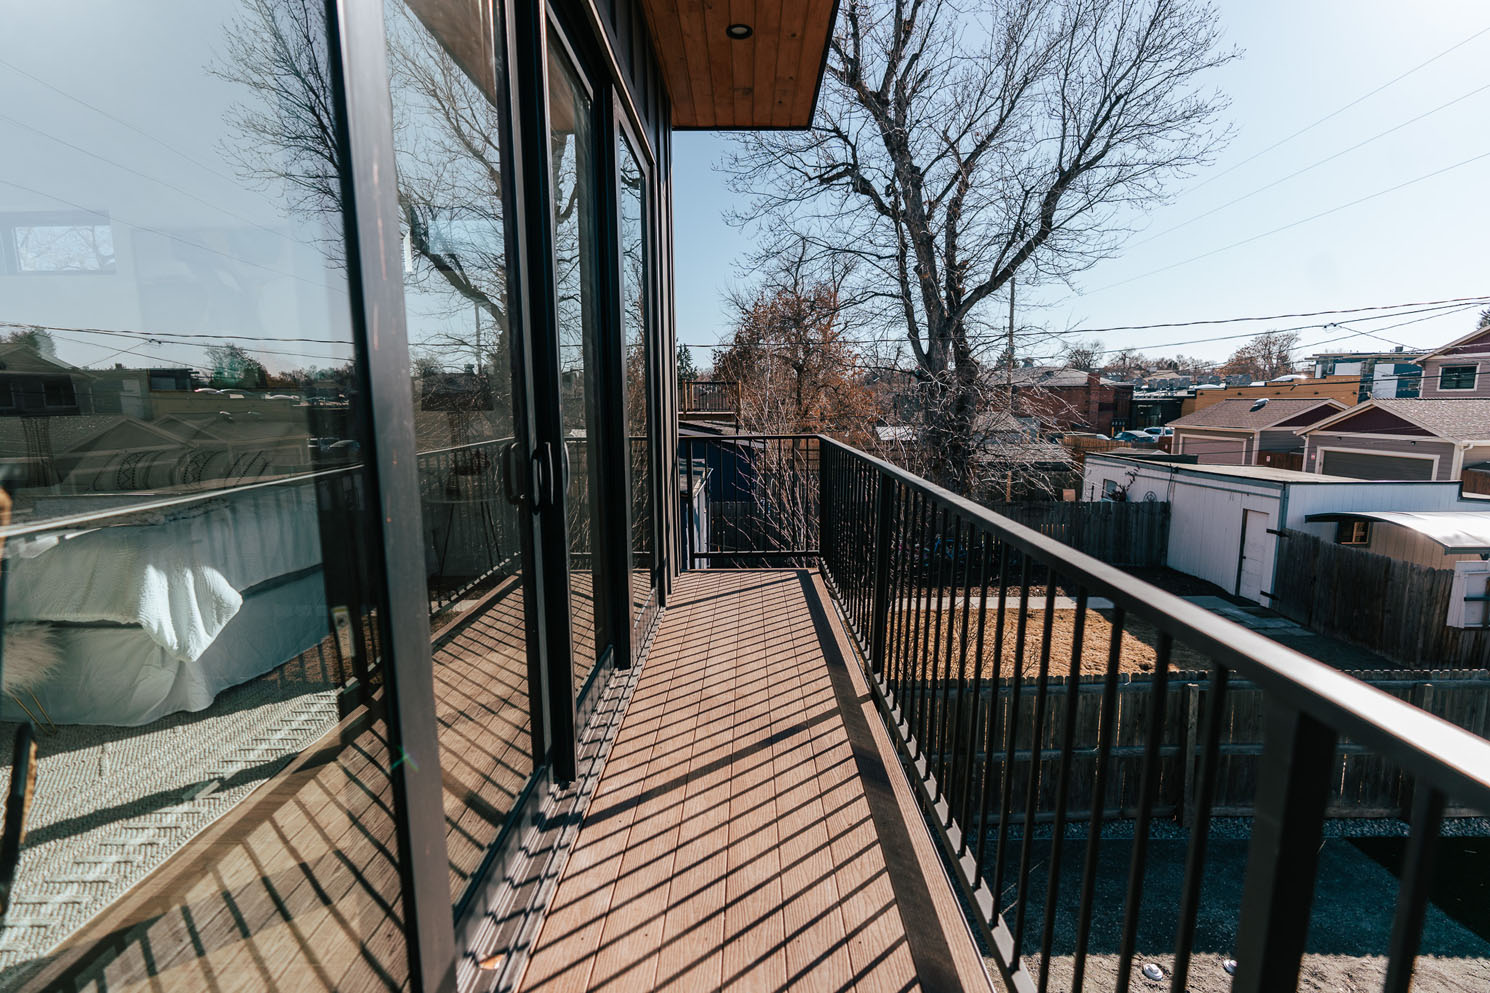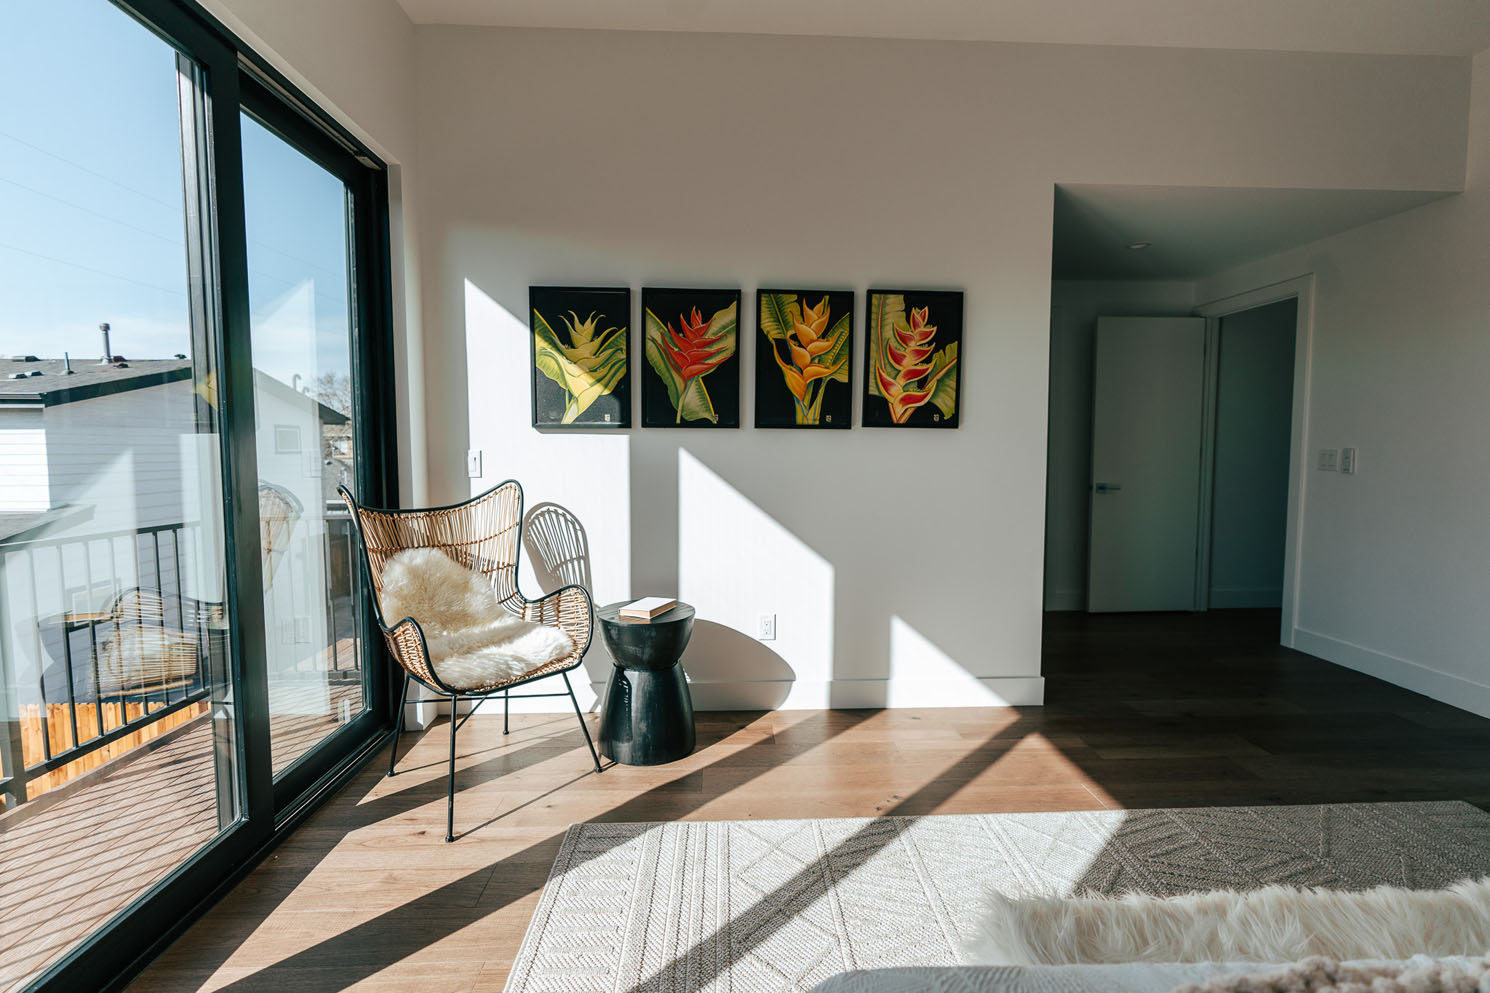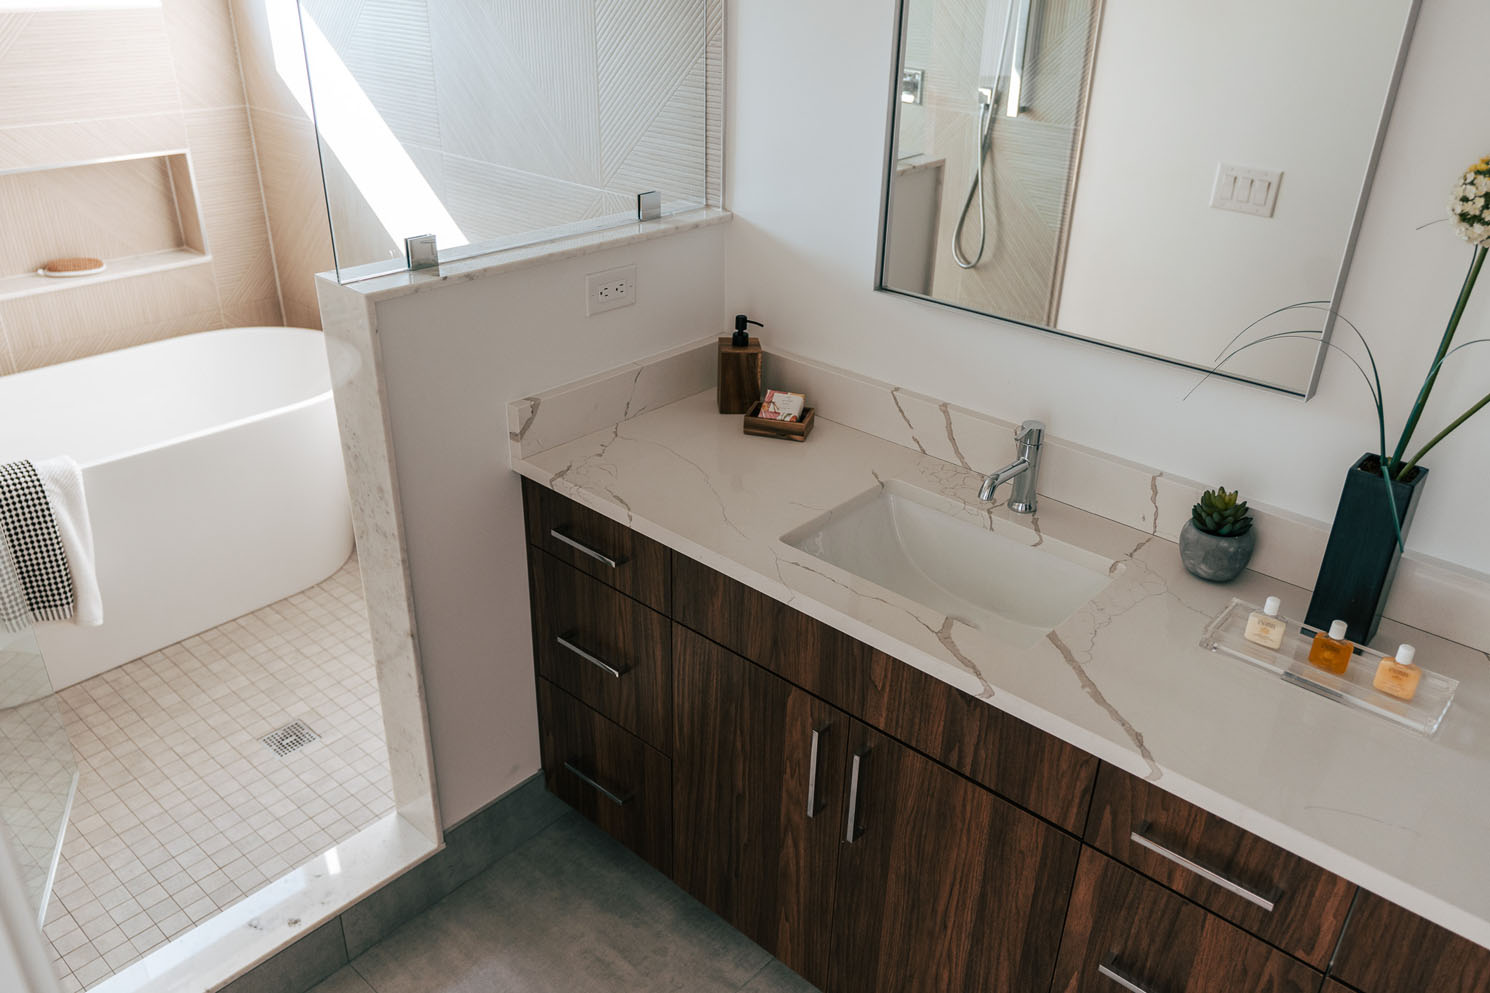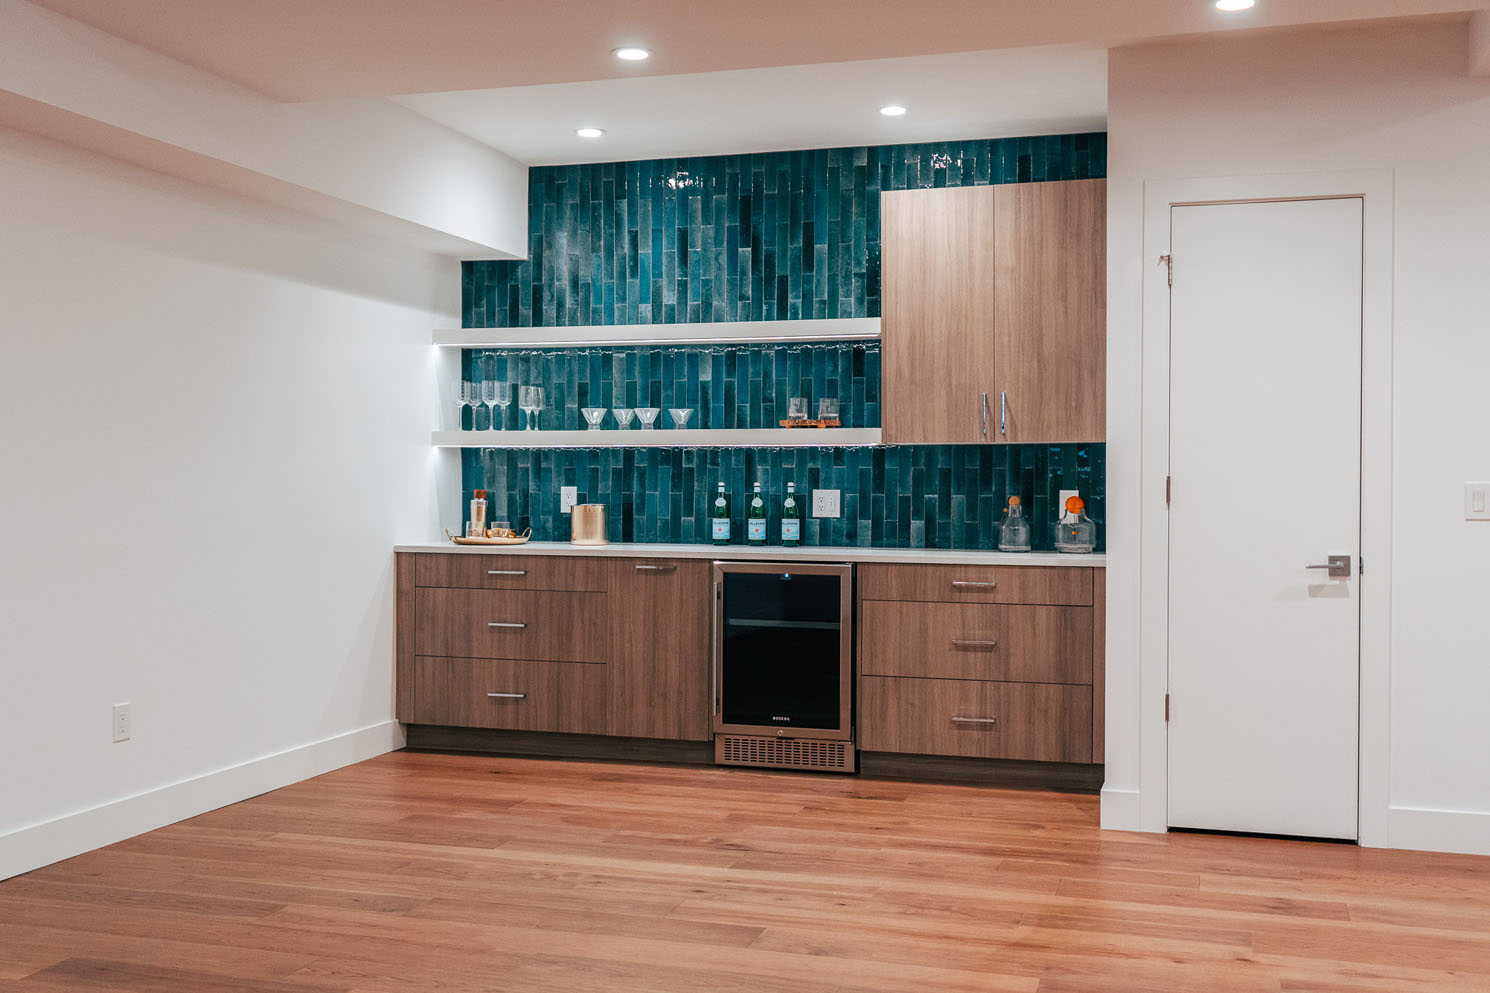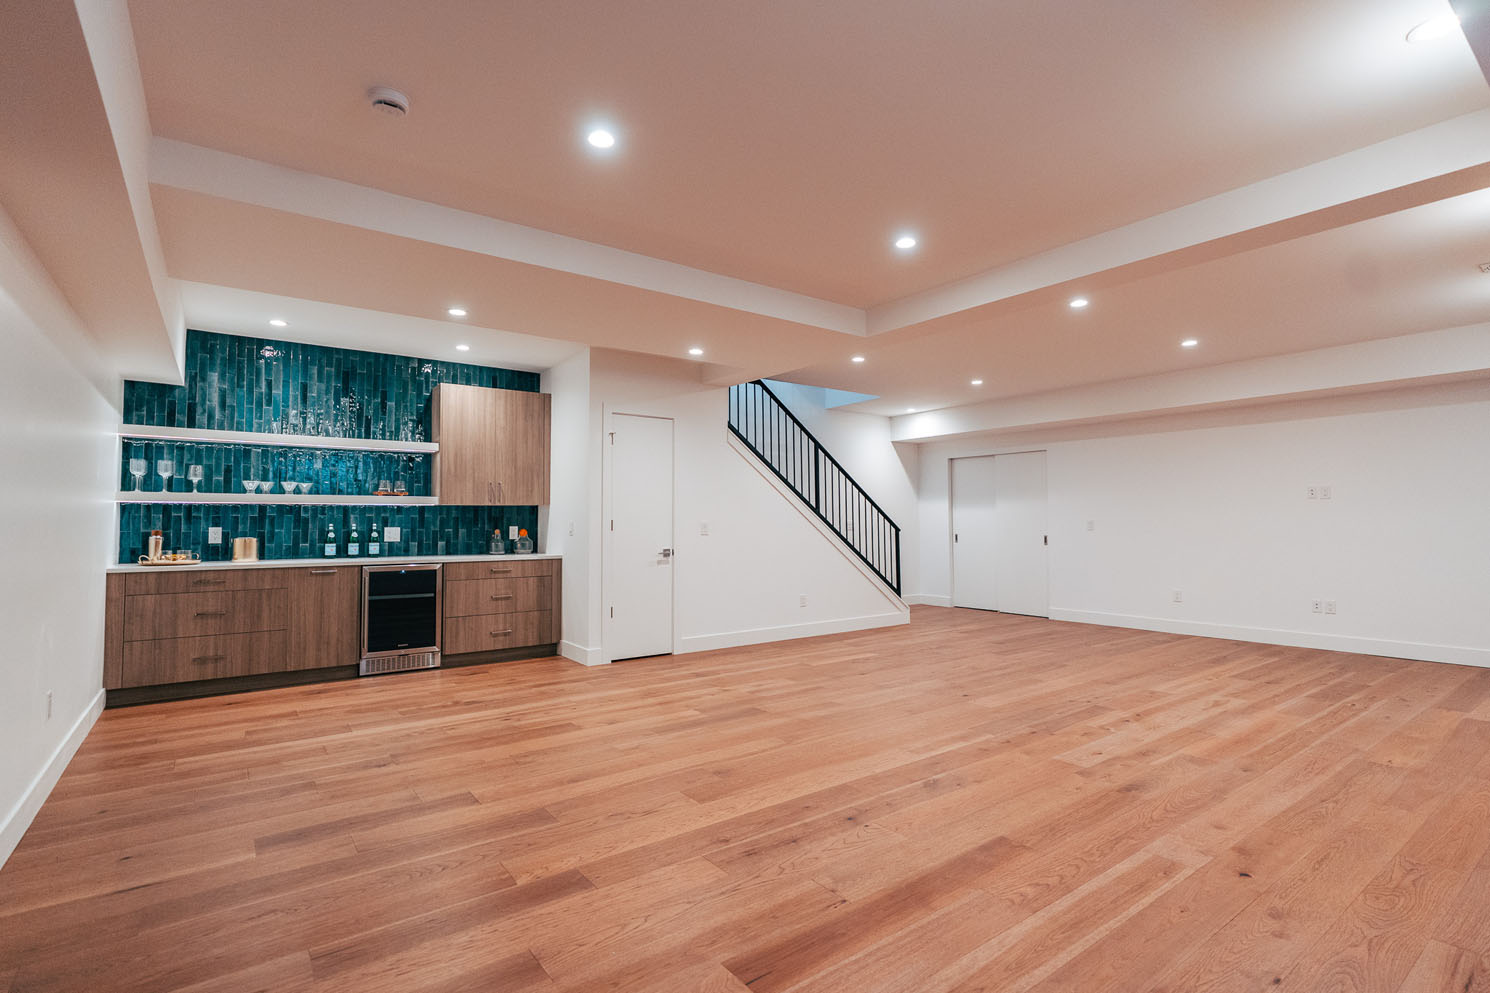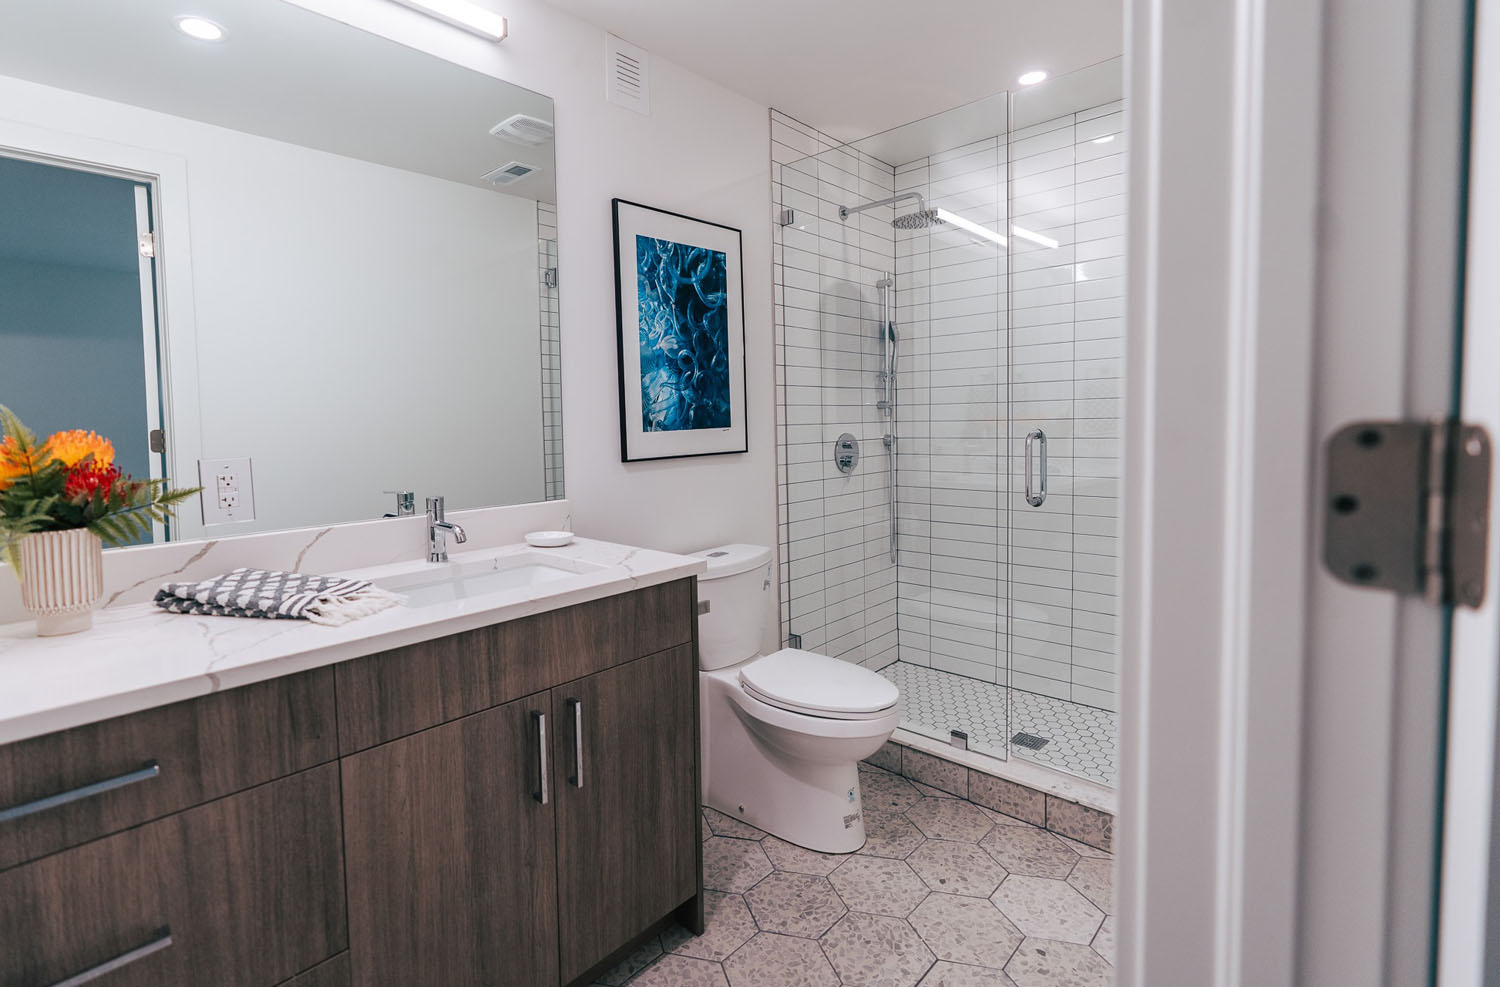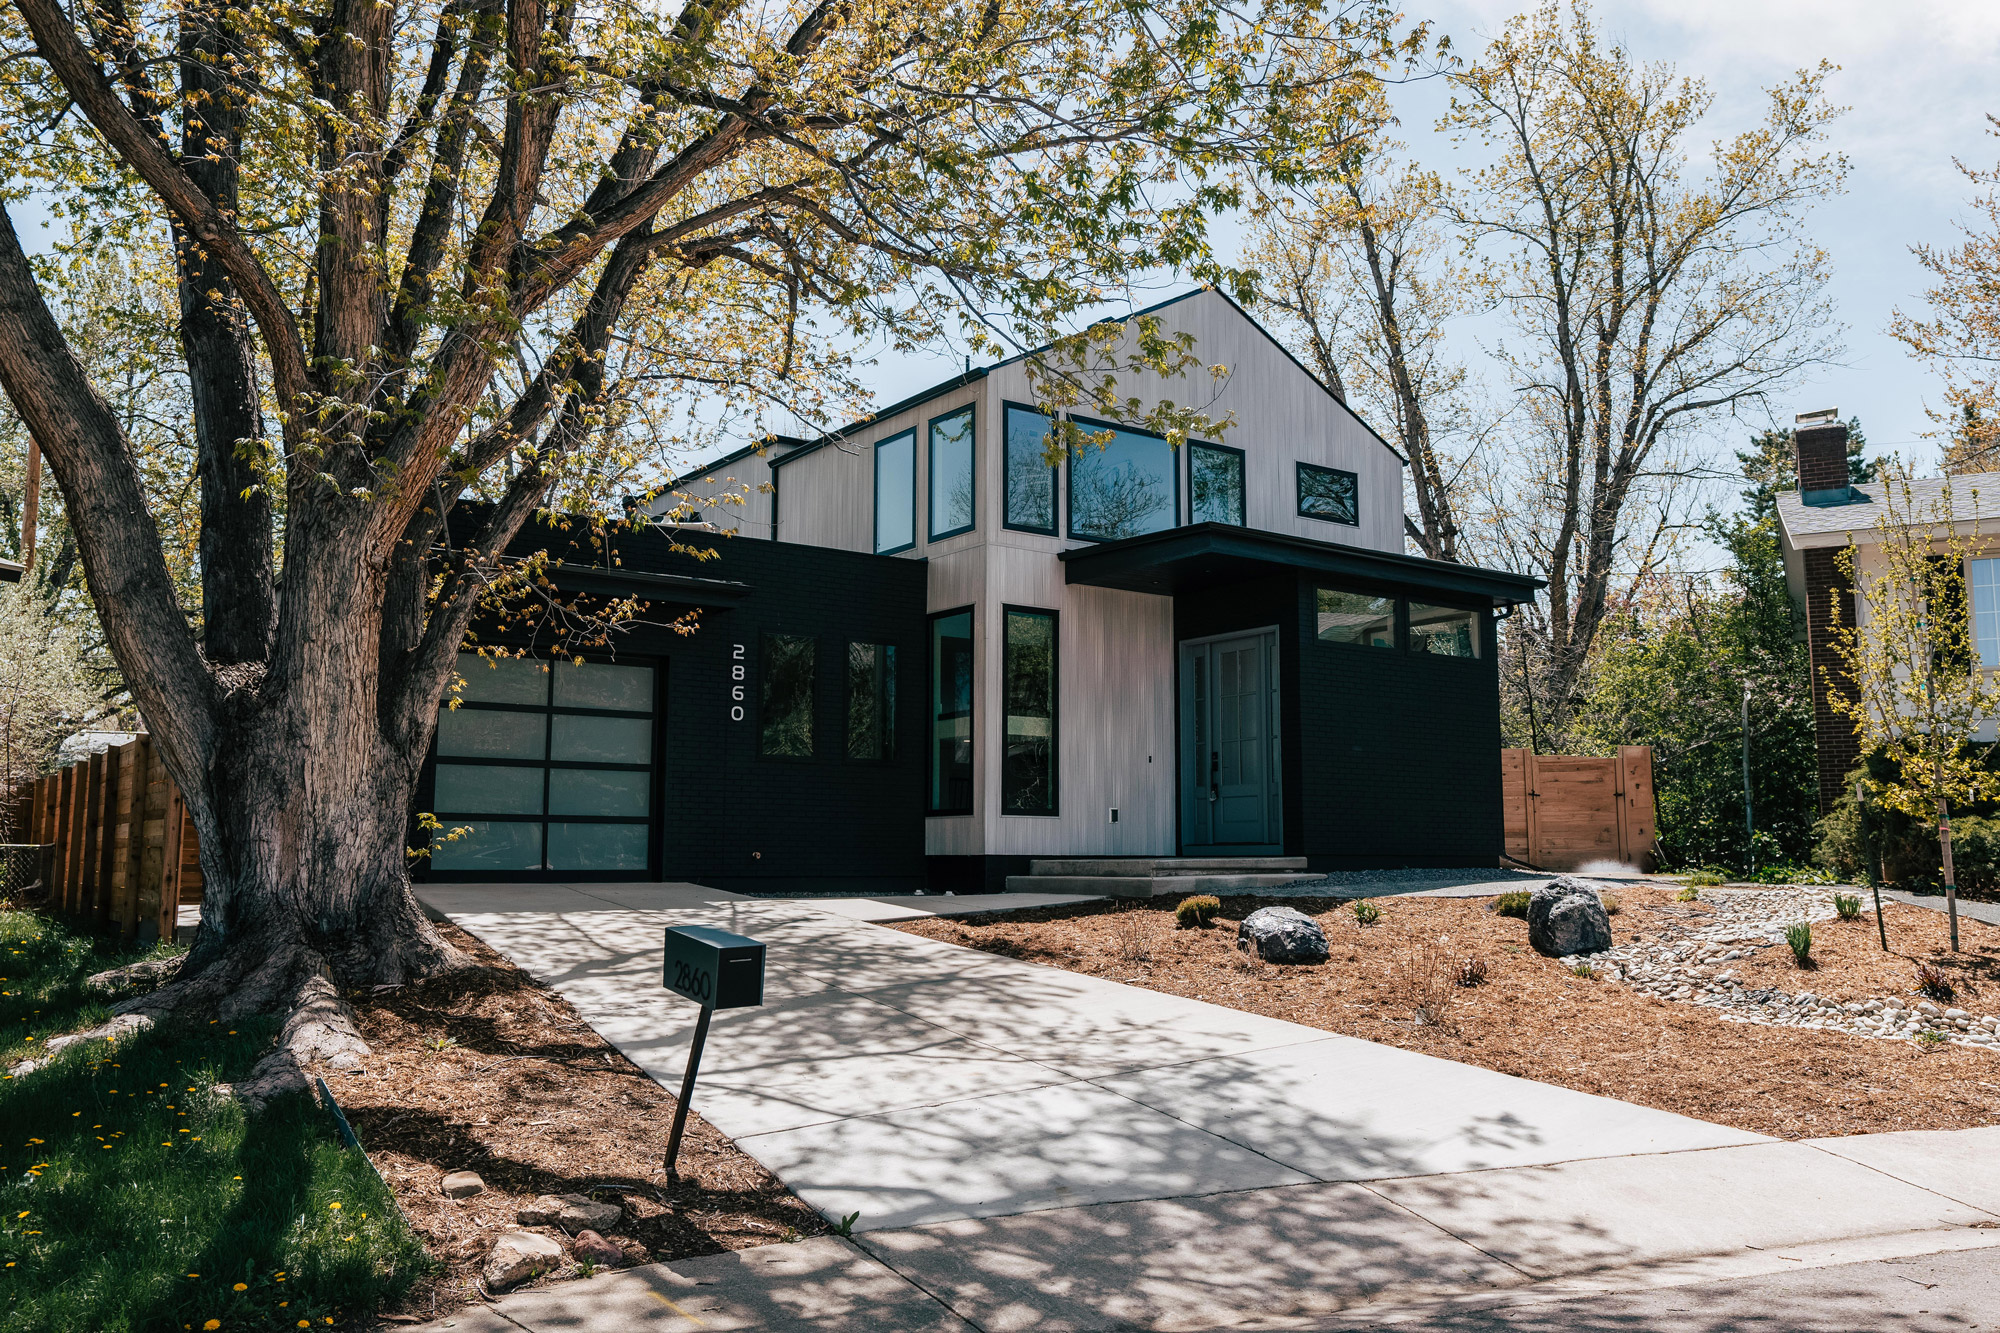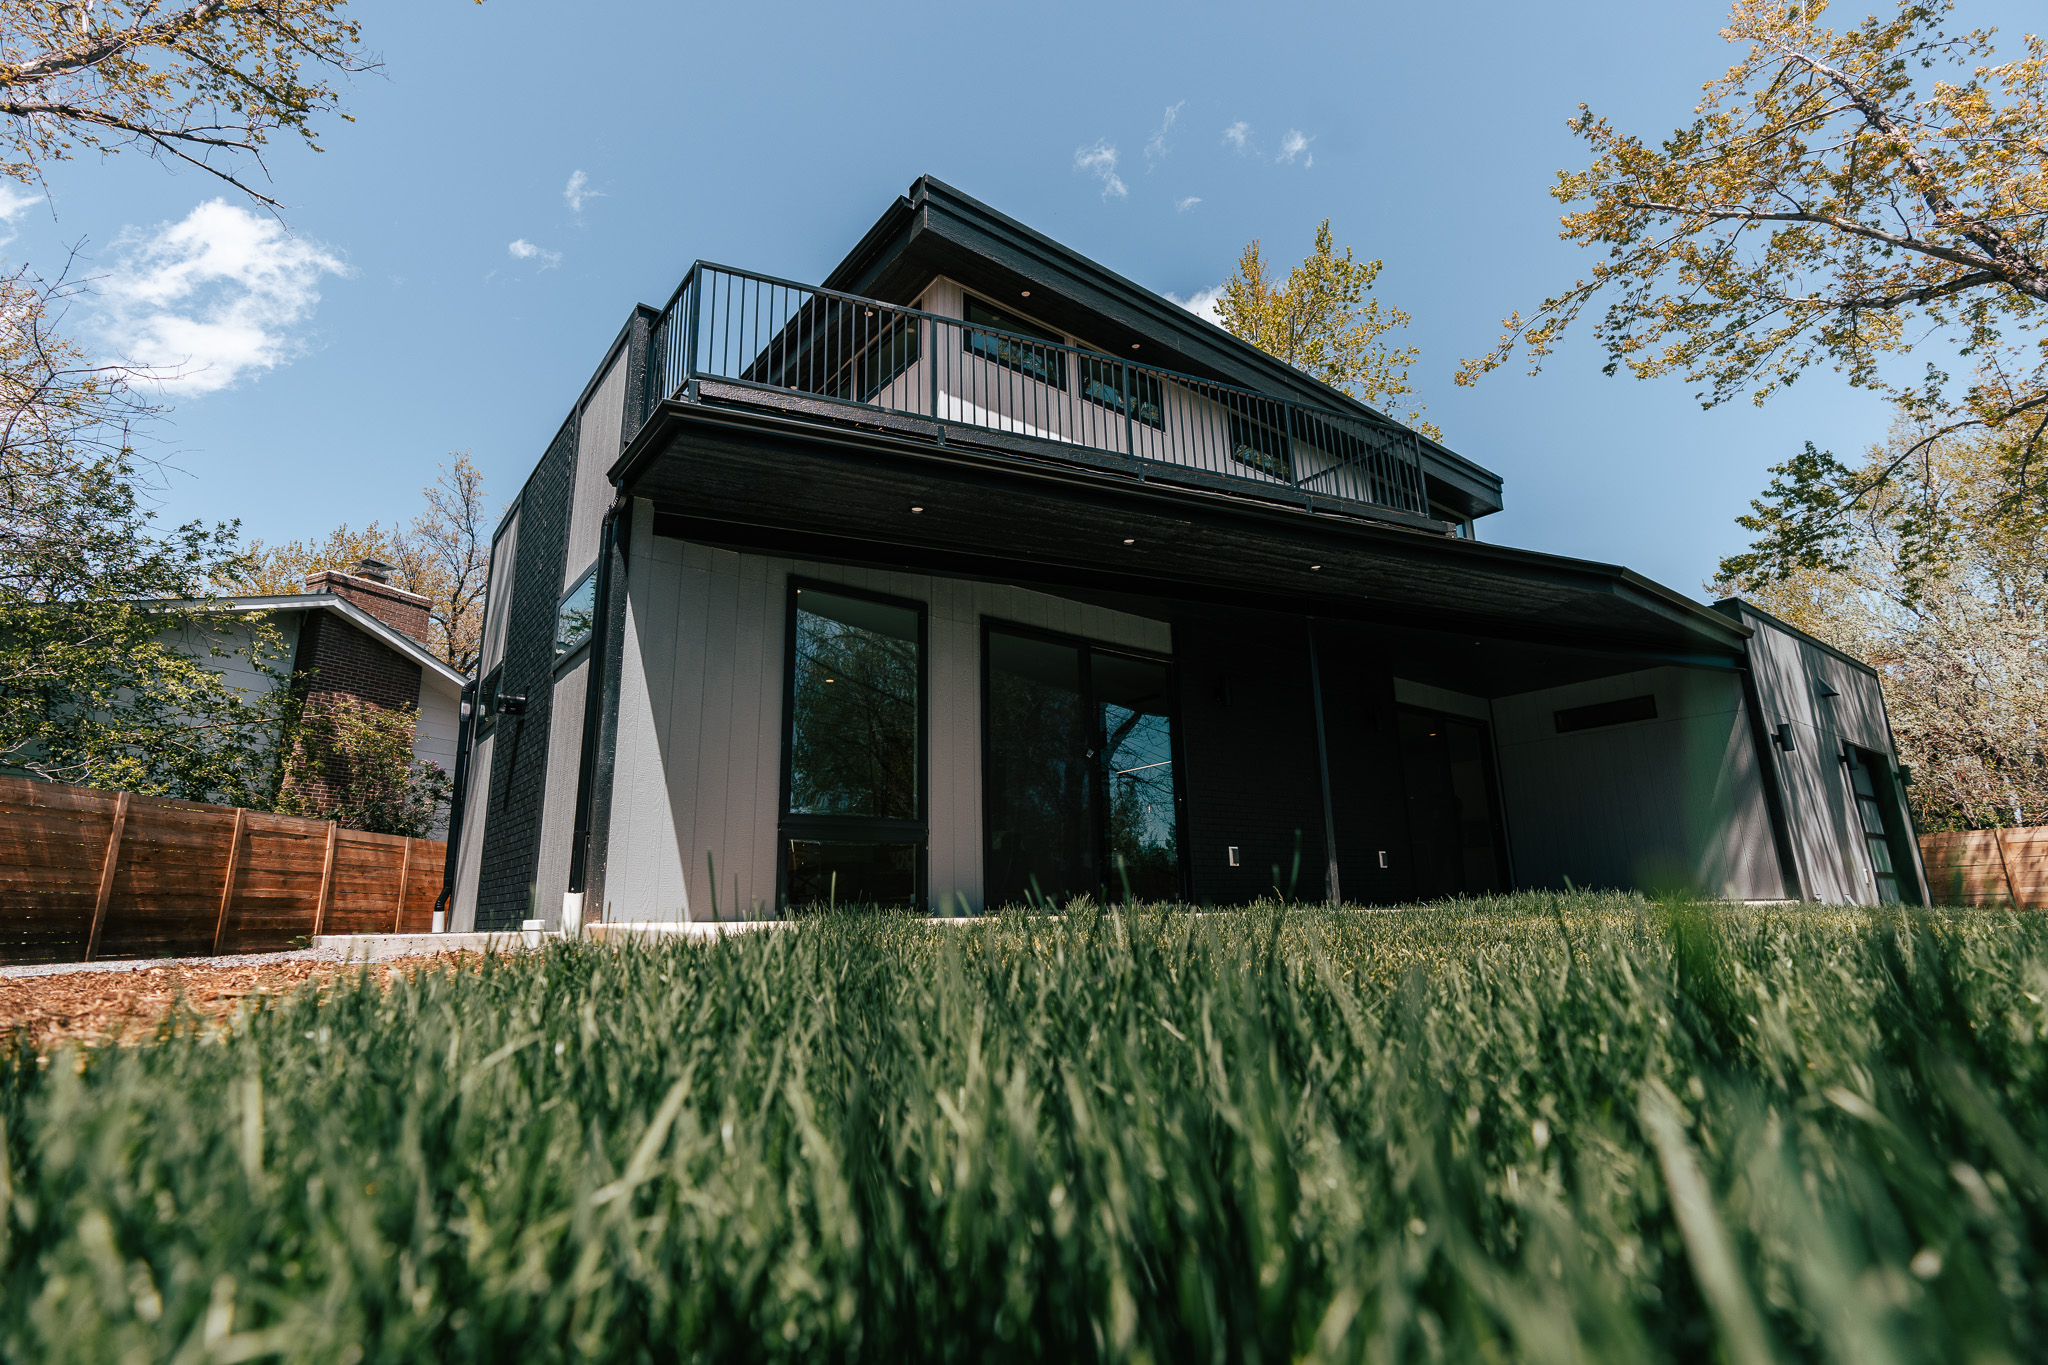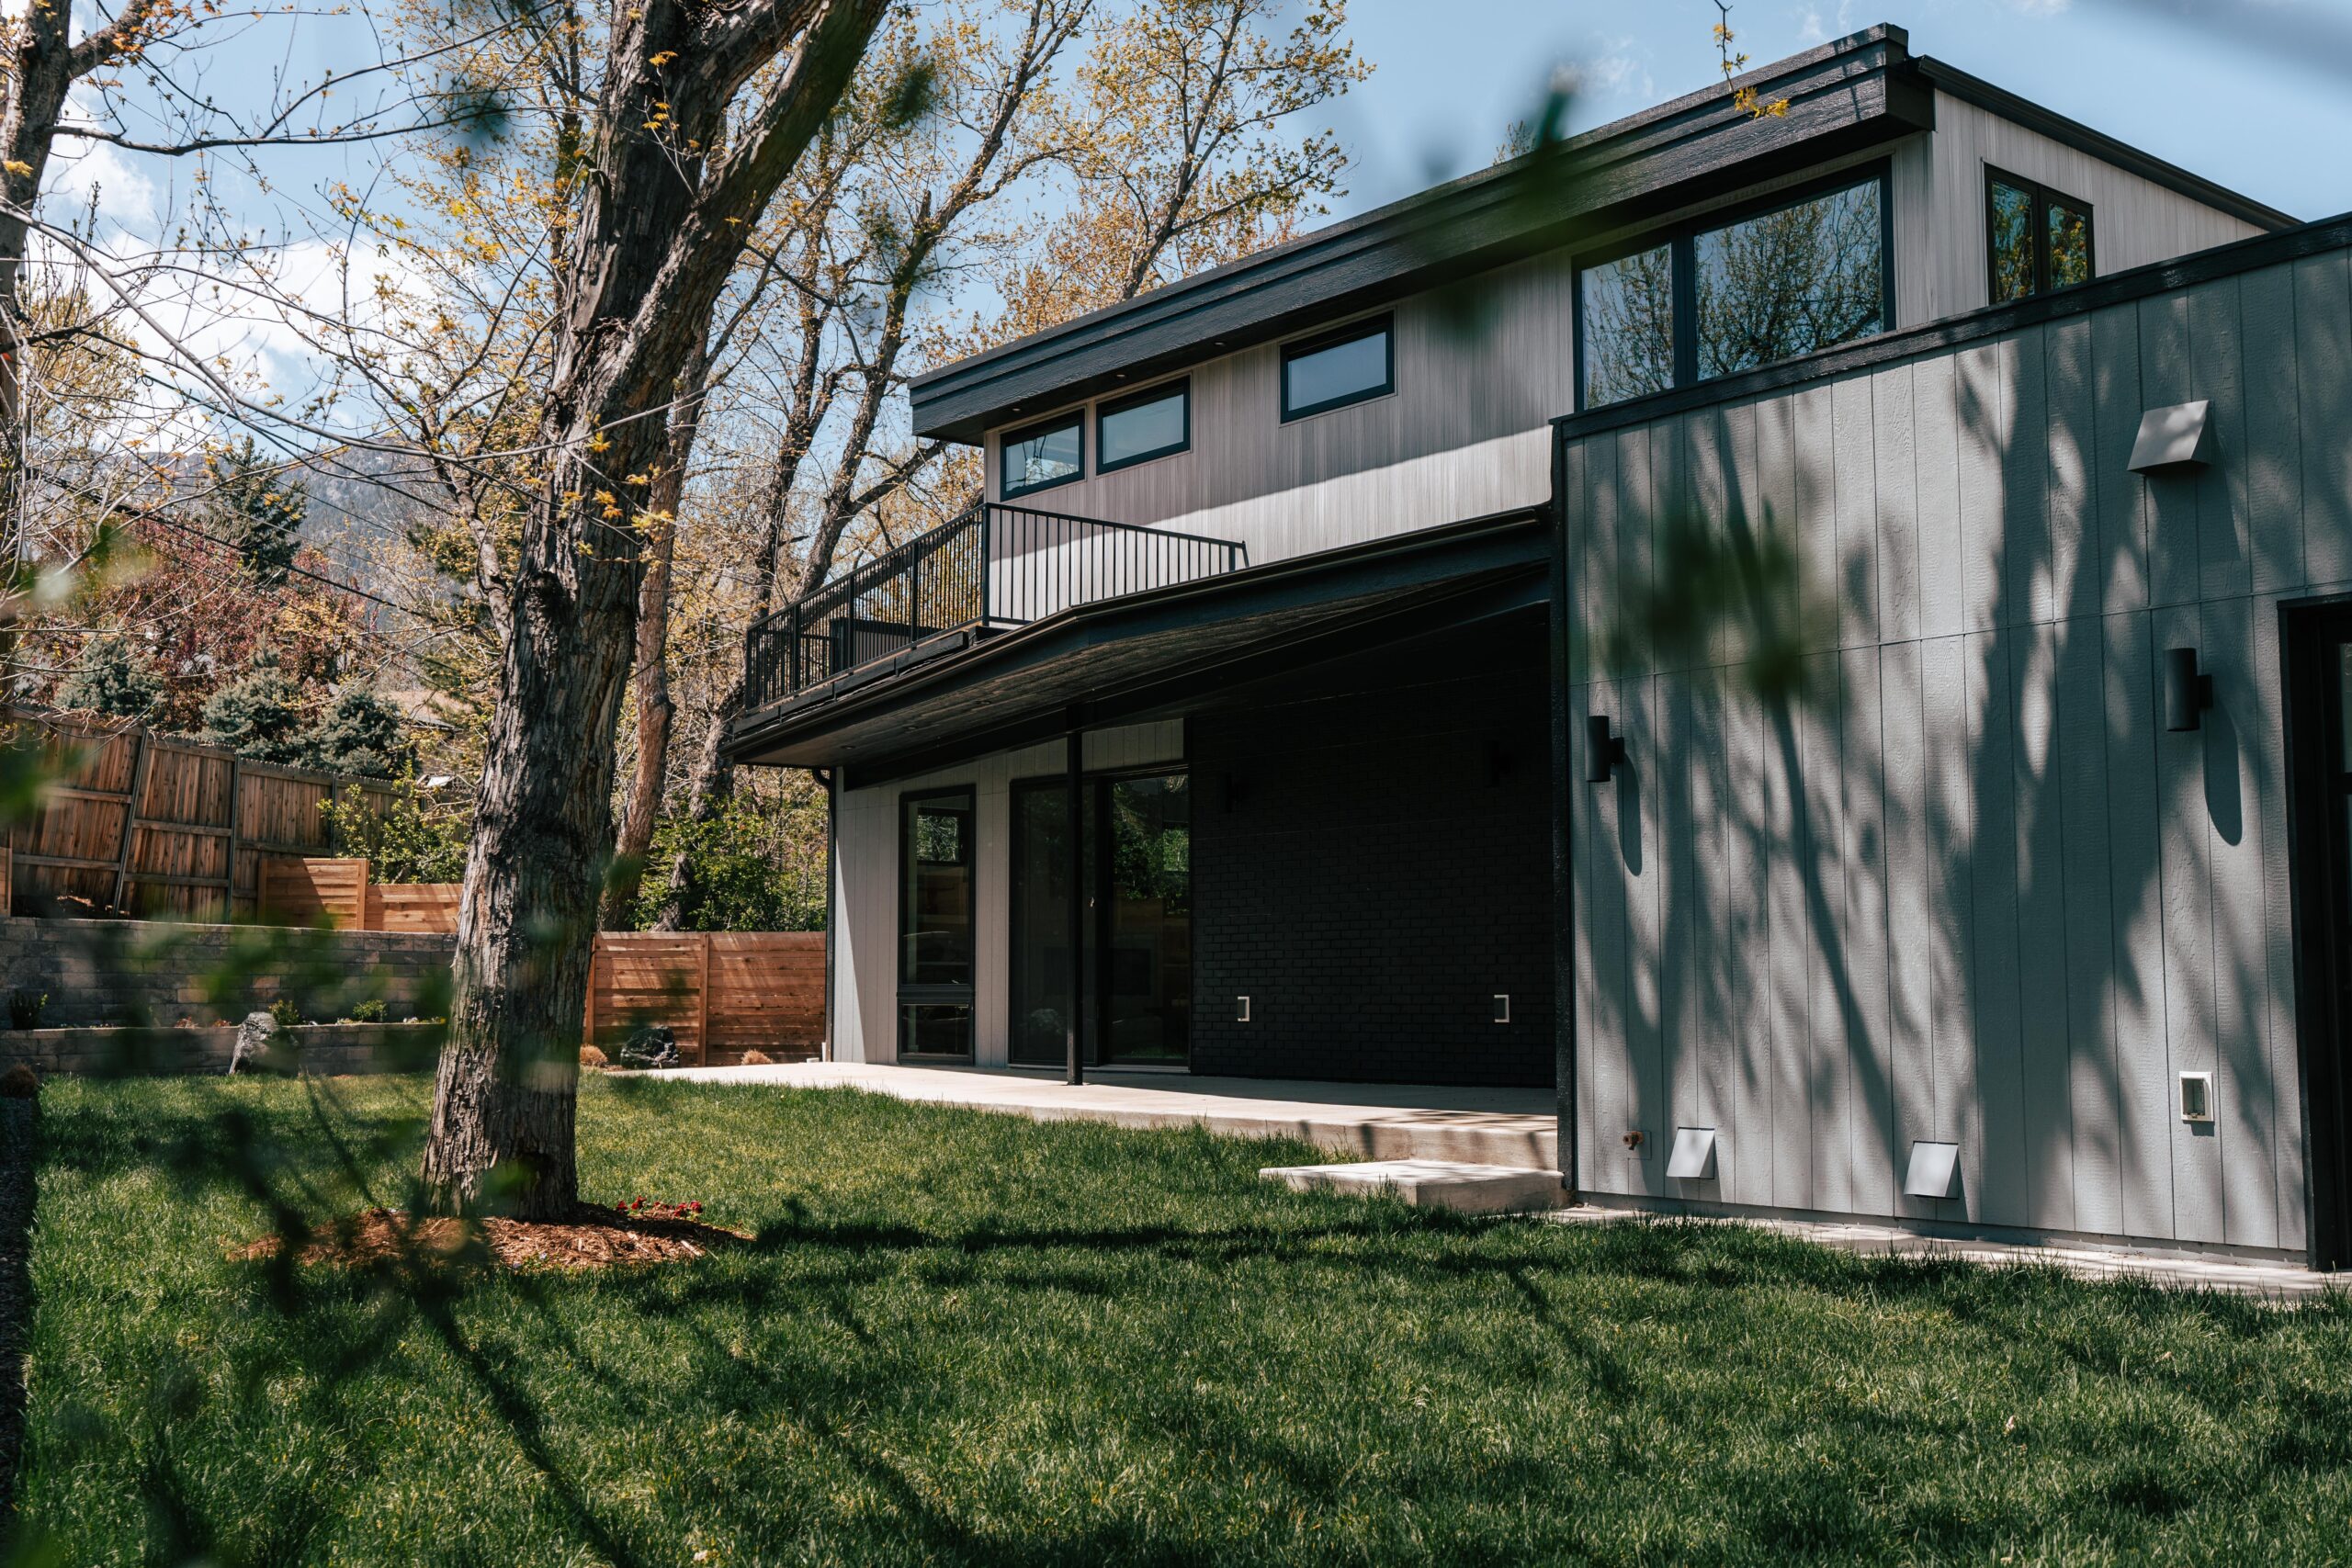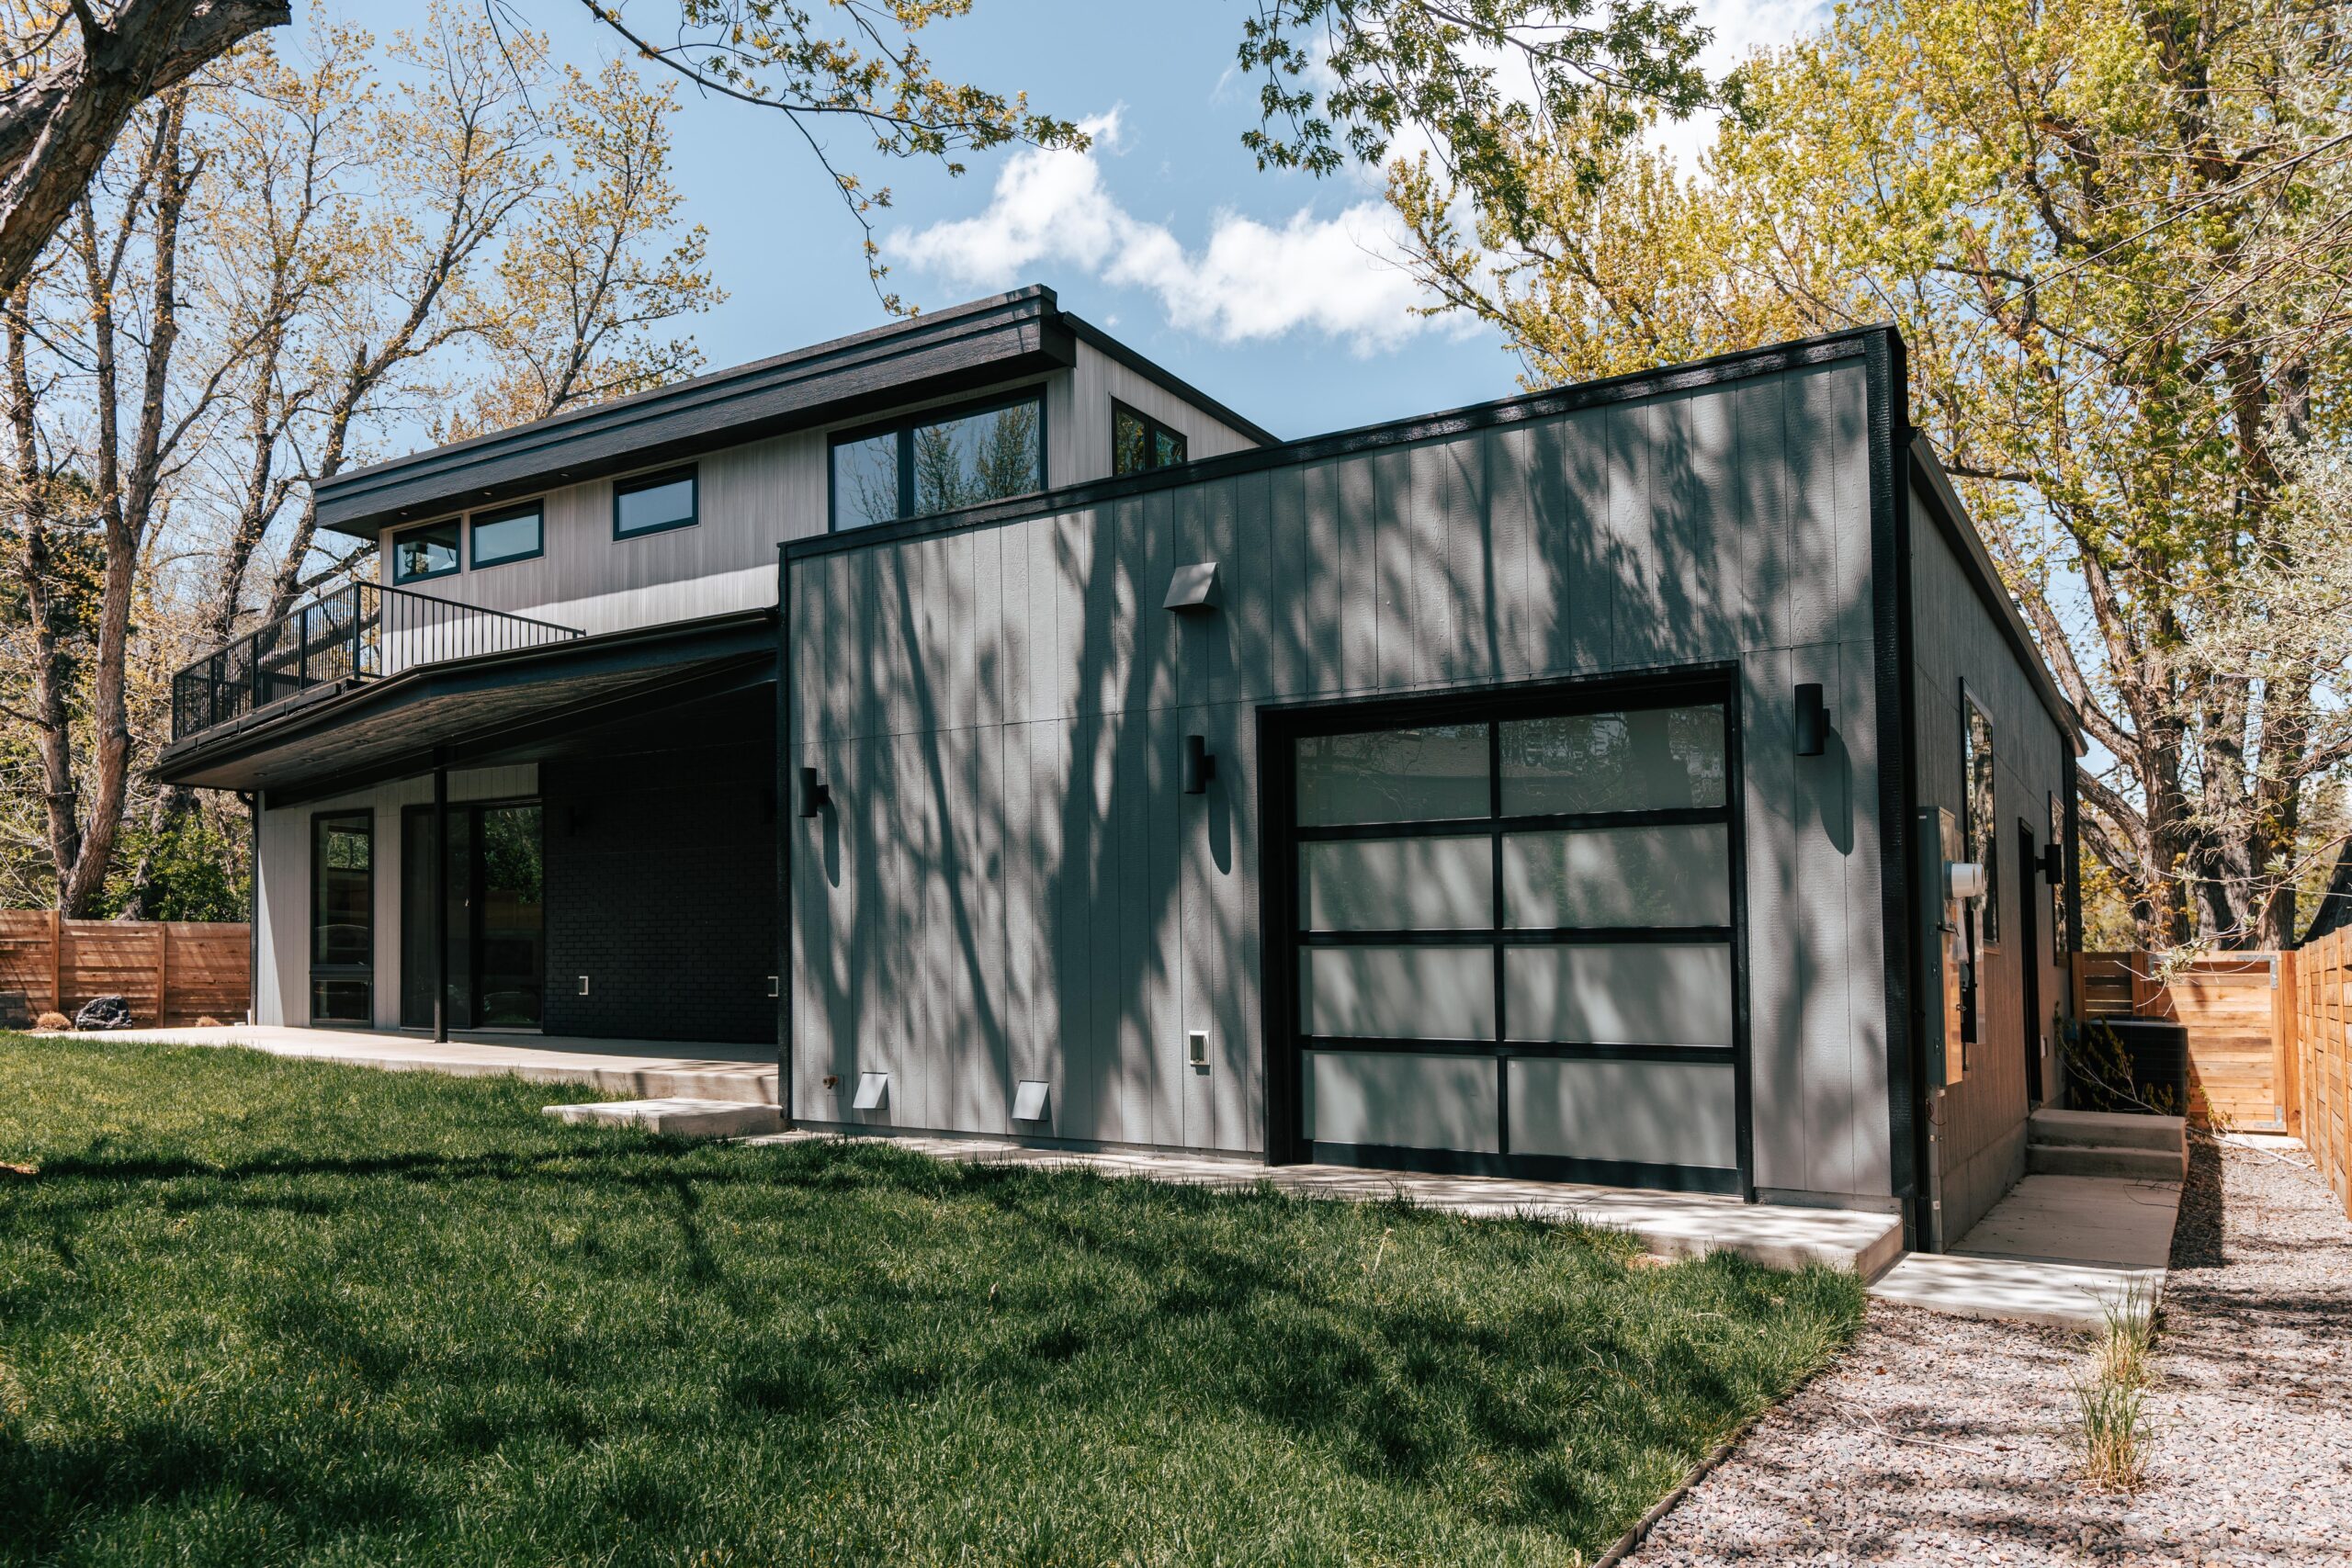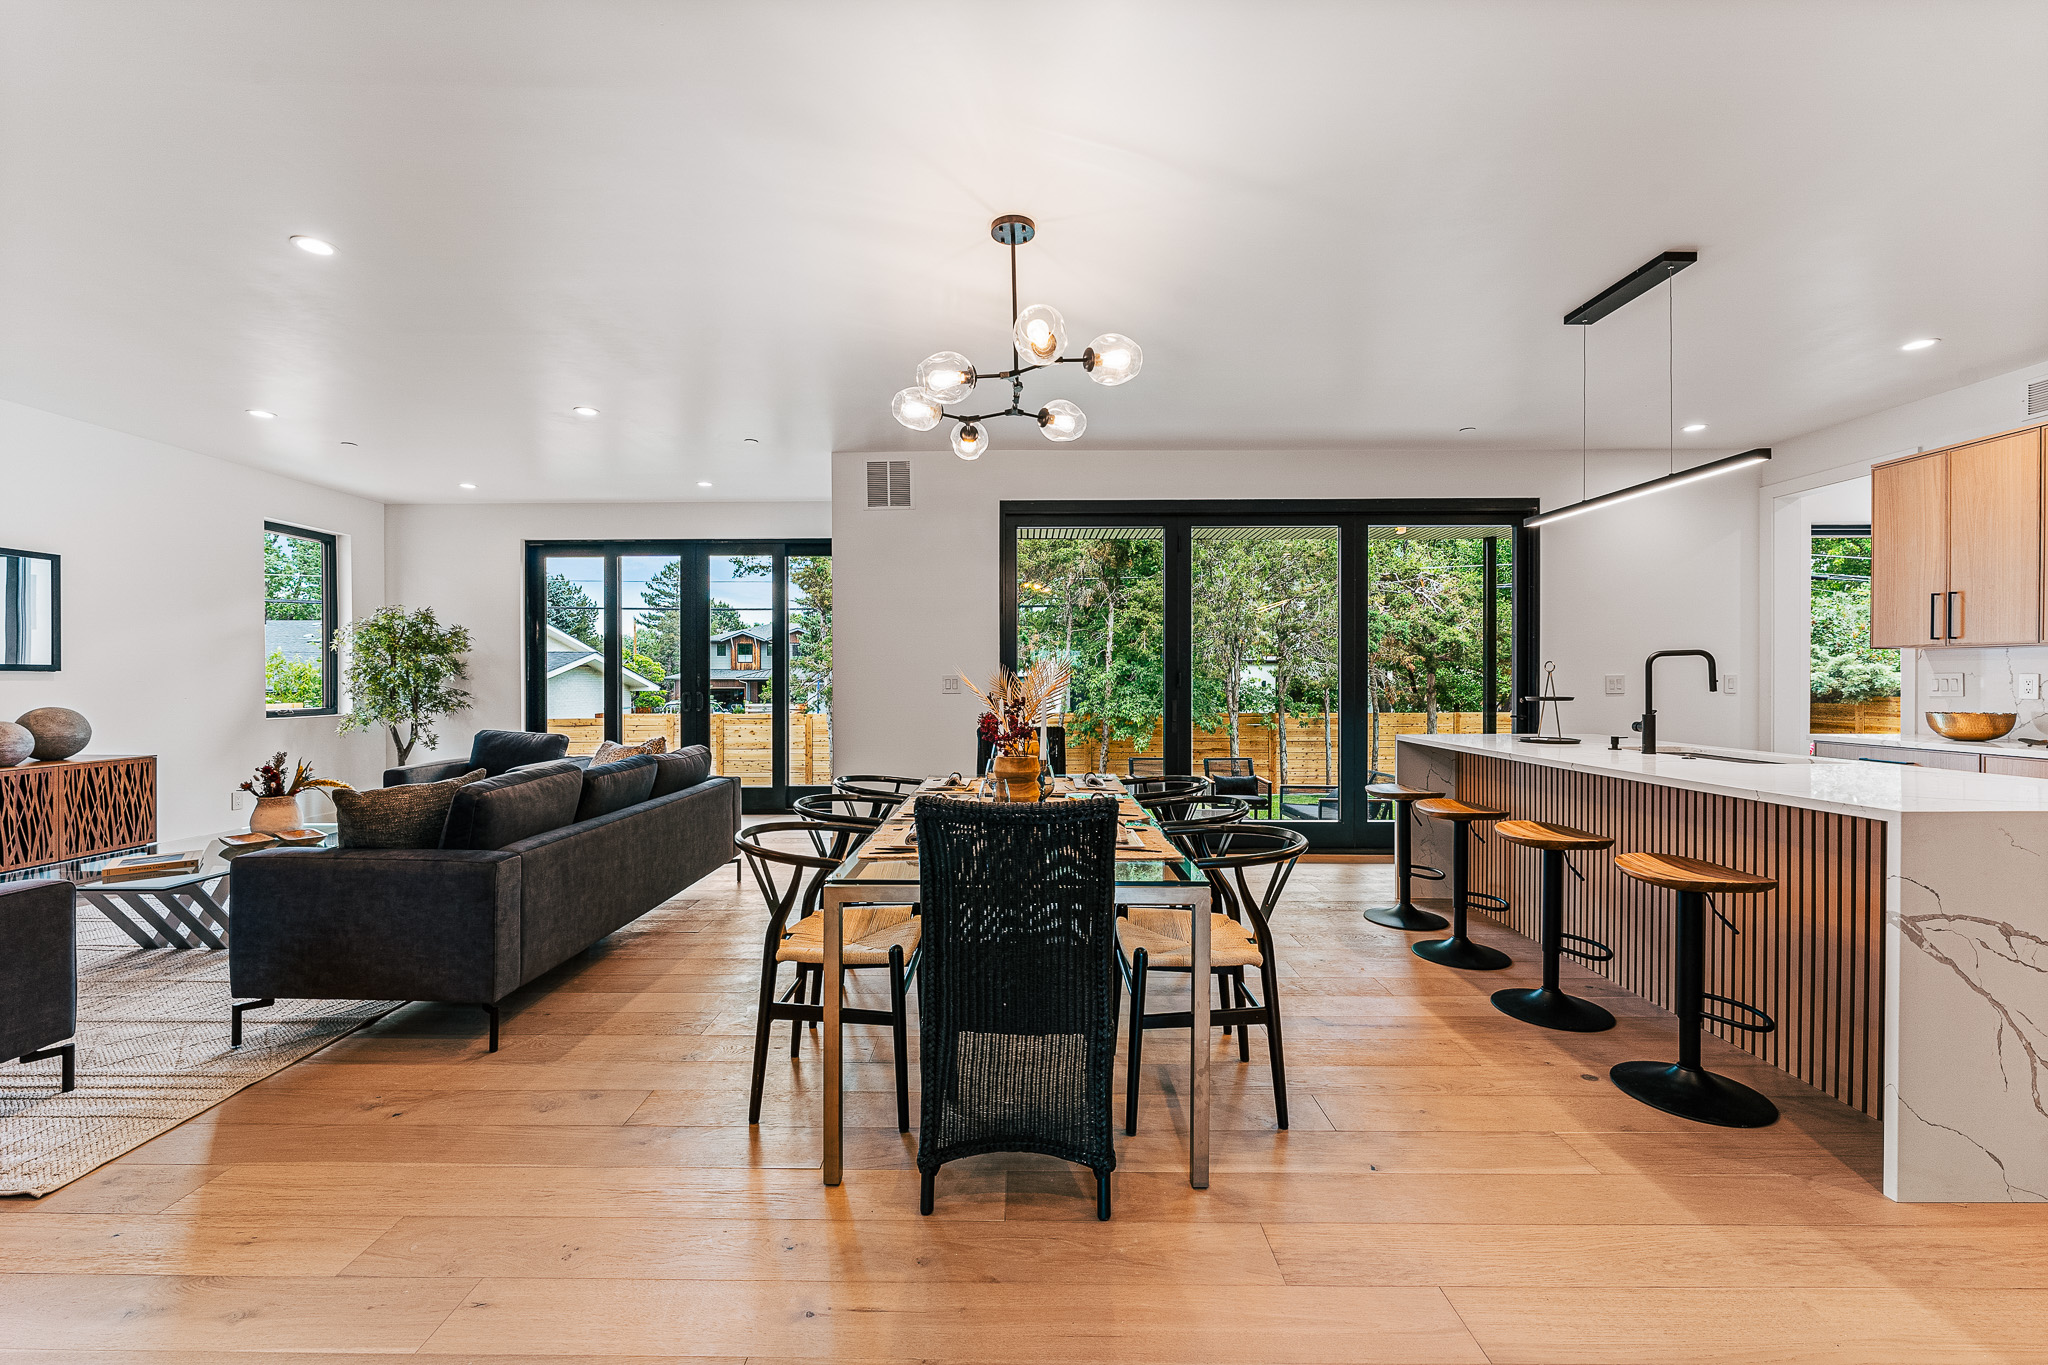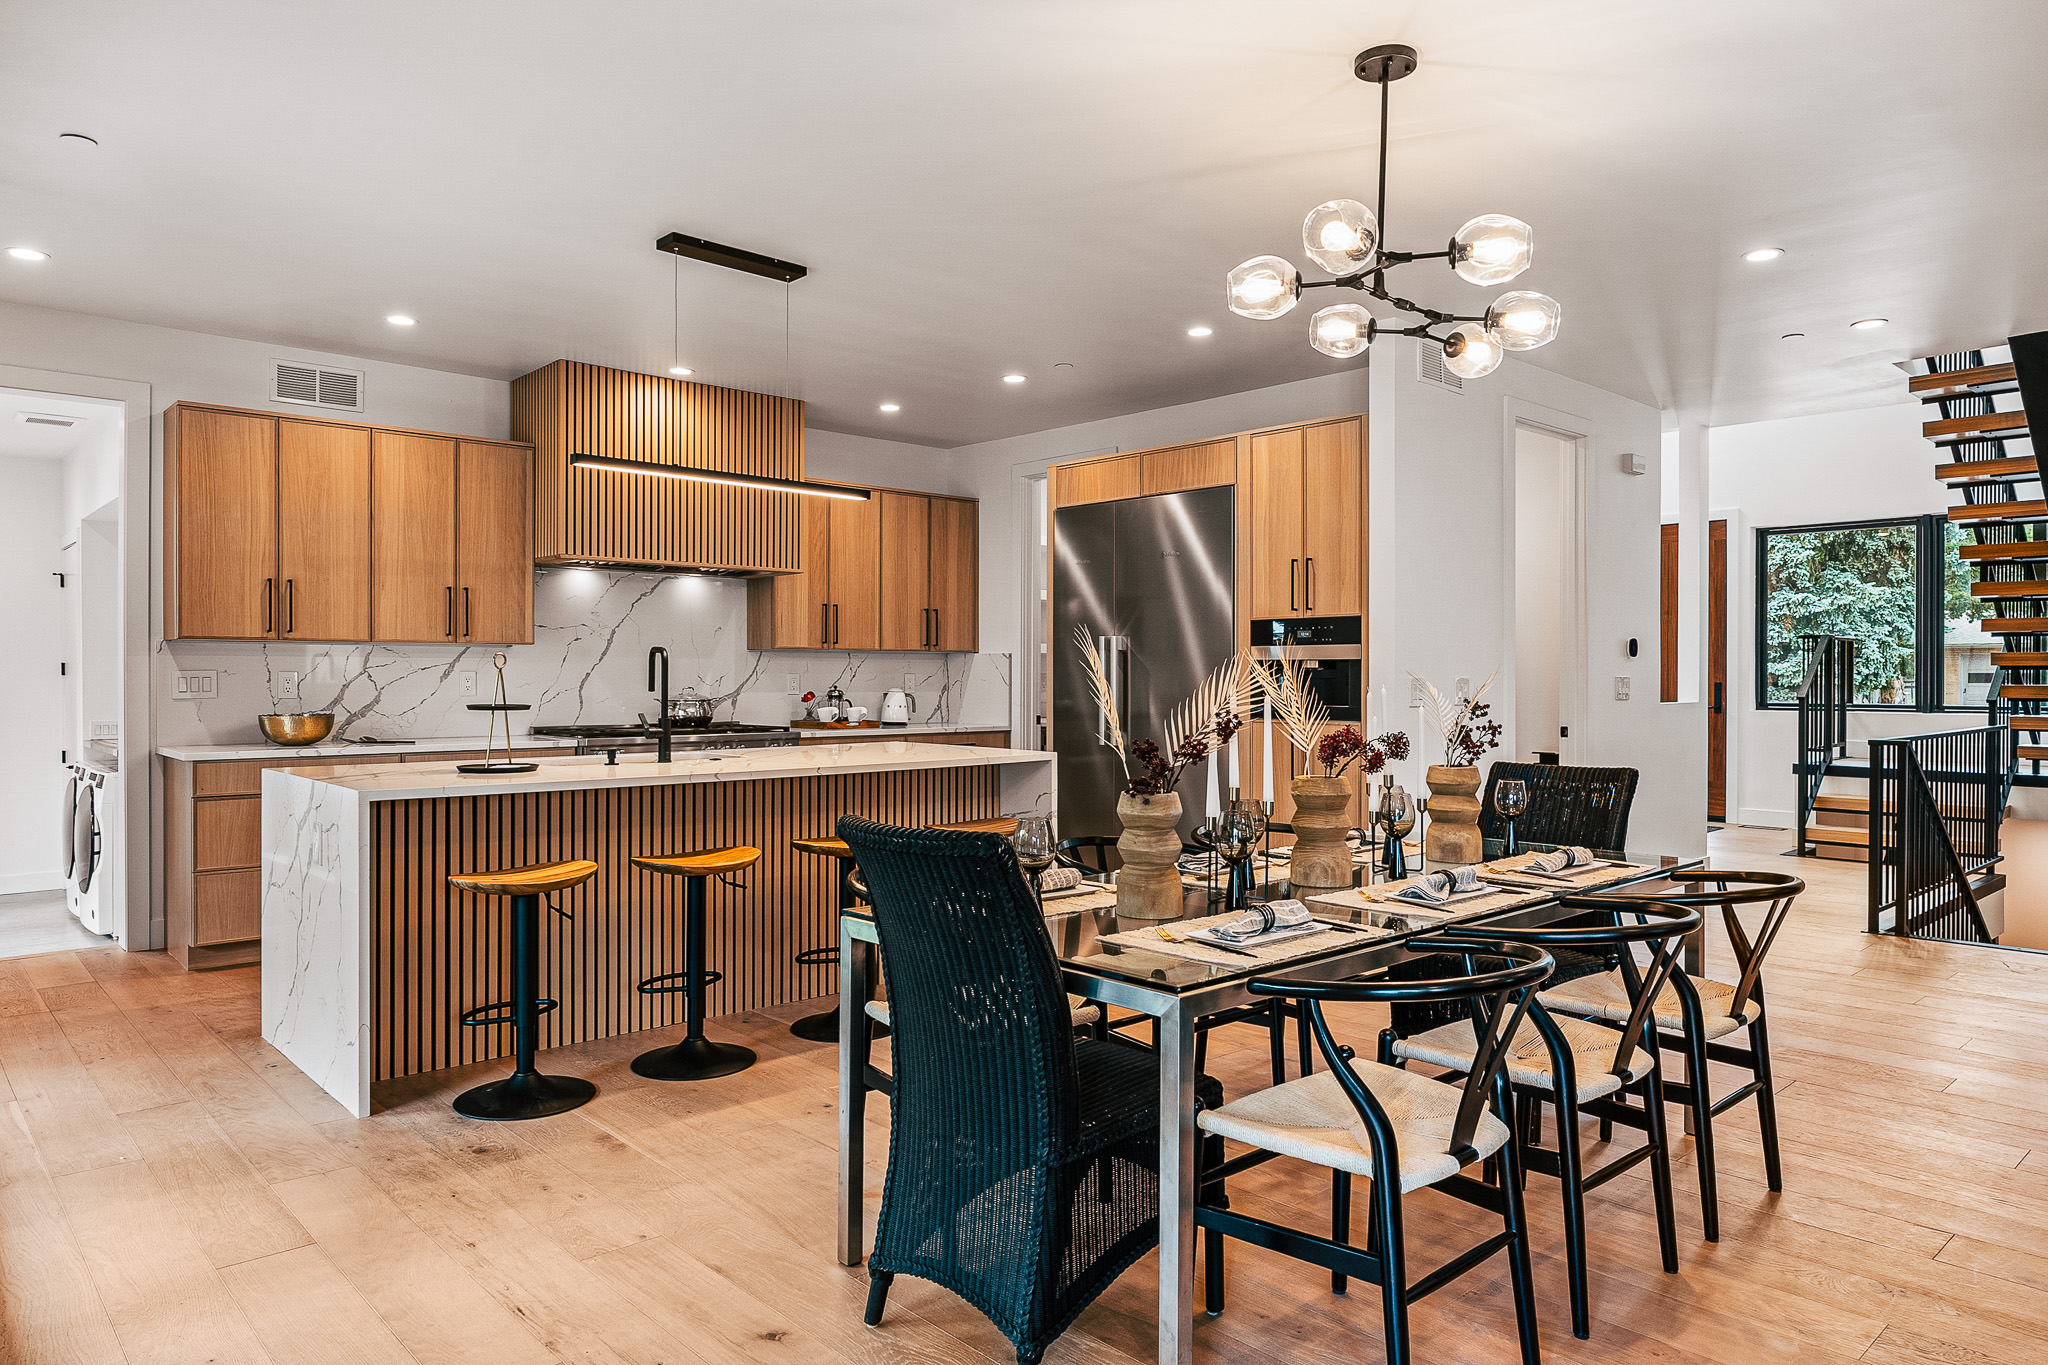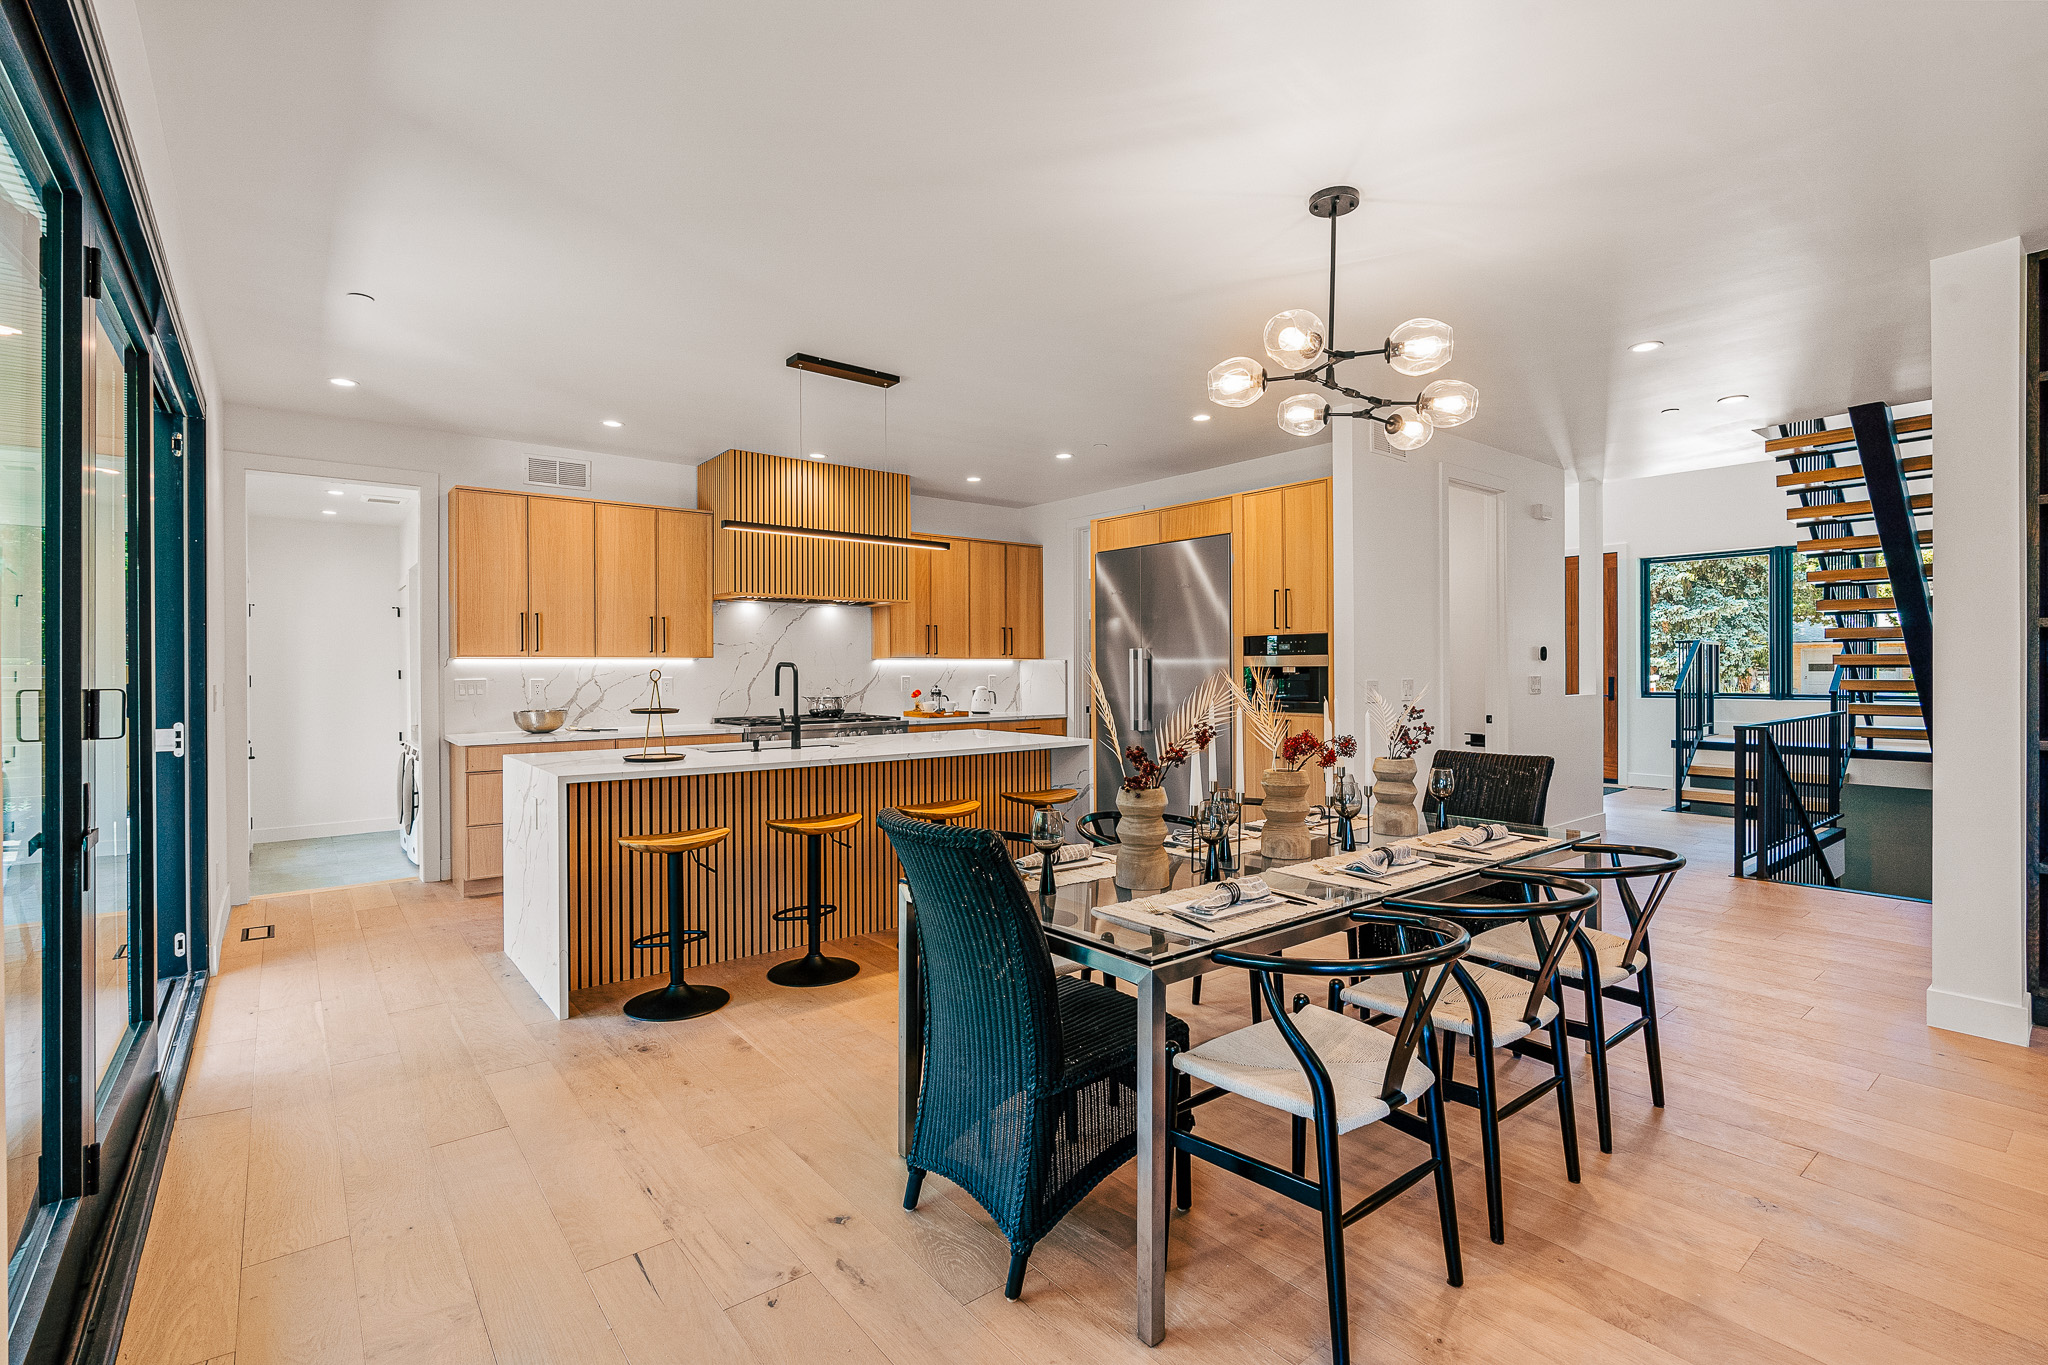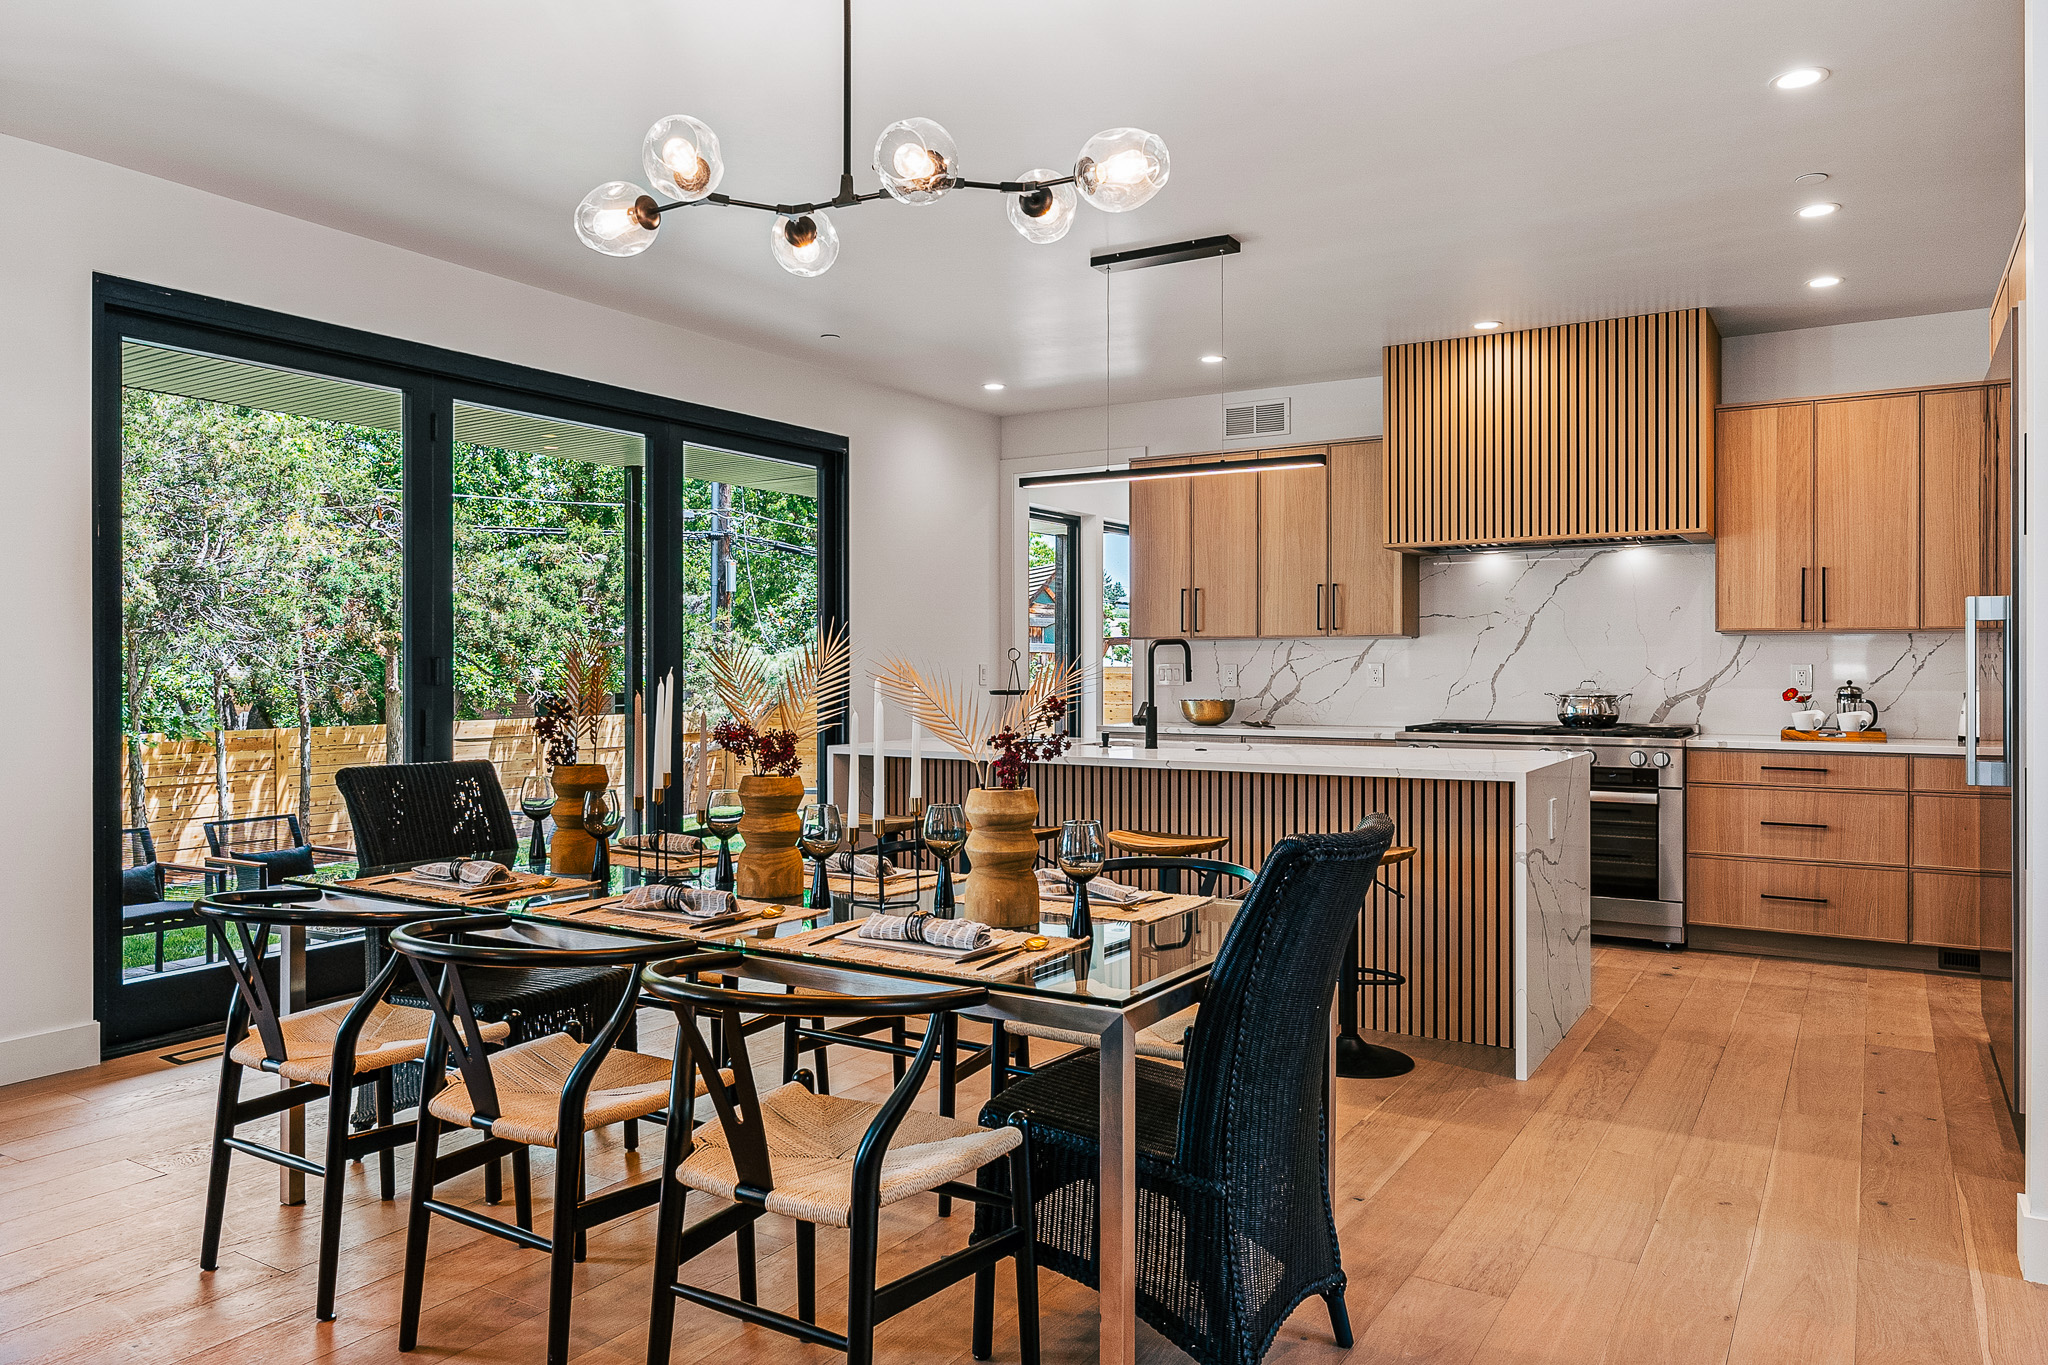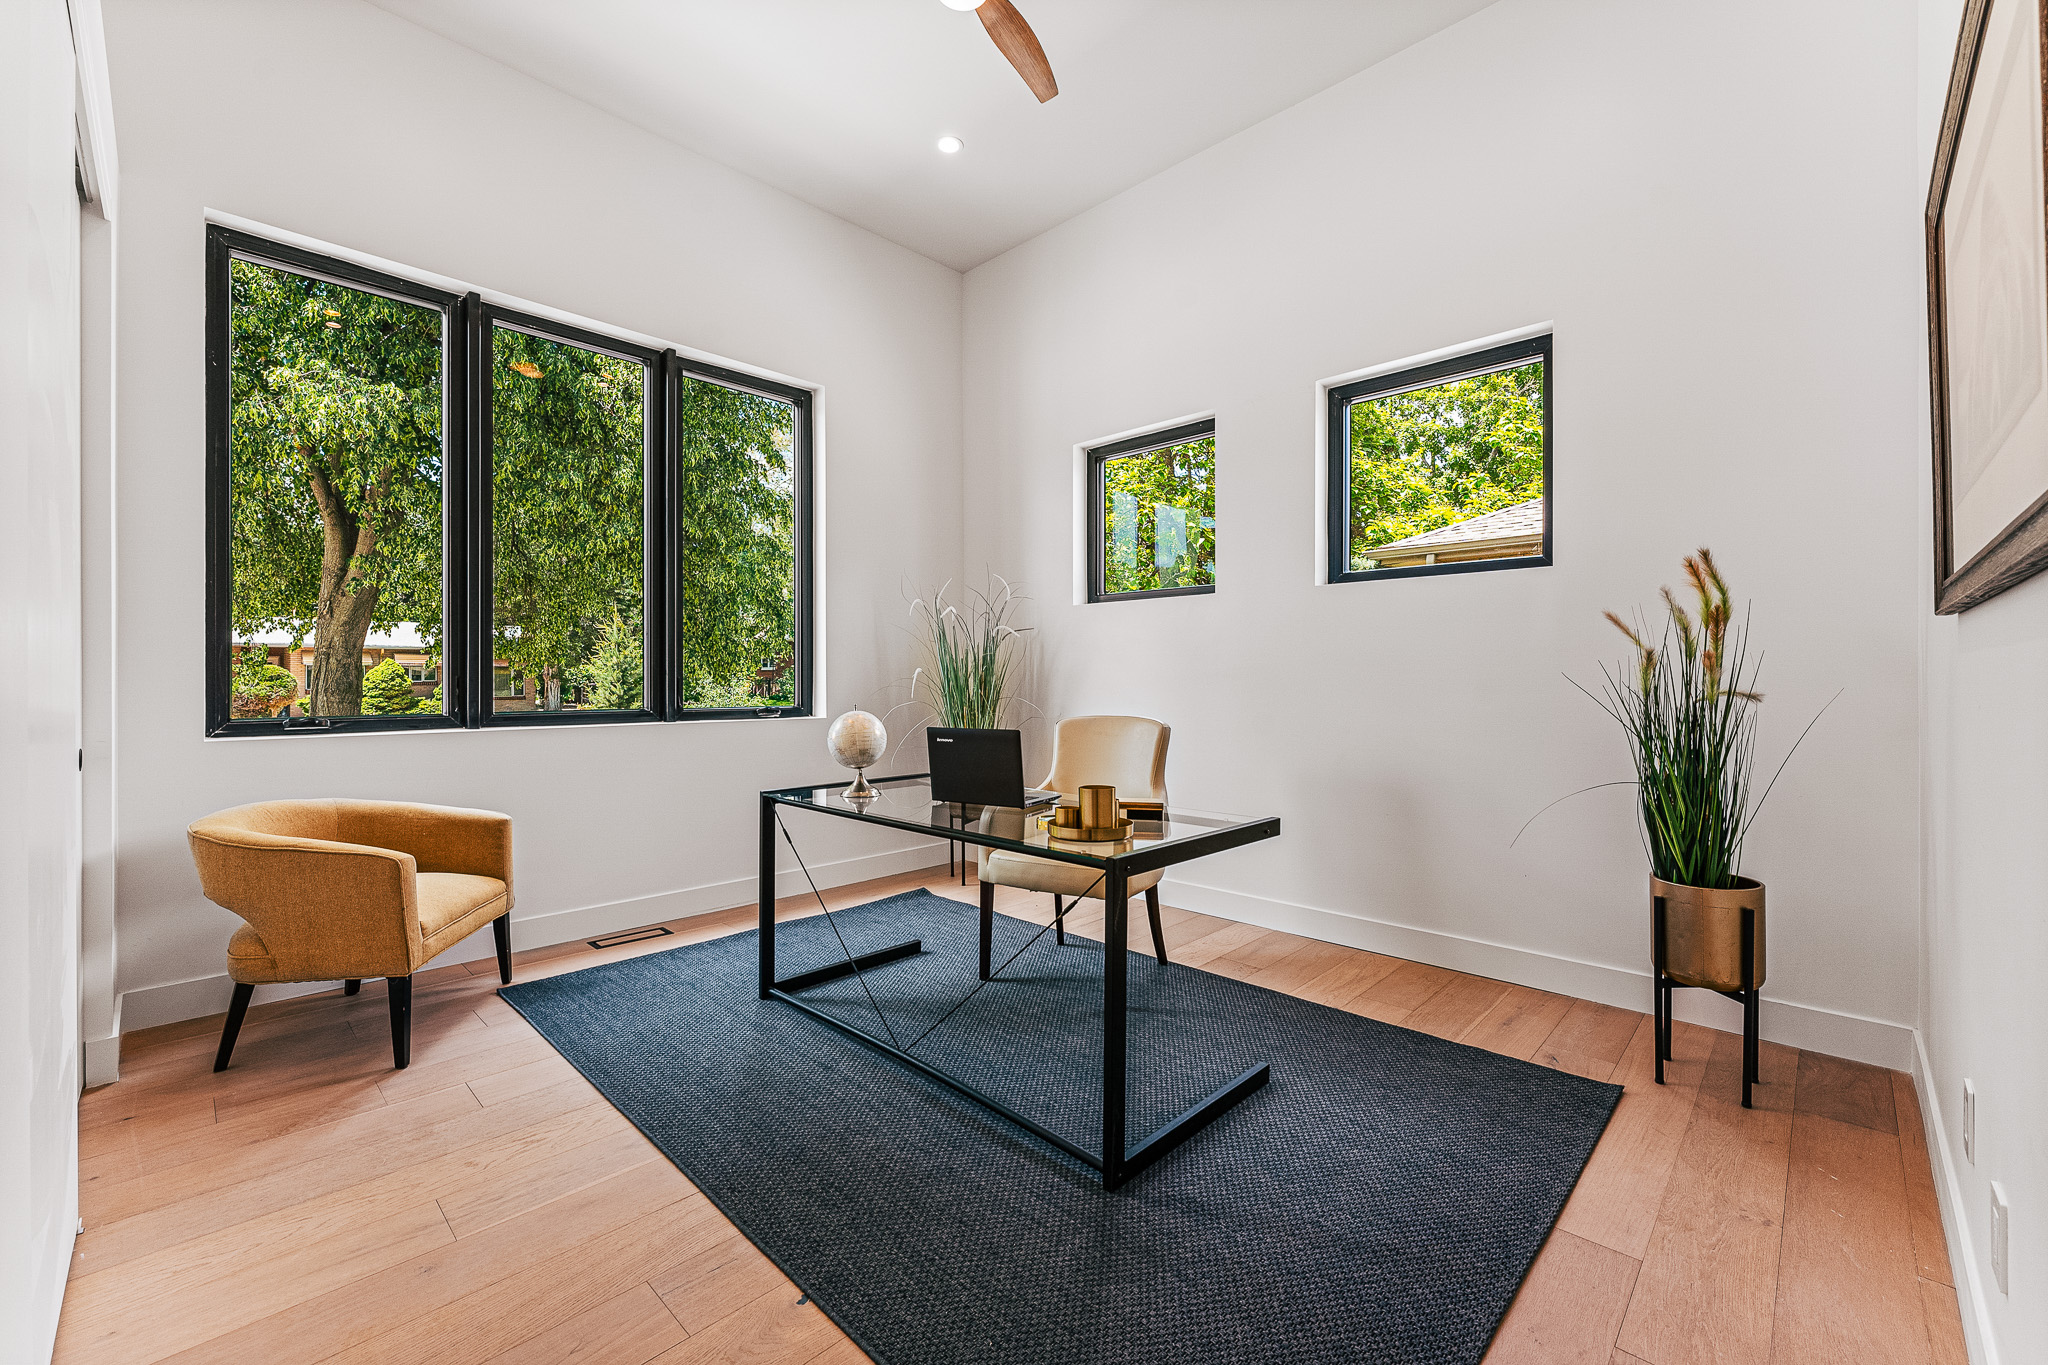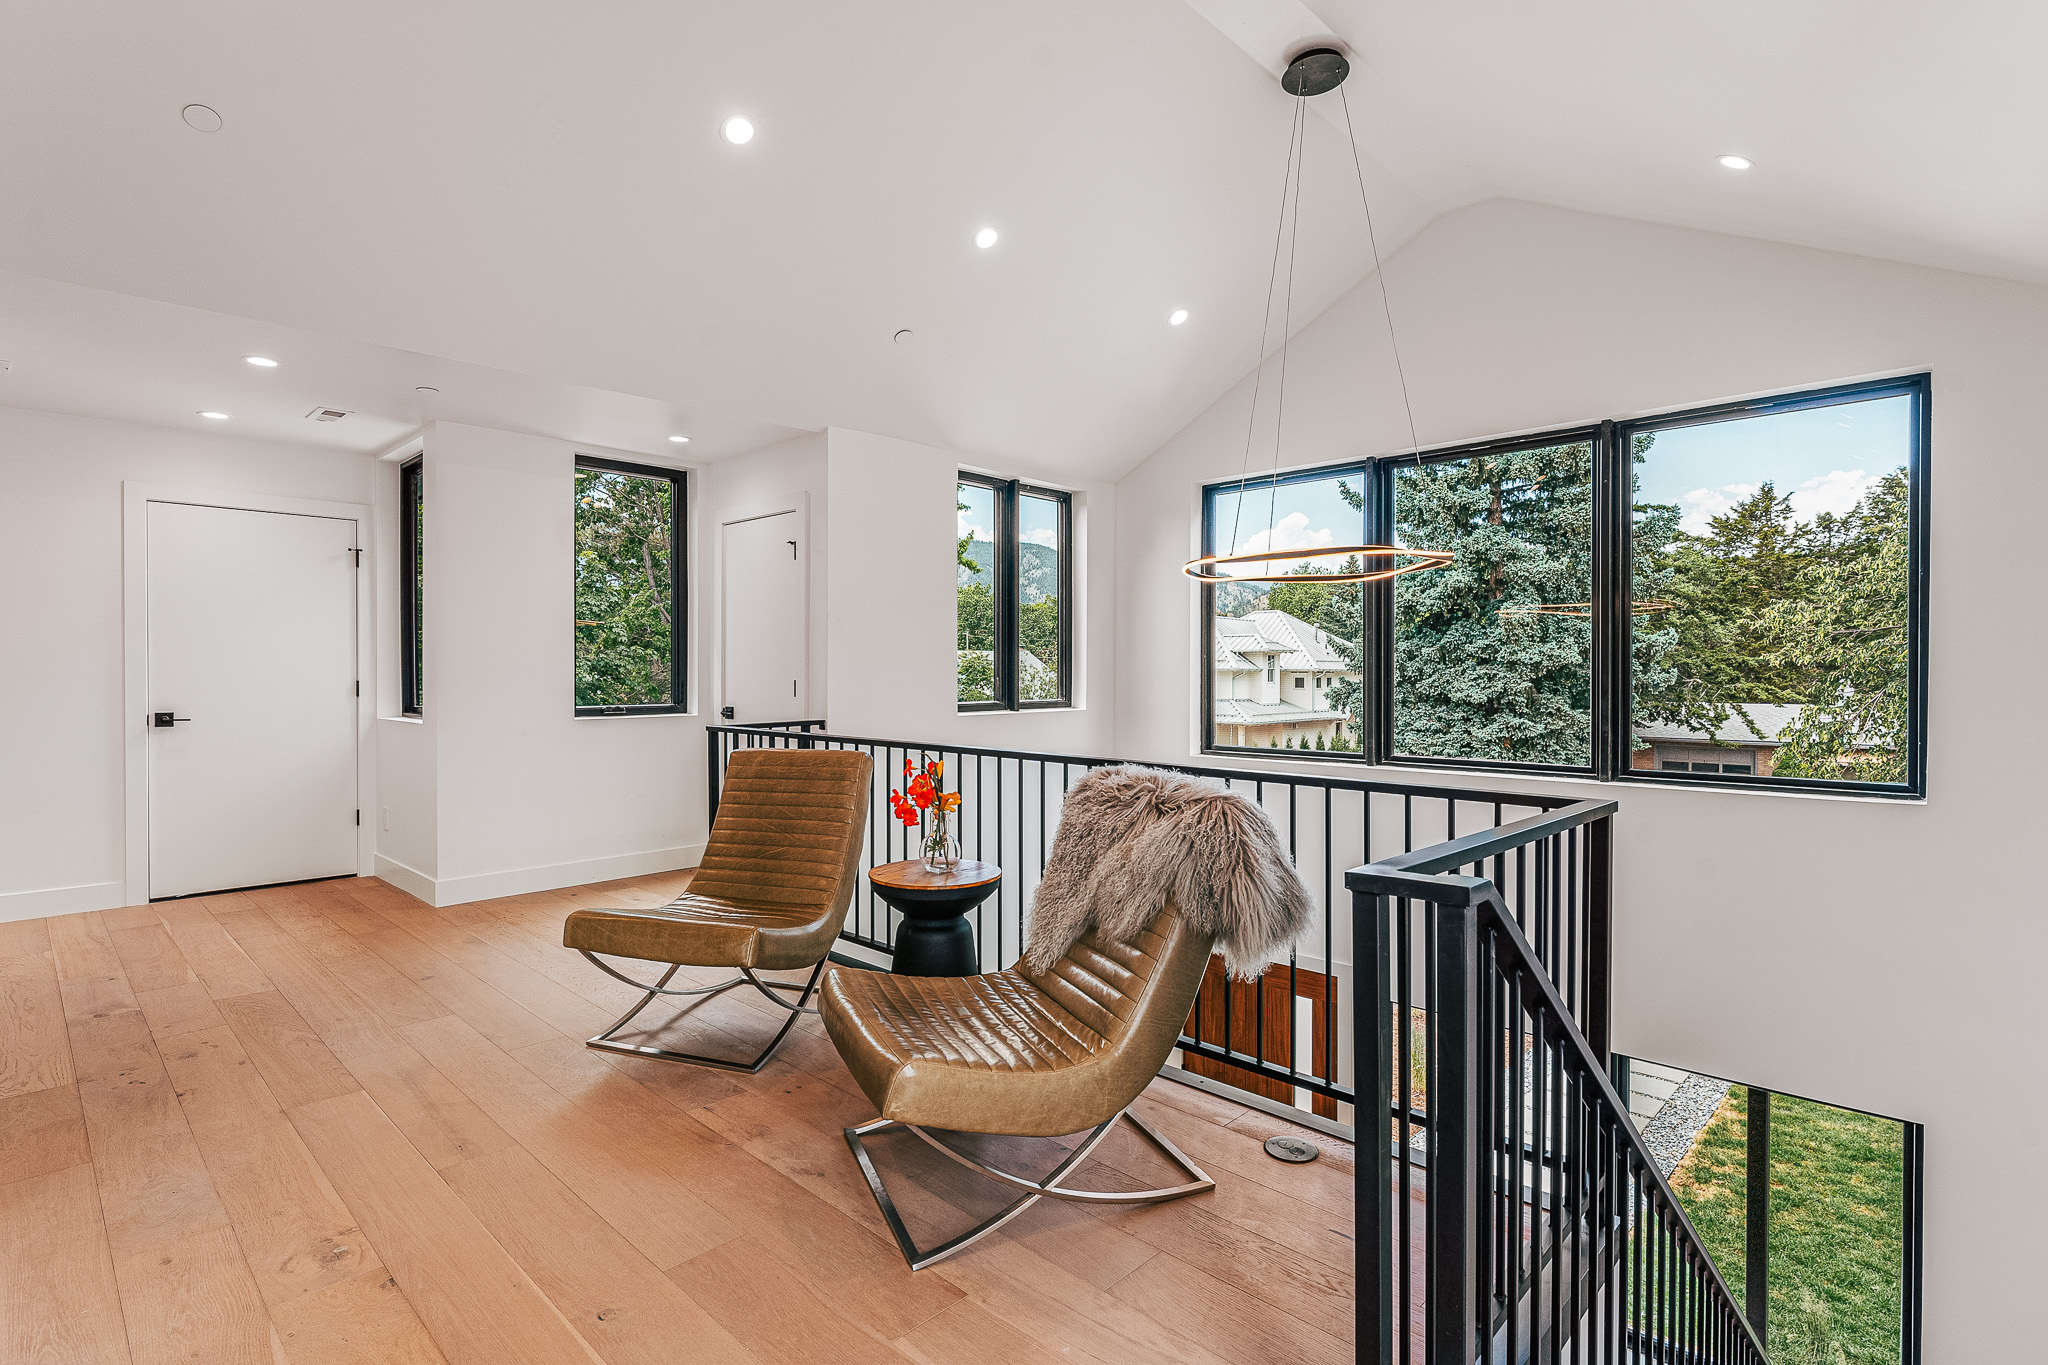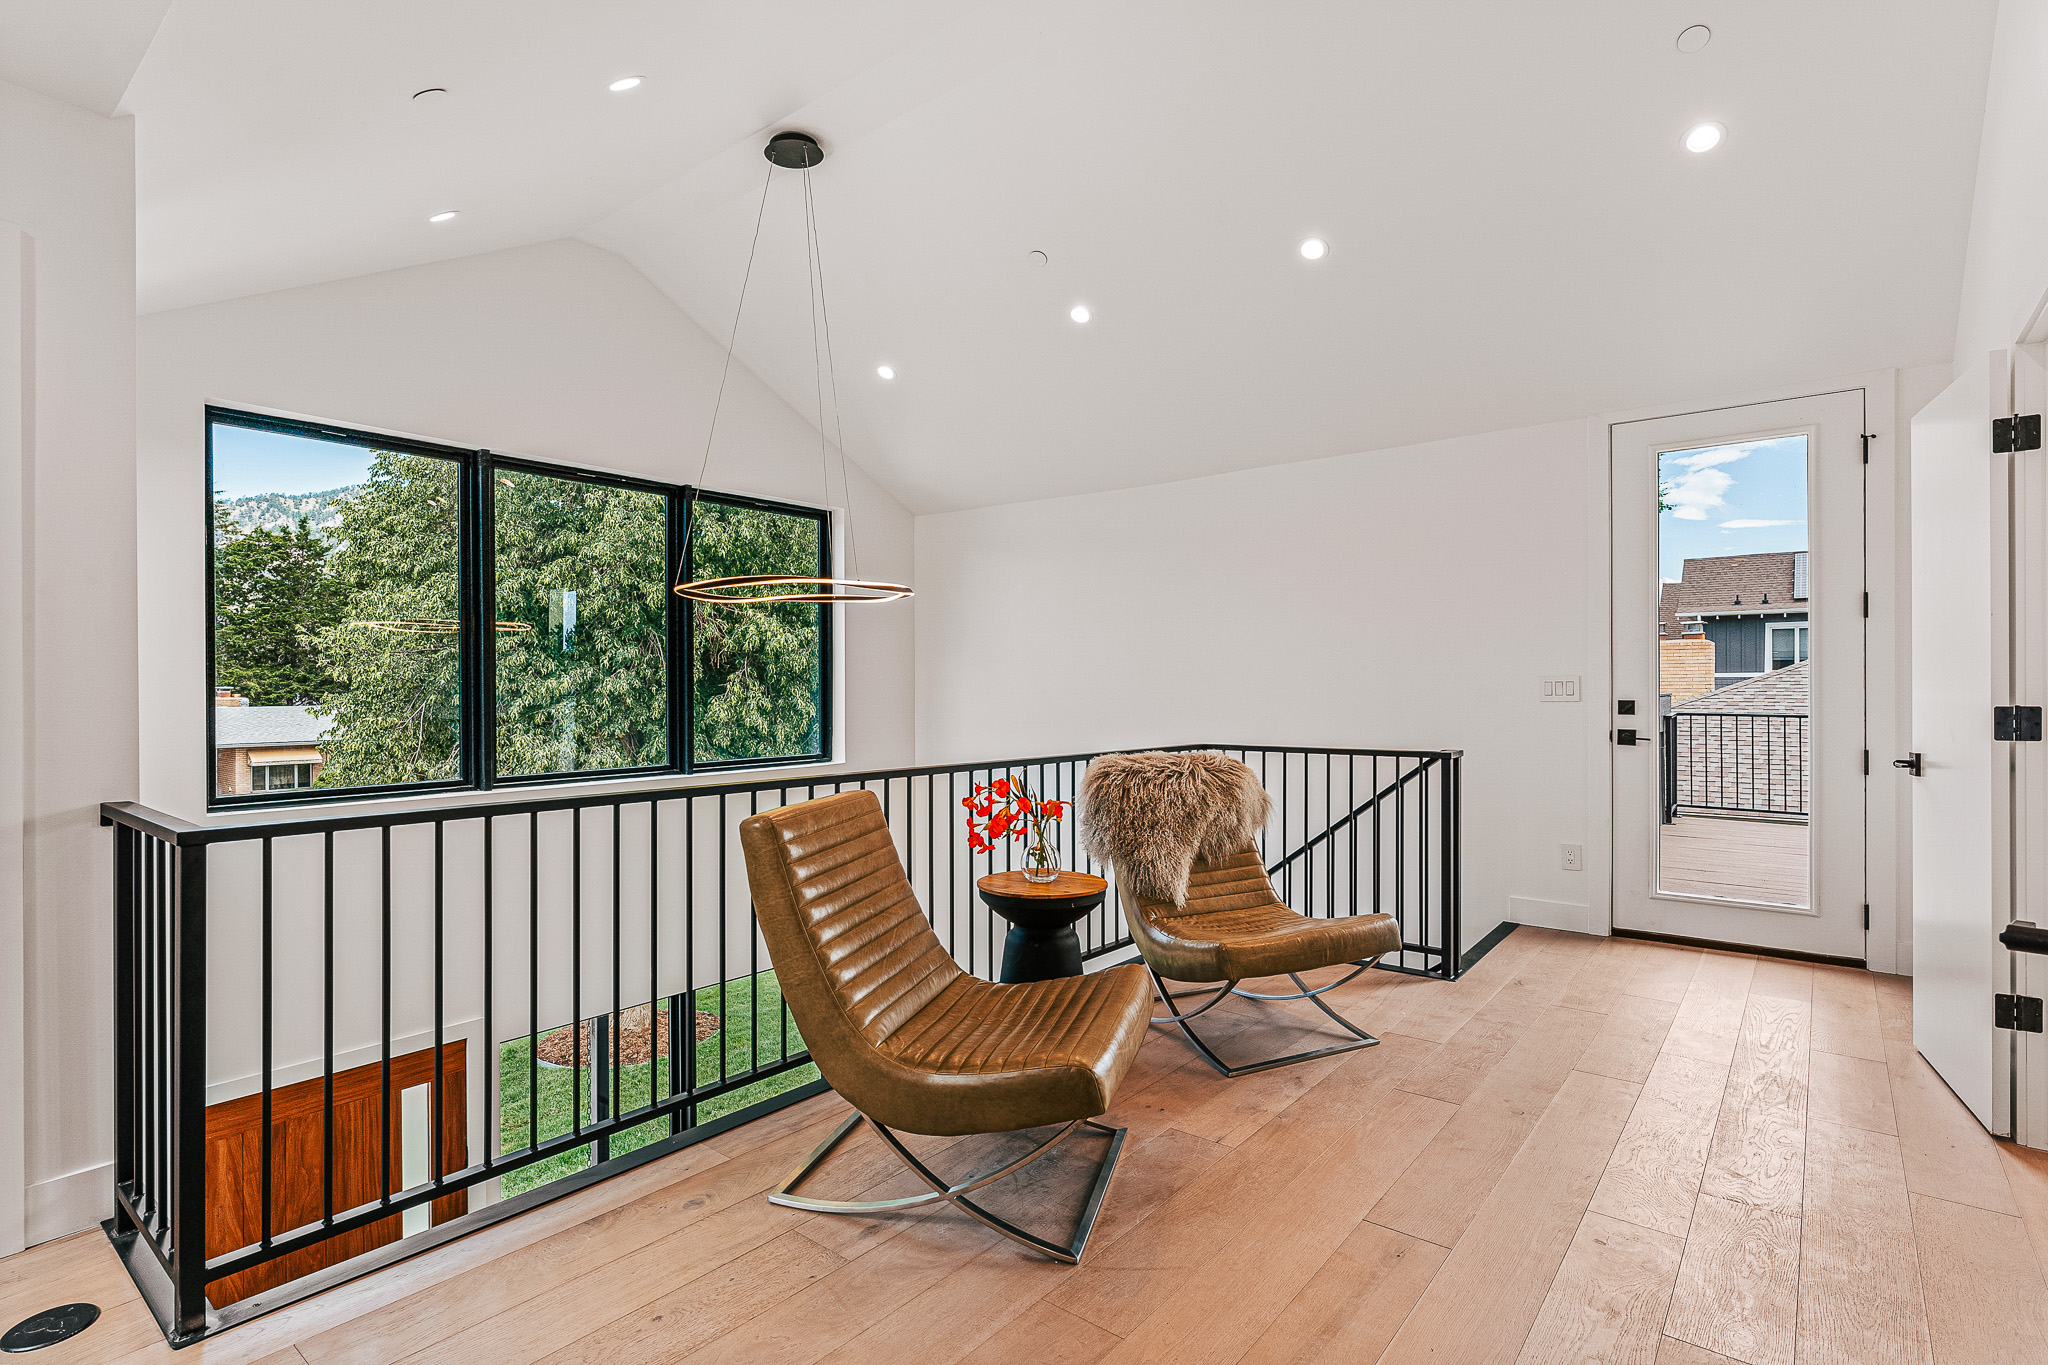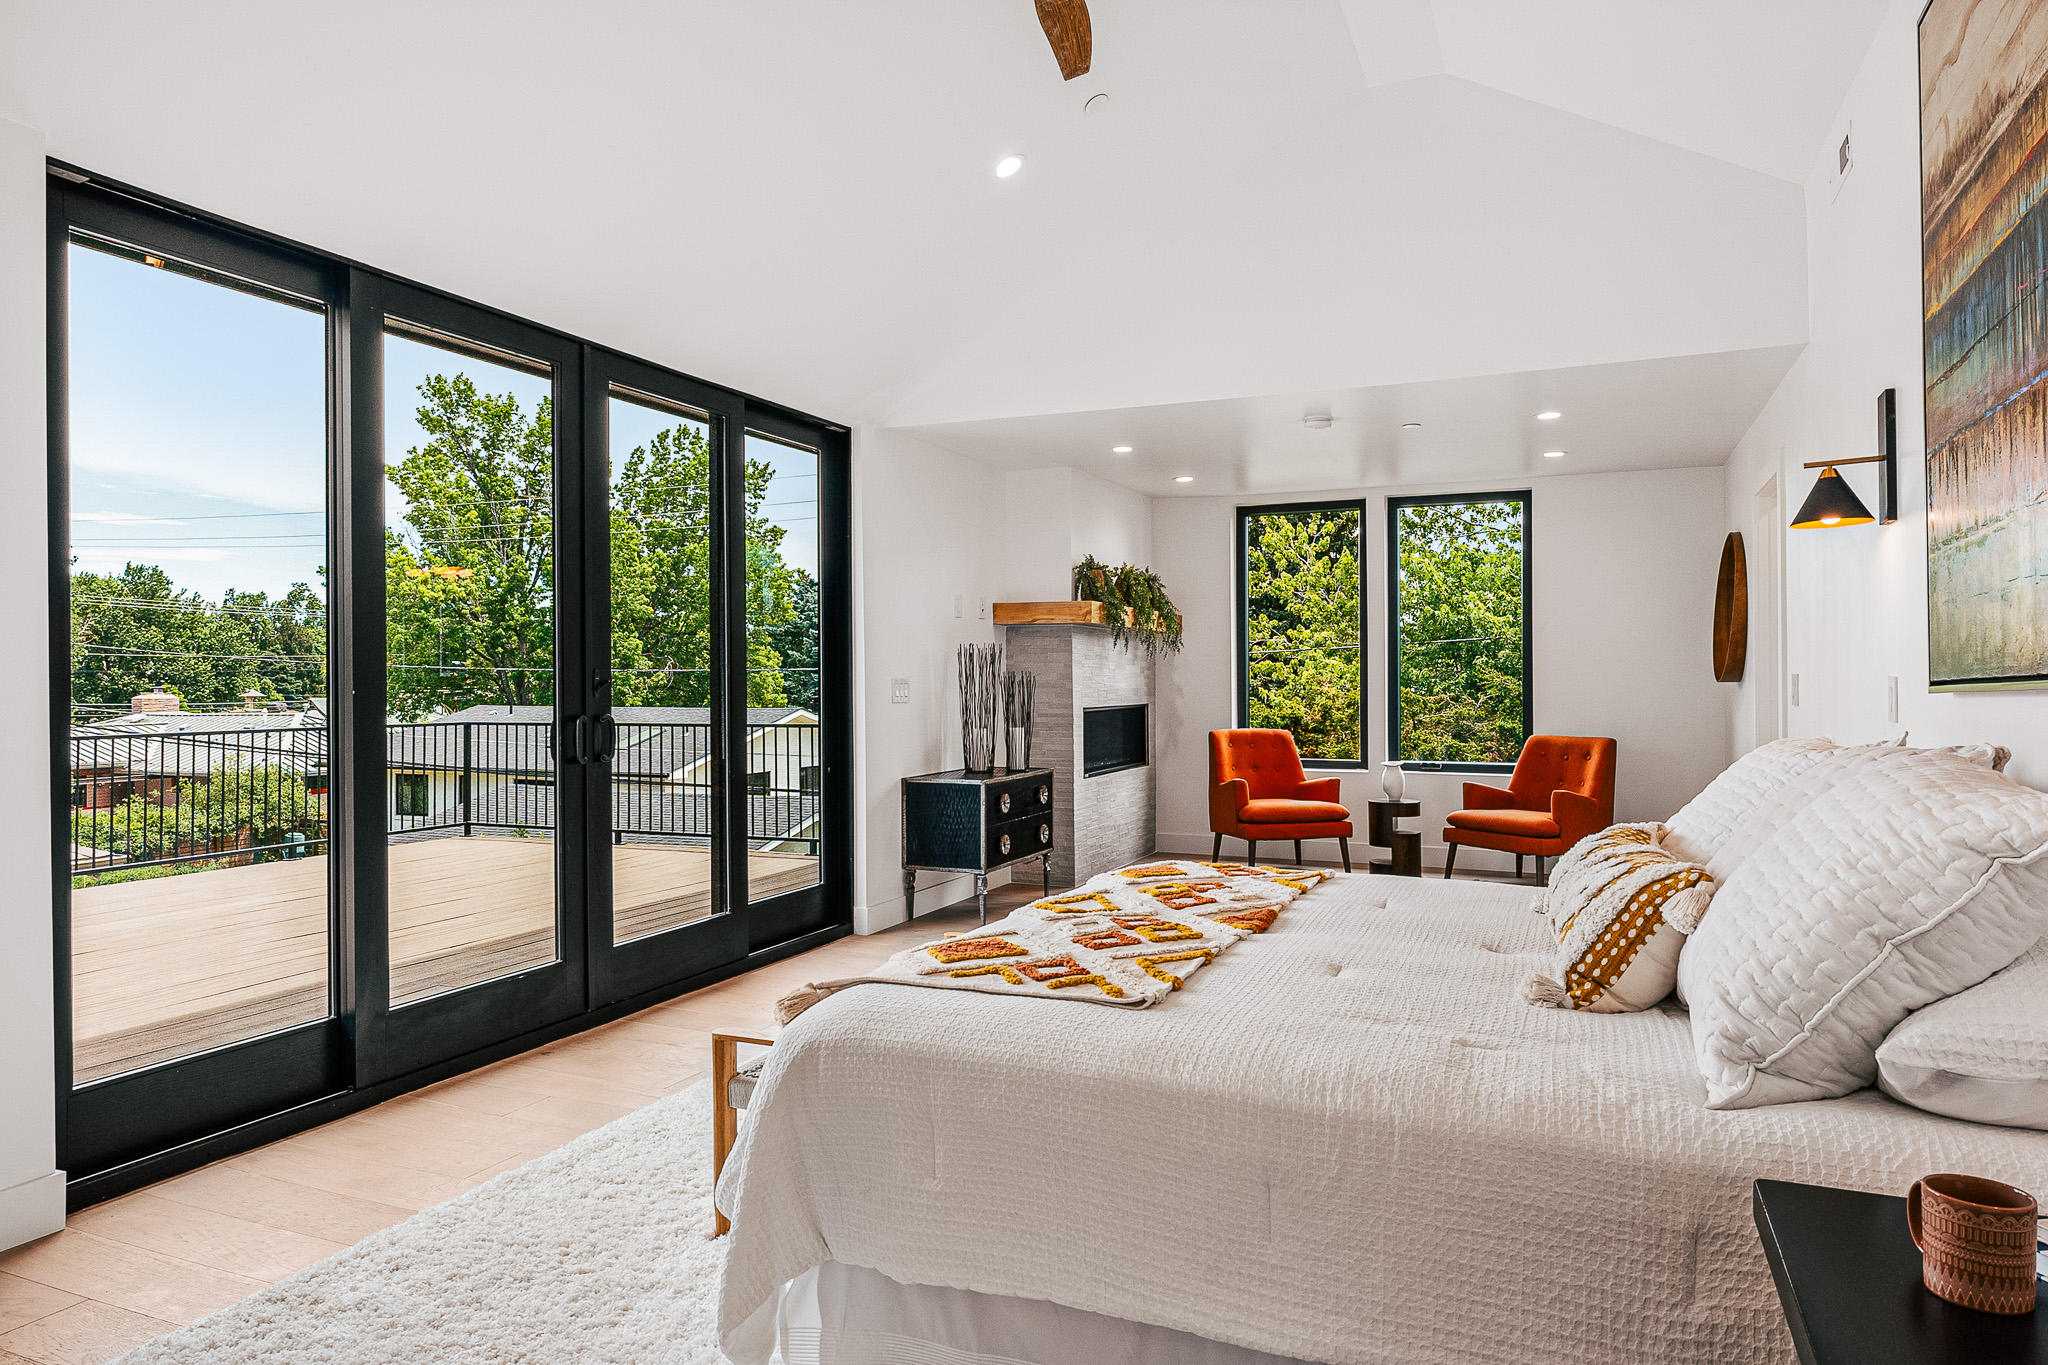
For many veterans and military families, finding the right home in Cheyenne can be challenging. While existing homes may offer a quick move-in timeline, veterans and their families often find themselves compromising on space, layout, or other features they need for their long-term needs.
Taking advantage of your VA loan benefits to build a custom home gives you the ability to design a space around your needs from the beginning—whether that’s the number of bedrooms, your own home office, better accessibility, or better energy efficiency.
For eligible veterans, VA construction loans can make building a realistic and preferred option.

Building with a Custom Home with a VA Construction Loan
Many veterans are familiar with using VA loans to buy a home, but fewer realize their benefits may also be used toward new construction—and even toward the land purchase with certain lending programs.
A VA construction loan allows eligible veterans and service members to finance the construction of a new custom home while taking advantage of many of the benefits of VA financing, like:
- The potential for little to no down payment
- No private mortgage insurance requirement
But building with a VA loan does require more planning and coordination than a traditional home purchase. That’s why choosing a builder who’s experienced with VA loans will help tremendously through this process. Below is a step-by-step guide for the general timeline of getting started with a custom build or a semi-custom home in Cheyenne, WY.
How Does it Work to Build a Custom or Semi-Custom Home with a VA Construction Loan?
1. Get Pre-Approved with a VA-Approved Lender
The process begins by speaking with a lender who offers VA construction loans. They will review your military eligibility, finances (income, debts, credit, etc.), and budget to determine what you can comfortably afford.
2. Choose Your Homesite—And Your Builder
Once you understand your budget, you can determine where you want to build. In Cheyenne, this may include neighborhoods within the city limits or larger properties throughout the surrounding area that can offer you more space and privacy. (If you own land already, that’s great!)
This is also the ideal time to start interviewing a few builders. Involving your builder during the land acquisition stage and having them evaluate the soil conditions, grading requirements, utility availability, and setbacks can help you save time and money later in the process.
As you compare builders, look at their reviews, ask about their past projects and experience with VA, or even check out a few of their ongoing projects in person. Just as importantly, ask how they manage project budgets and timelines. Builders who offer a Guaranteed Maximum Price and Guaranteed Durations will make certain that your project will stay within the expectations set with your lender.
Learn More About Guaranteed Maximum Price & Duration Offered by PR Builders
3. Begin the Design Process
Once you have your land and have decided on your builder, it’s time to start developing your design! During this phase, you’ll work with your builder to develop a floor plan, select features and finishes, and establish a detailed construction budget.
Your options can include:
- A Custom Home: Have complete flexibility to design around your family, preferences, accessibility needs, and long-term goals, backed by a Guaranteed Maximum Price and Guaranteed Duration.
- A Semi-Custom Home: Have meaningful design input on layout and finishes while keeping the building process streamlined and working within a more modest budget. (Starting in the mid-$650K range)
As the plans are finalized, your builder and lender will work together to make sure your project aligns with your approved financing before construction begins.
4. Sign a Construction Contract & Close on Your Loan
Once your home plans, construction budget, and financing are finalized, you’ll sign your construction contract with your builder and close on your VA construction loan, which can cover 100% of the building cost. At closing, your lender finalizes the loan documents, confirms the project’s budget and plans, and authorizes construction to begin. With financing in place and approvals complete, your builder can move forward with the project.
5. The Construction Process & Transition to Mortgage
With construction underway, your lender releases funds to your builder through scheduled construction draws as each phase of the work is completed.
Once construction is complete and the home passes its final inspections, the construction loan transitions into your permanent VA mortgage. Depending on your loan program, you may not begin making regular mortgage payments until your new home is finished and you’re ready to move in!

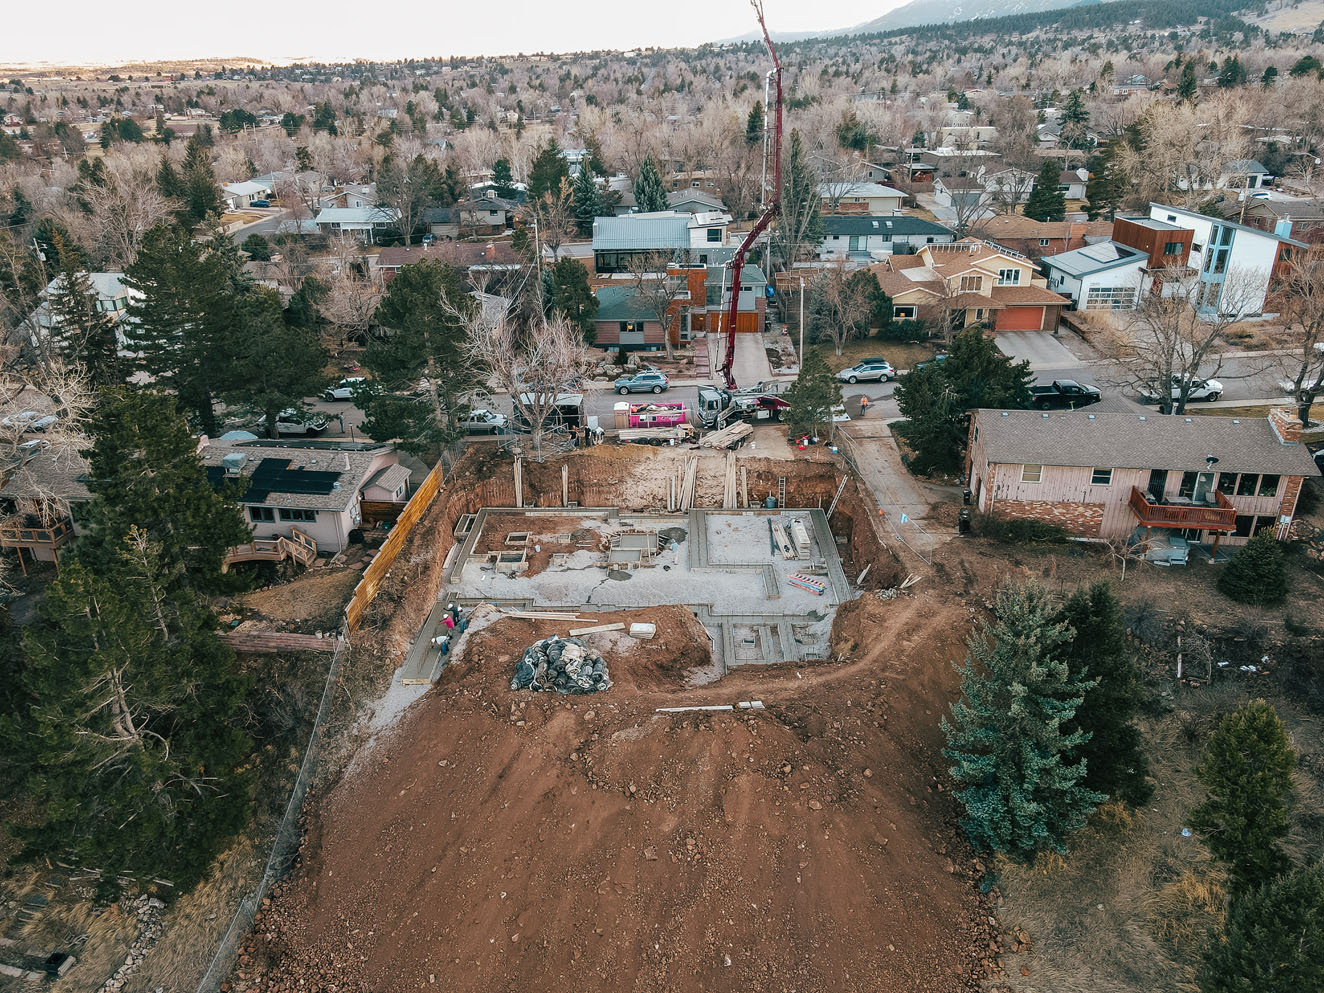
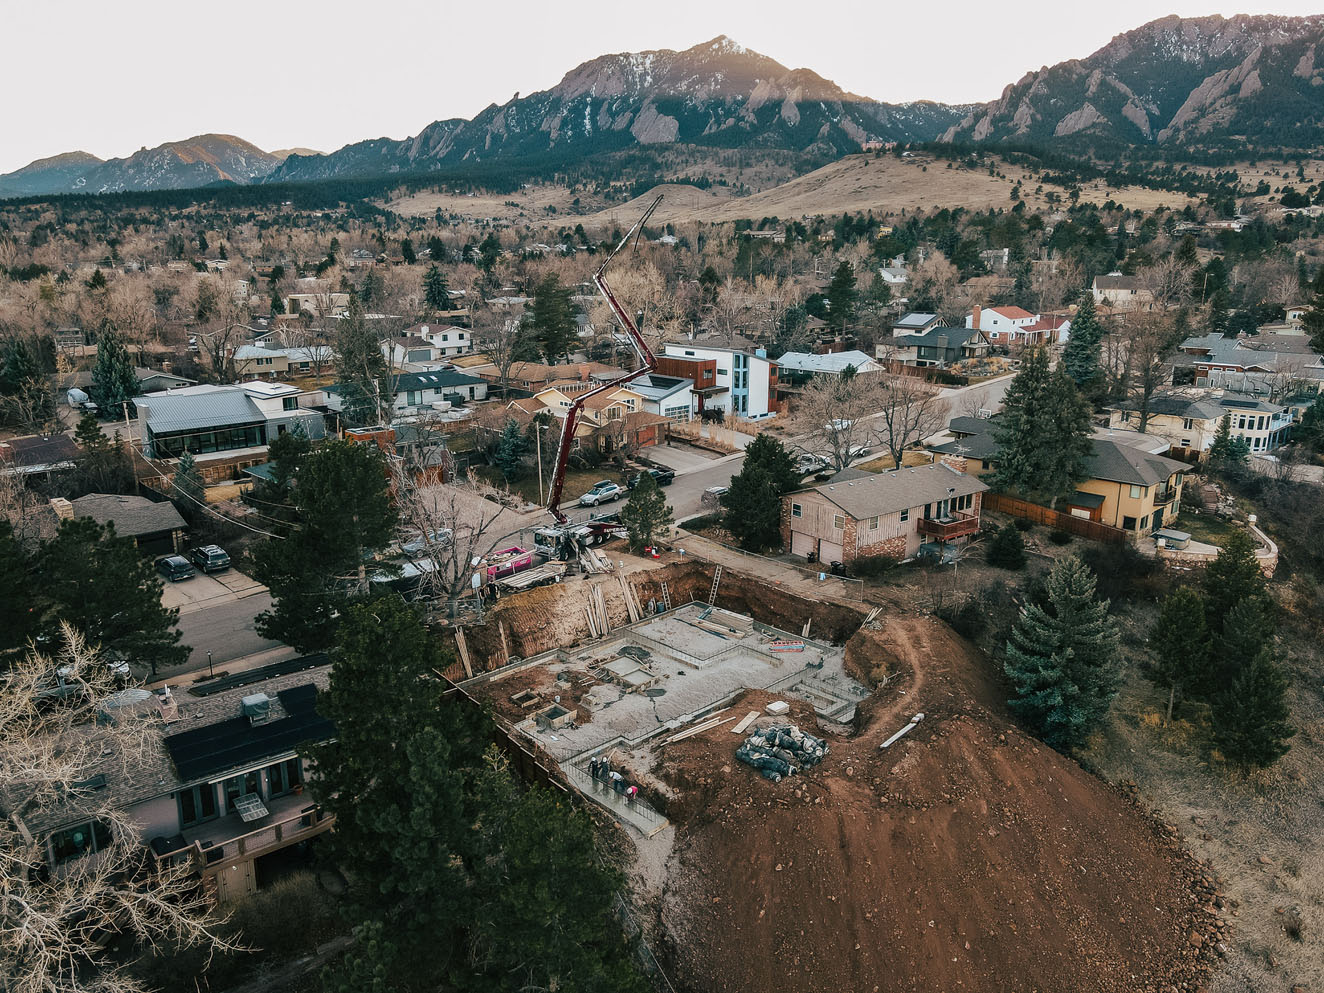
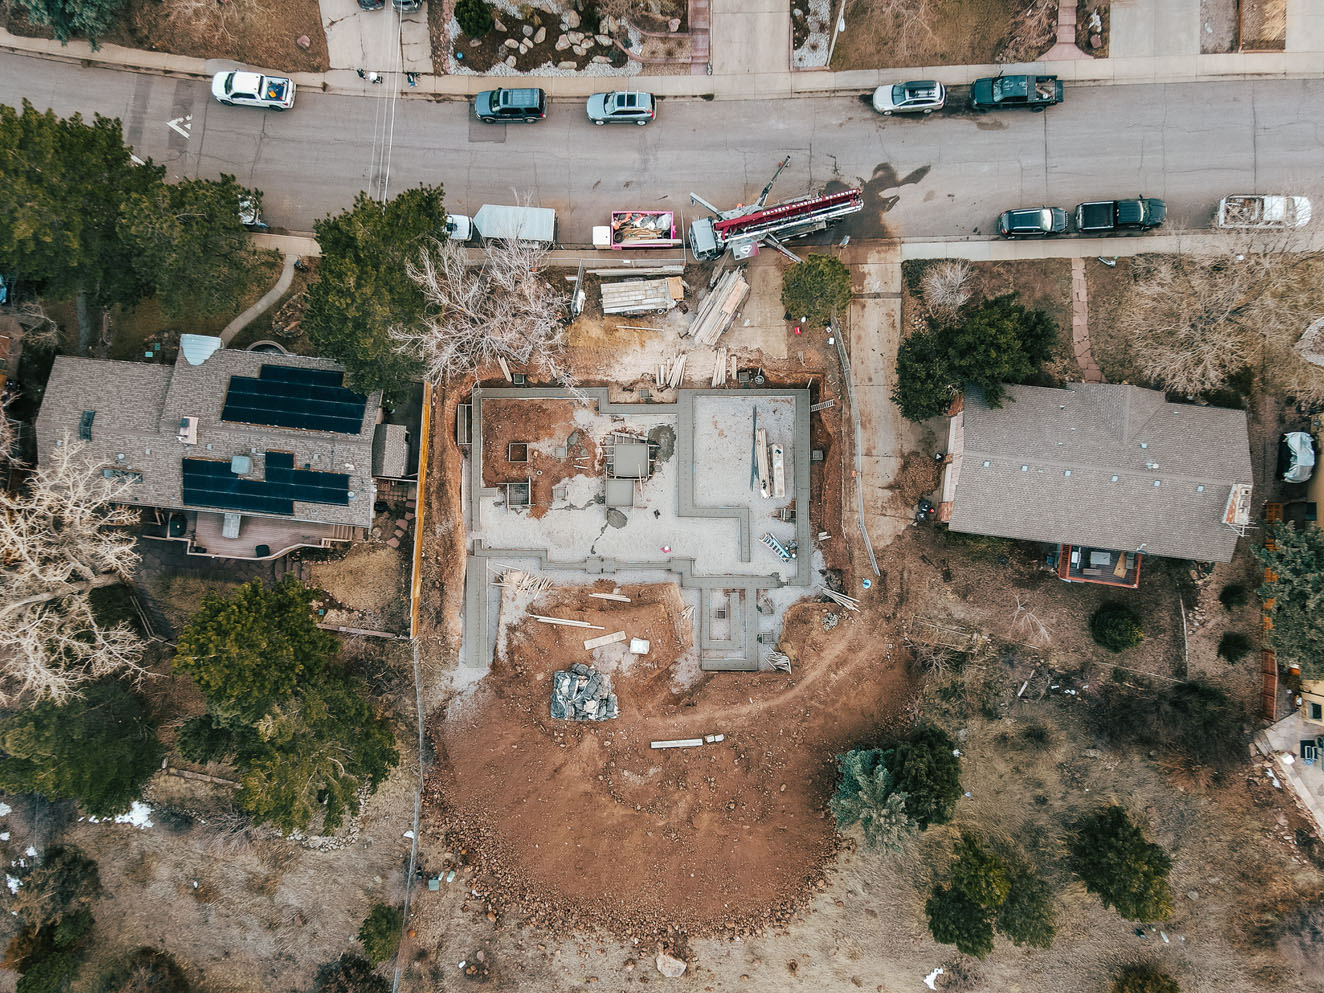
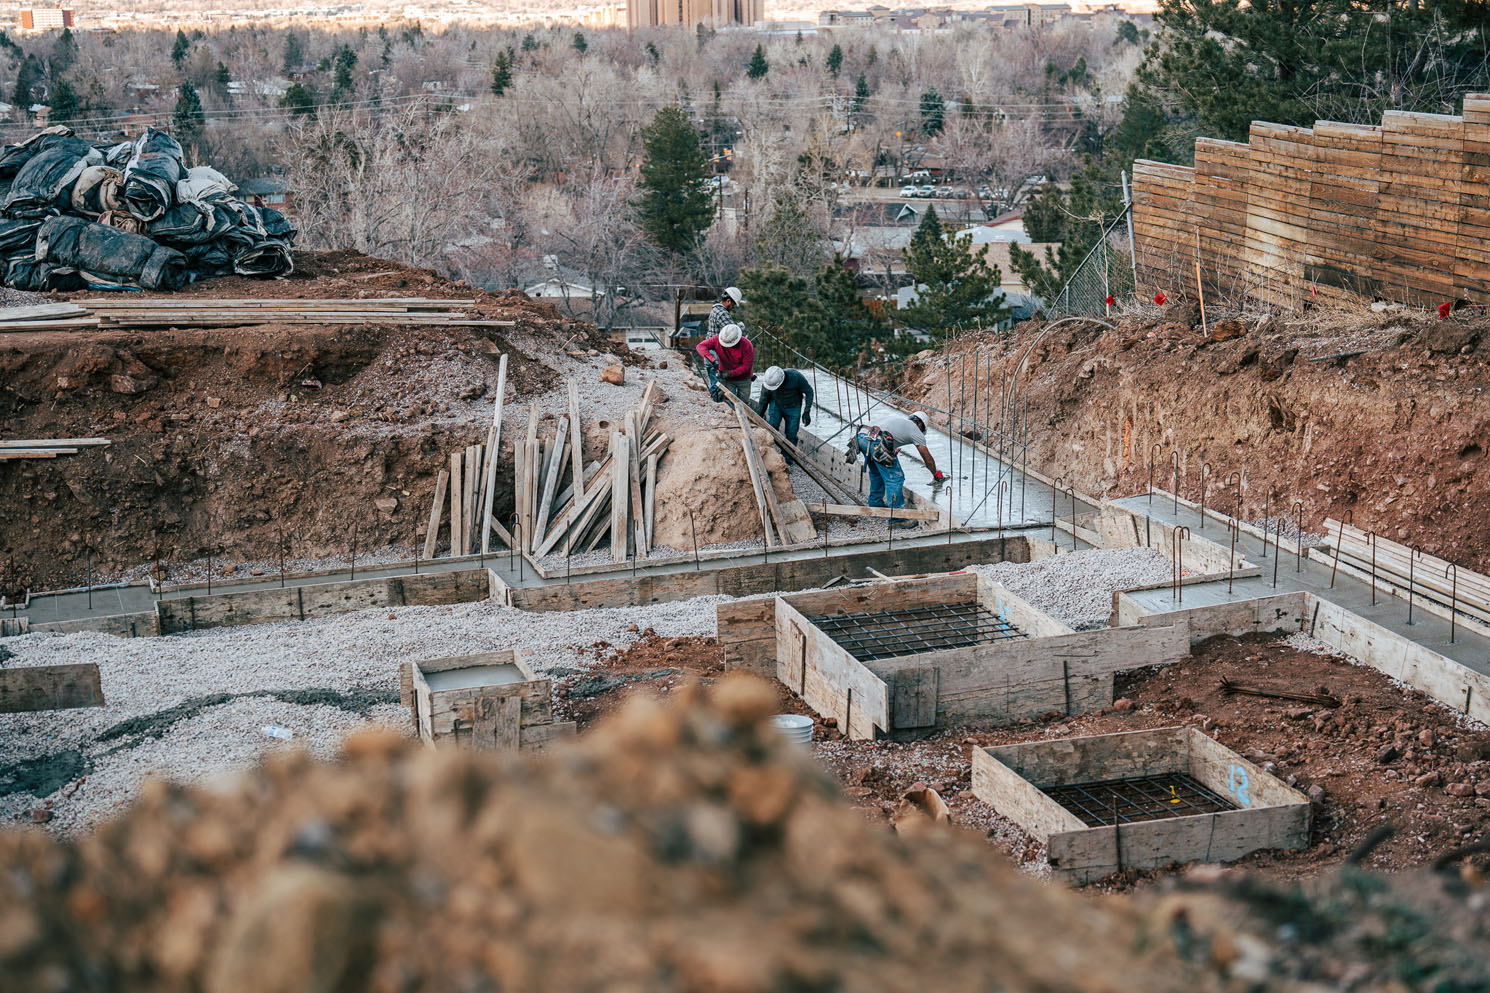
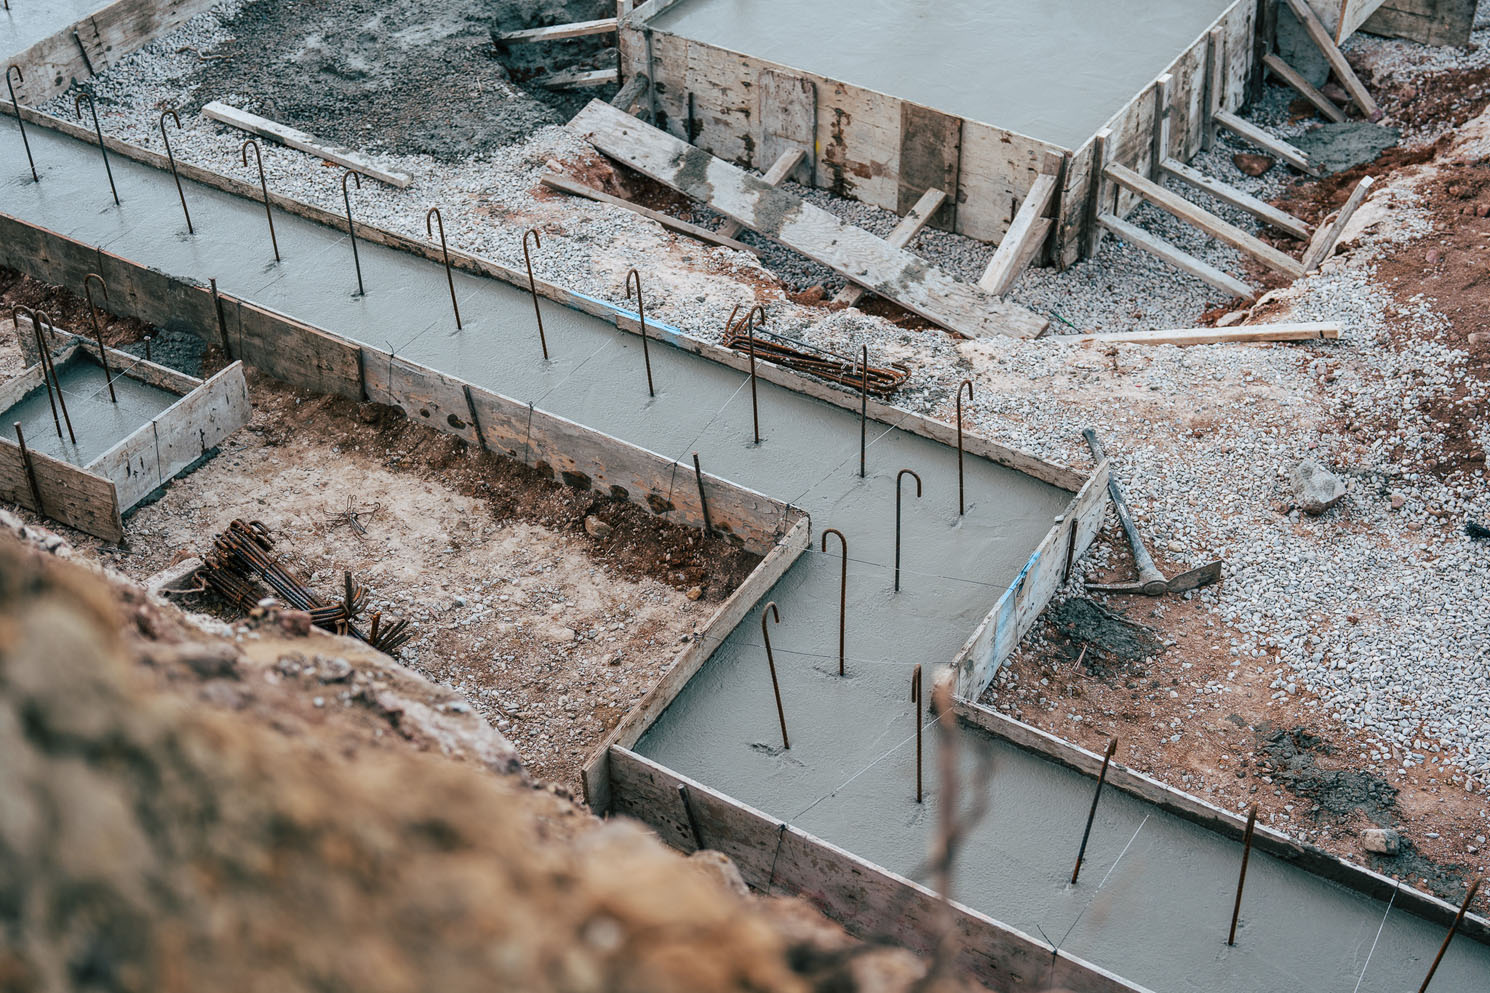
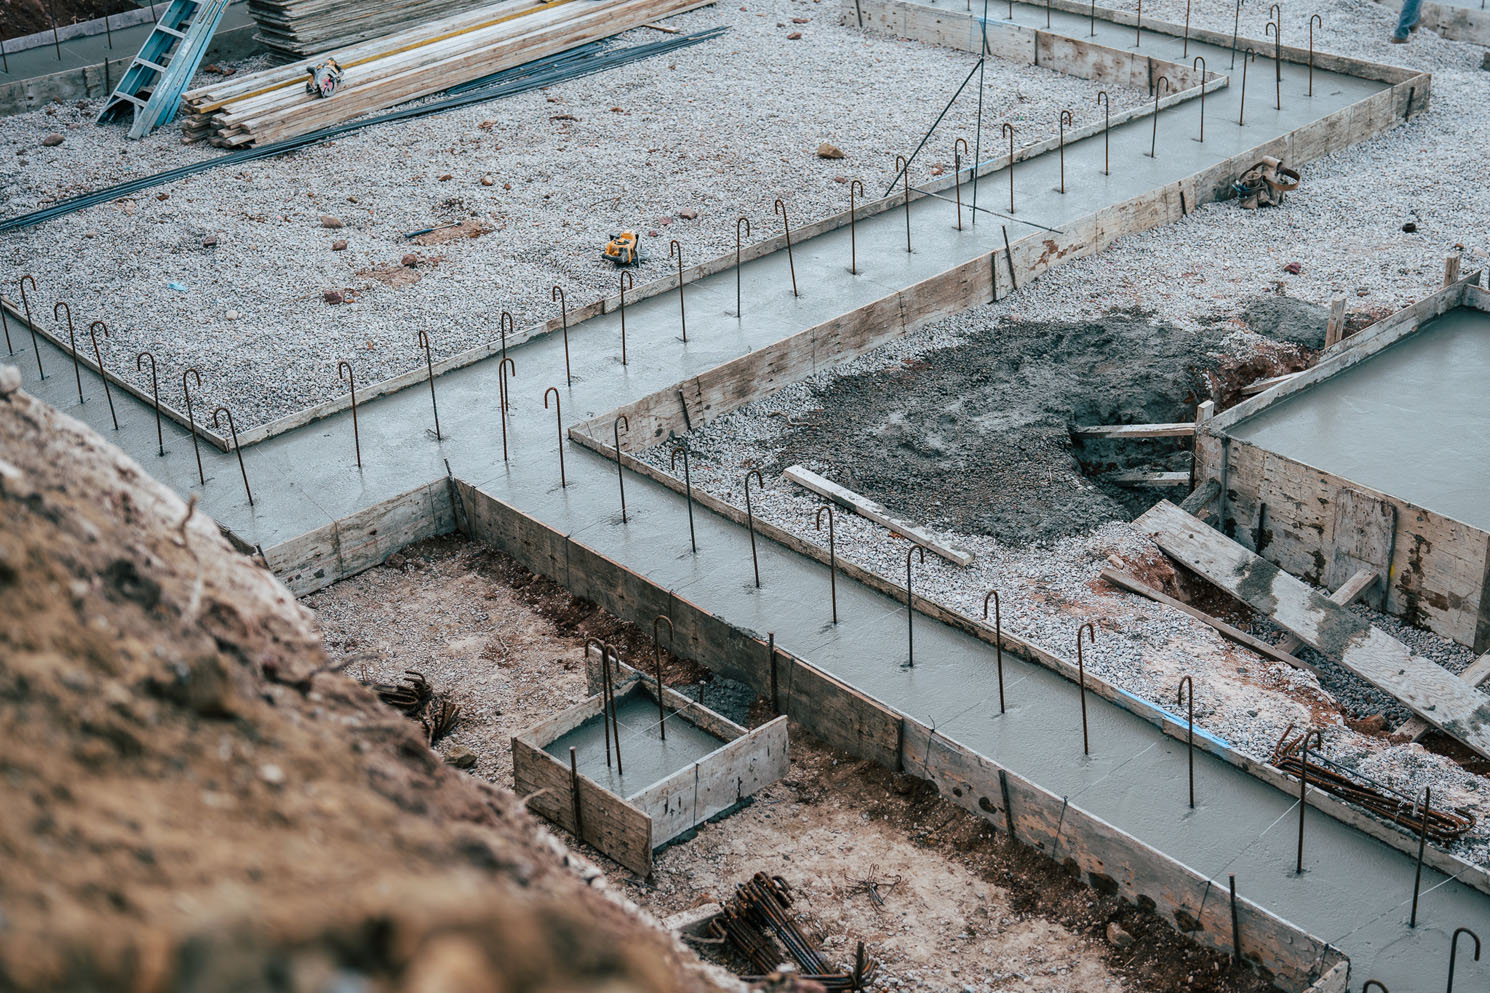
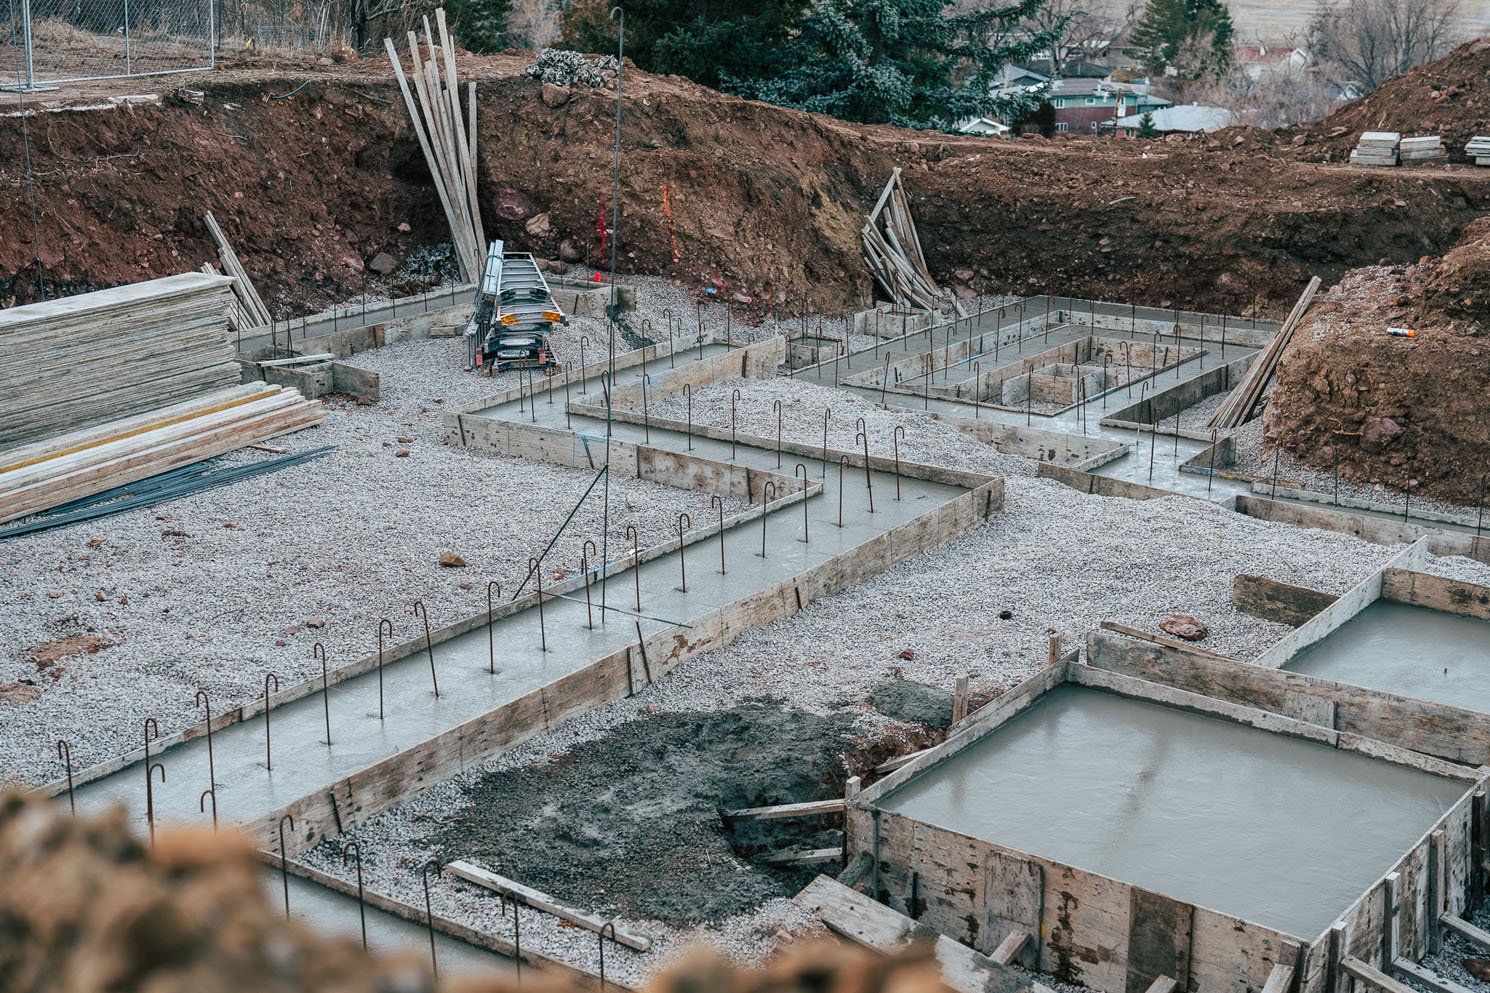
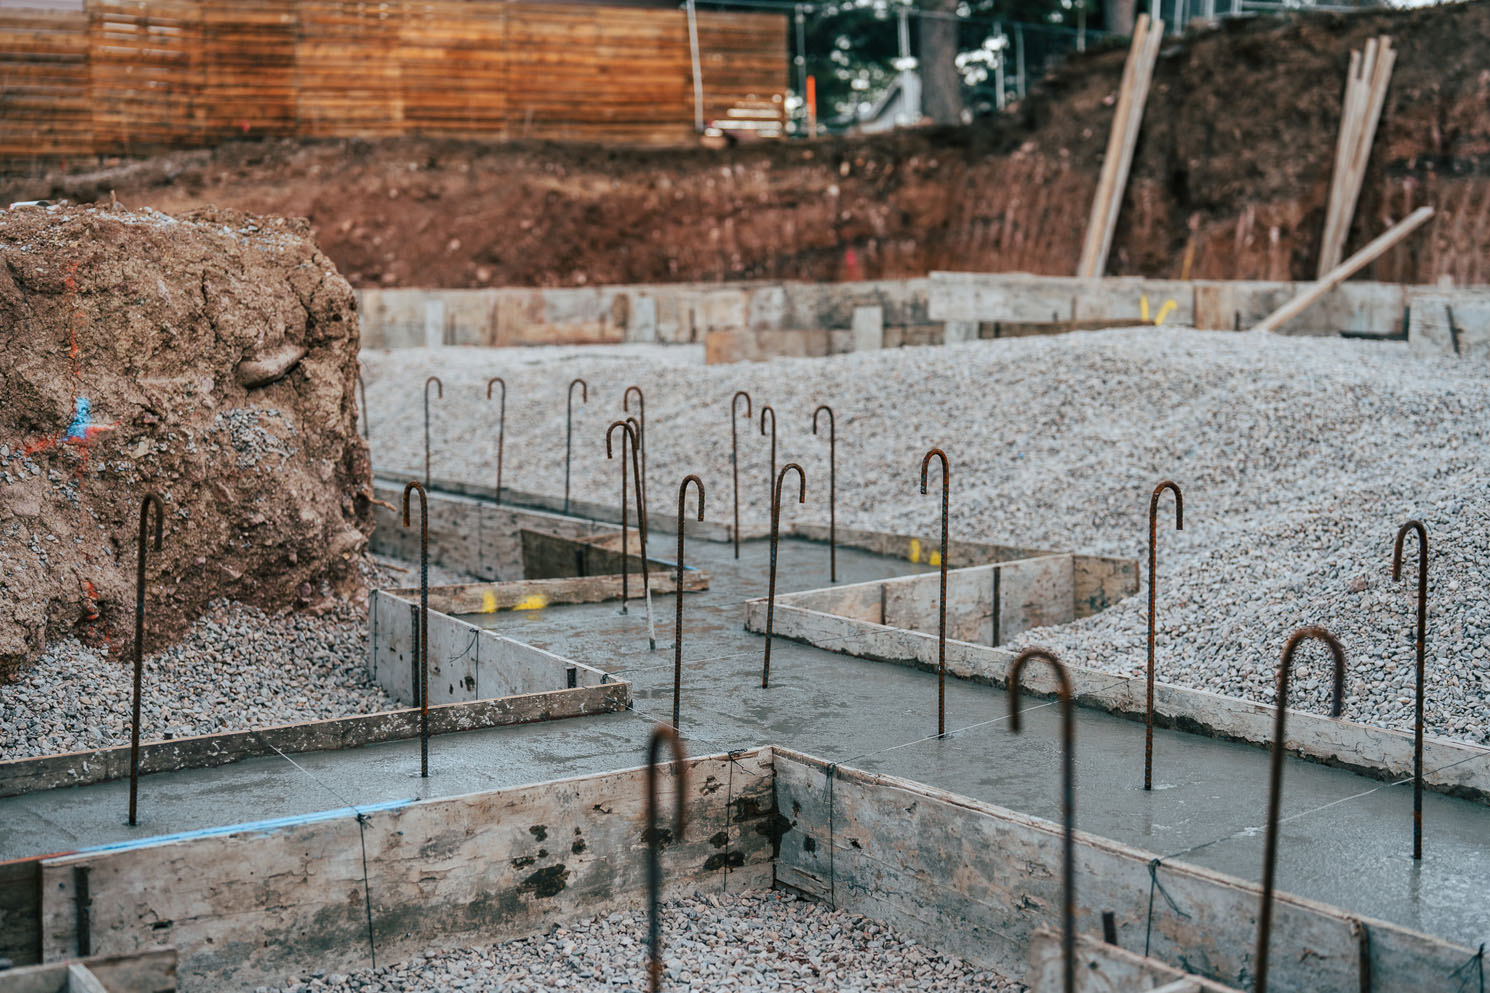
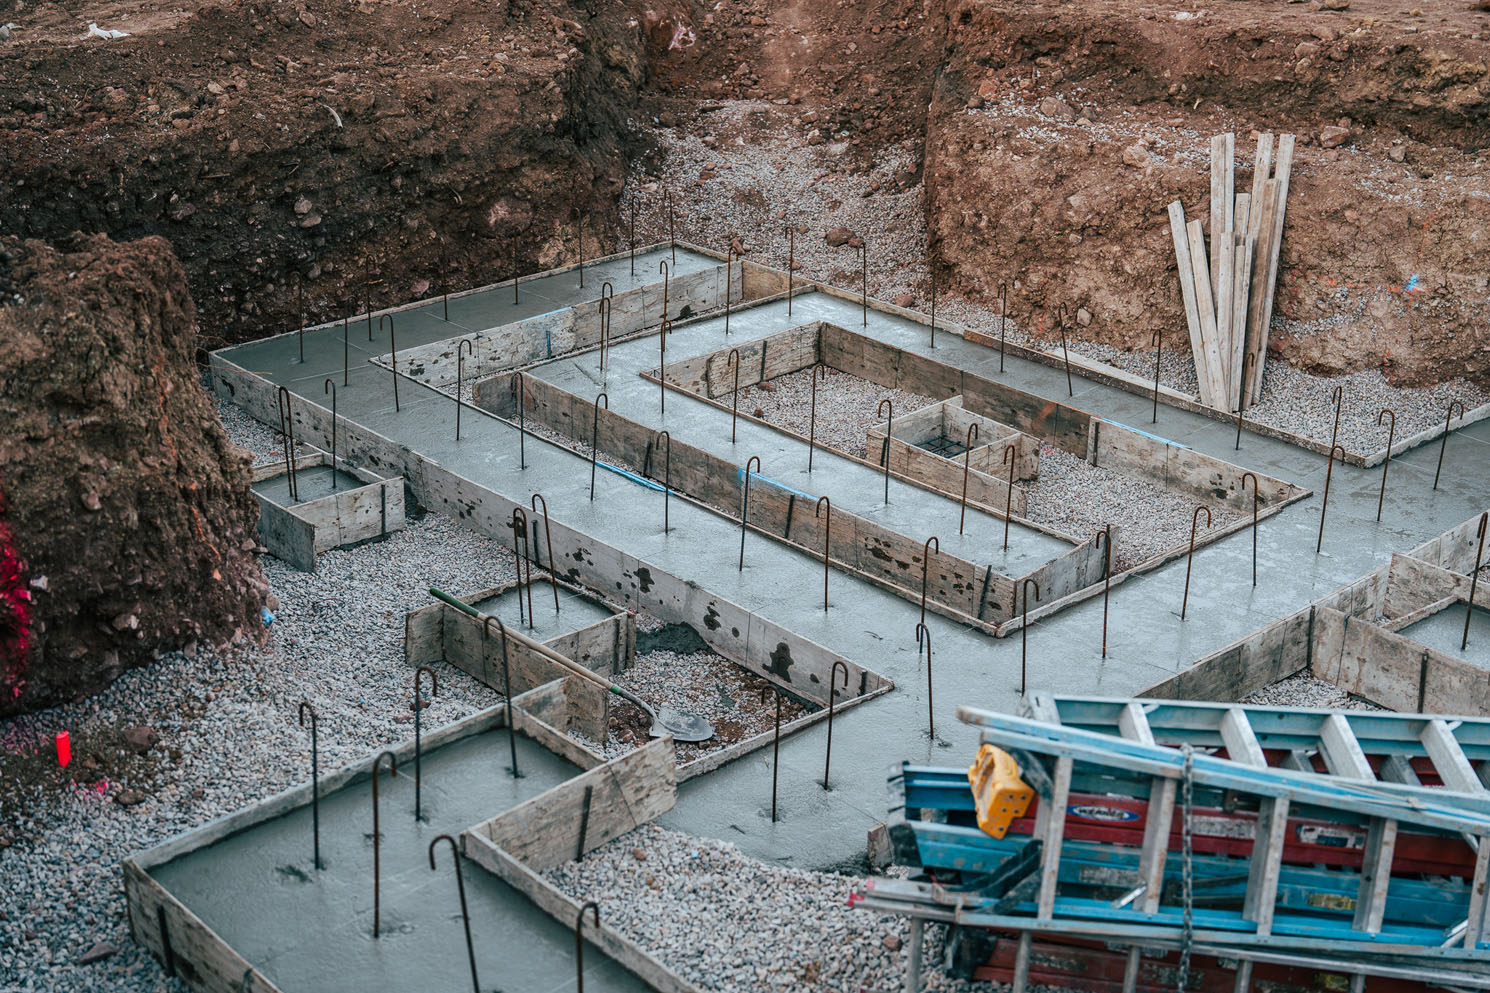
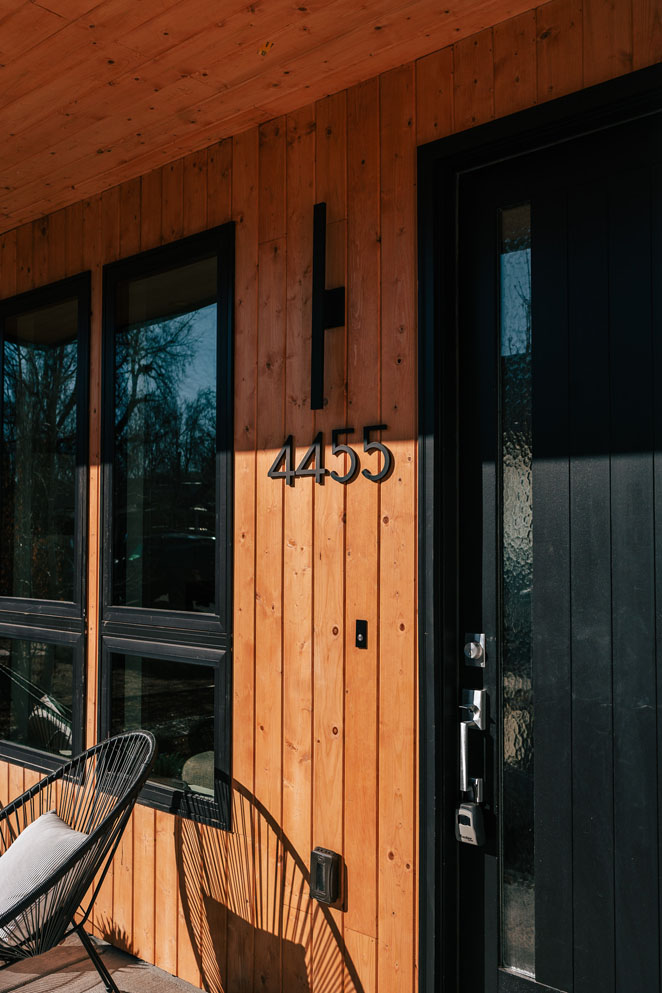
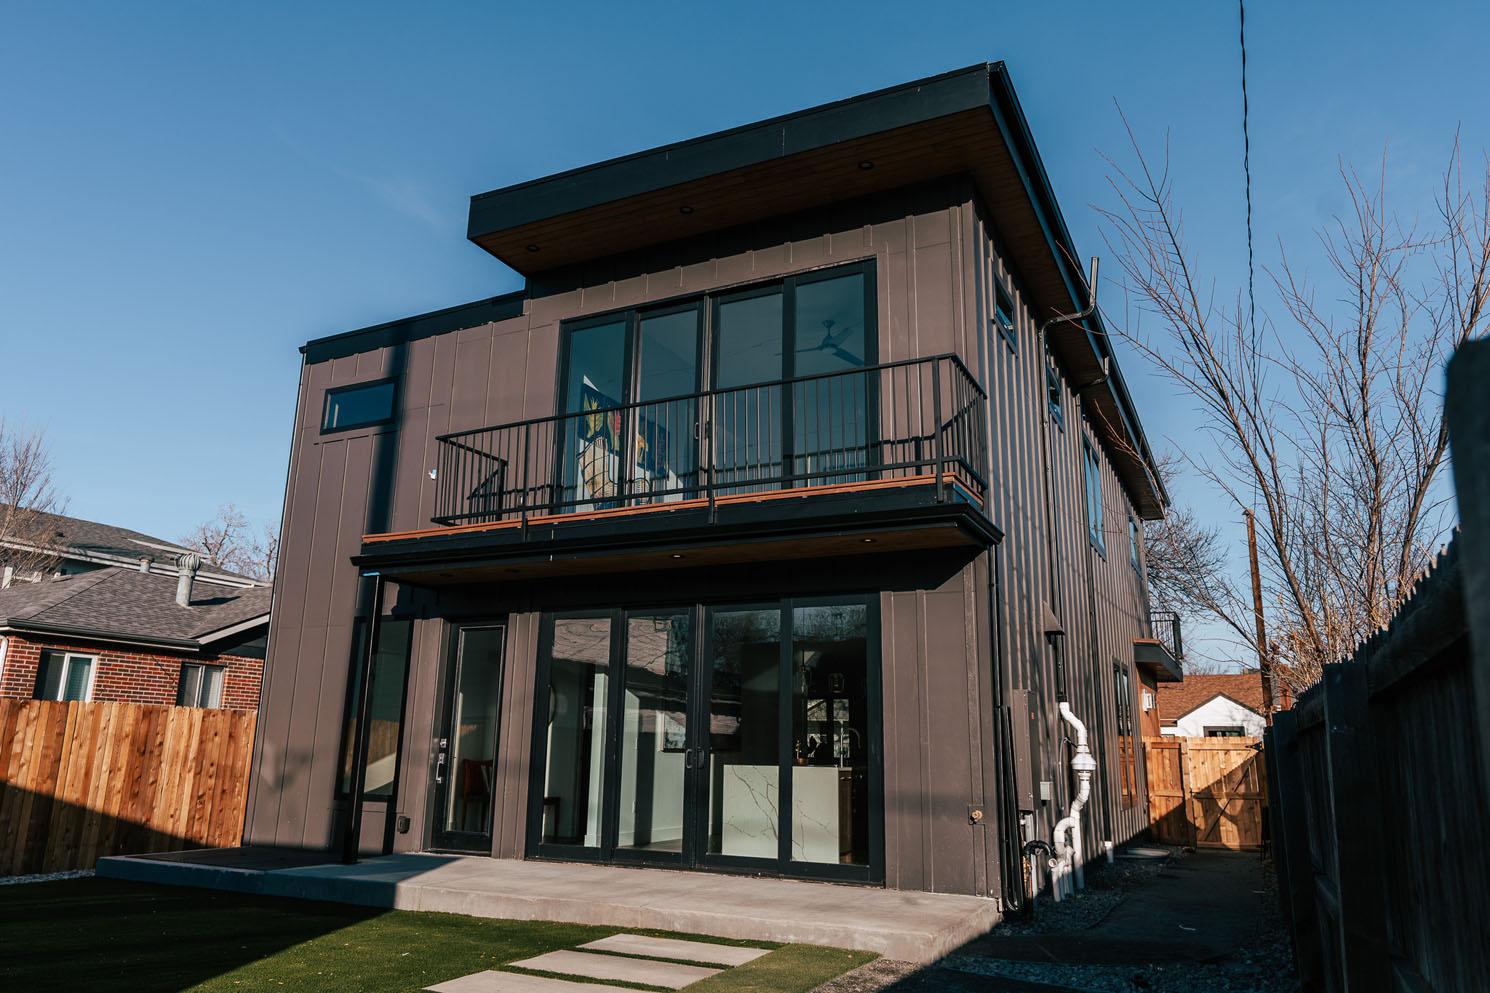
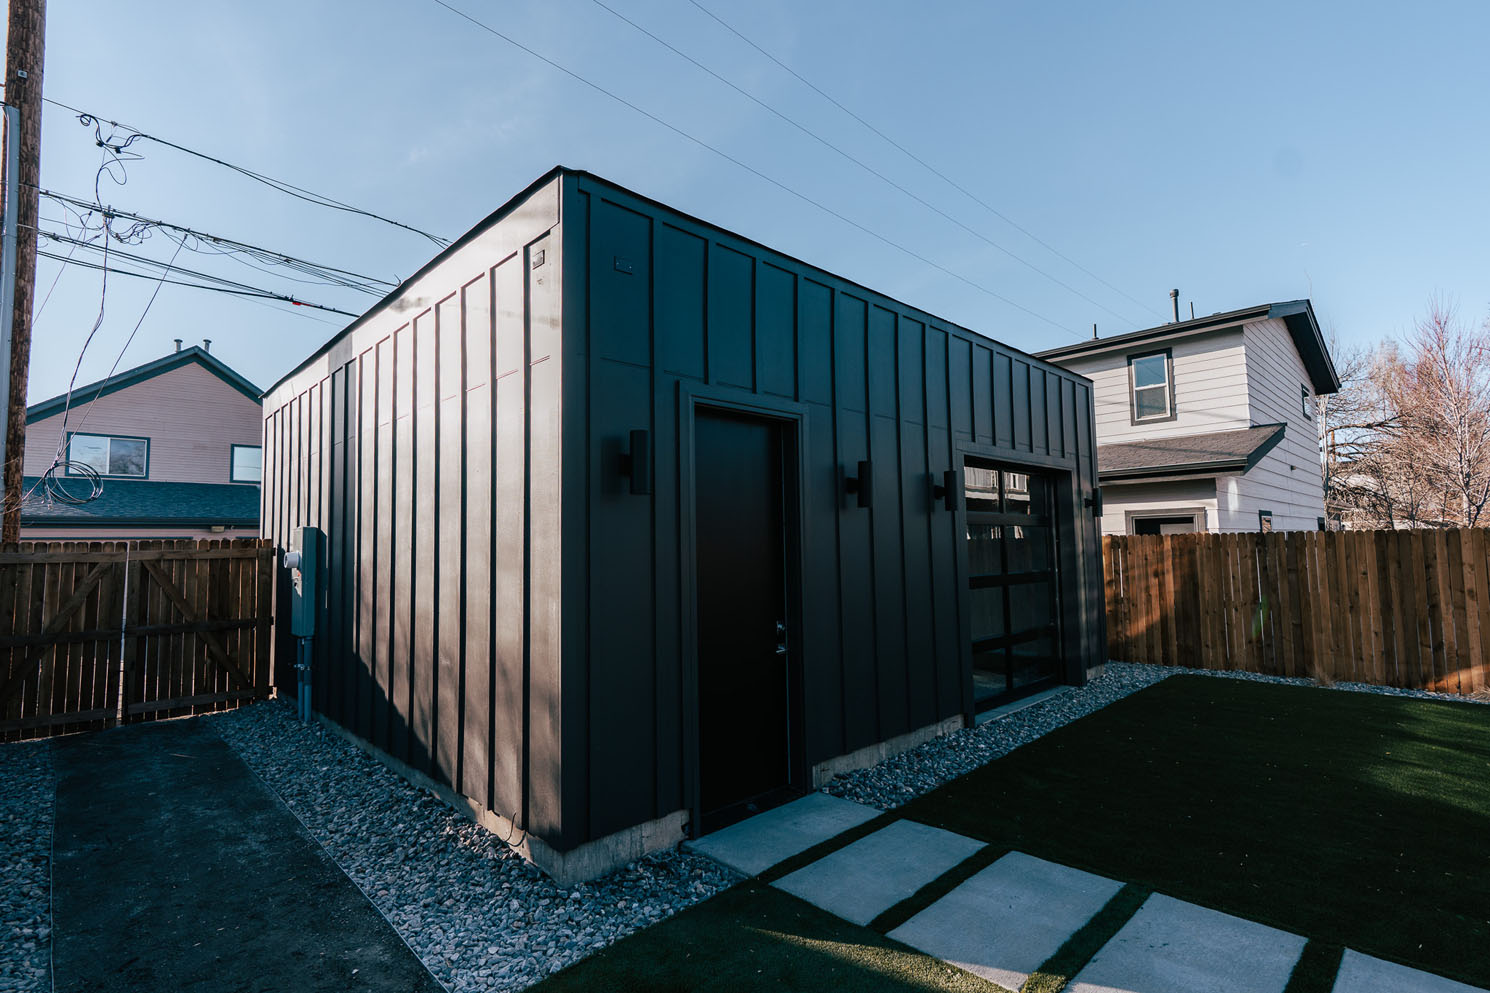
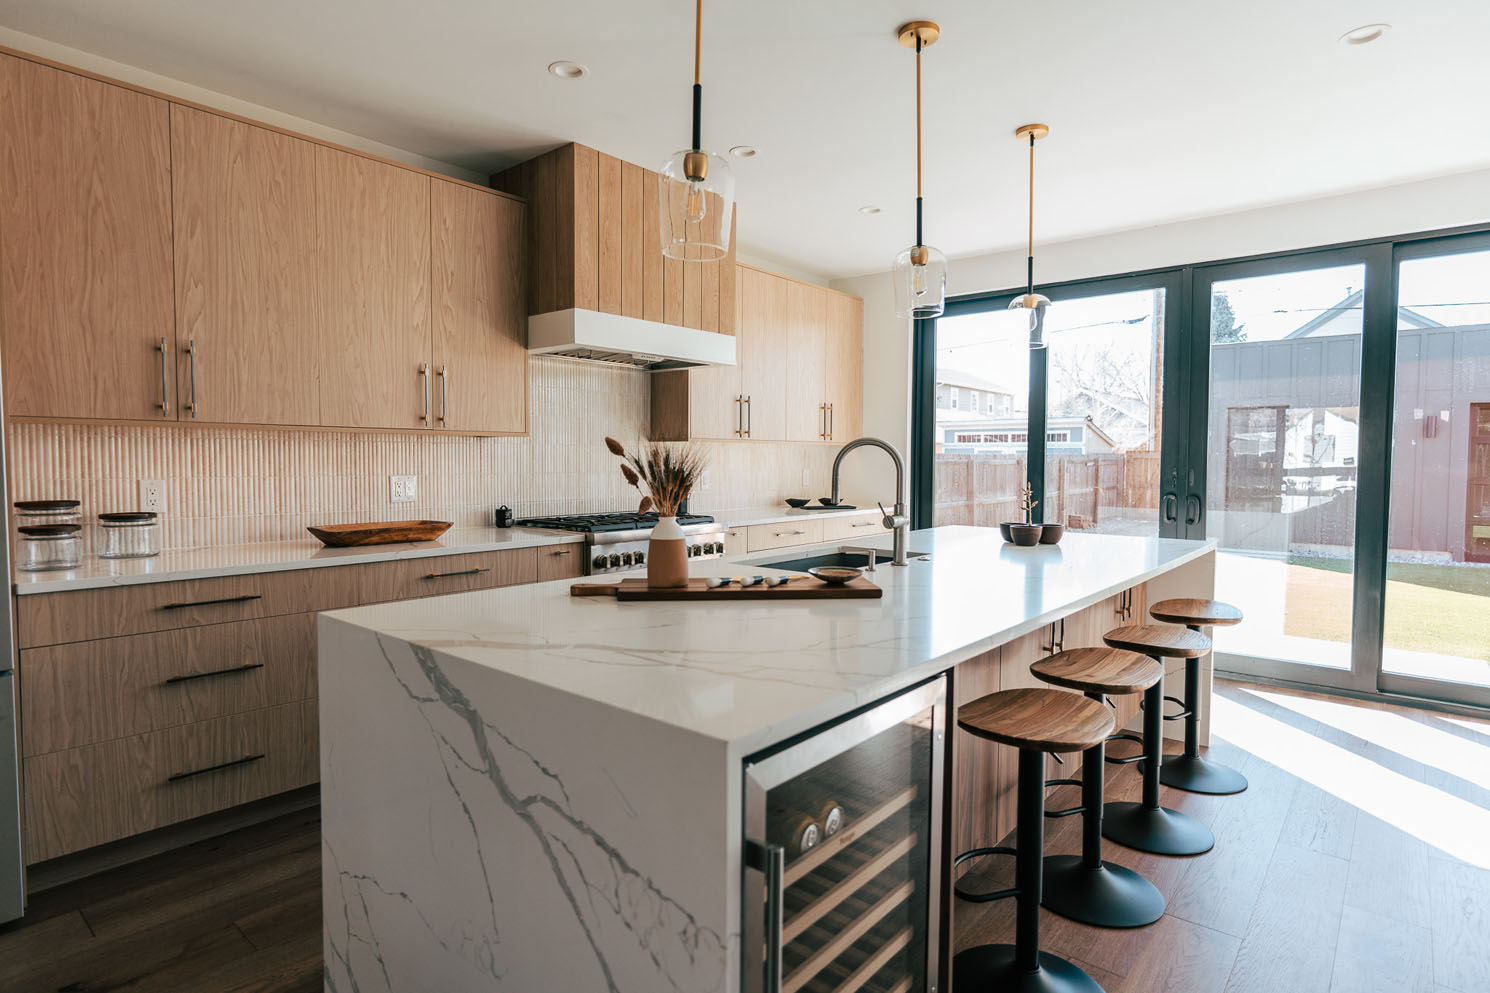
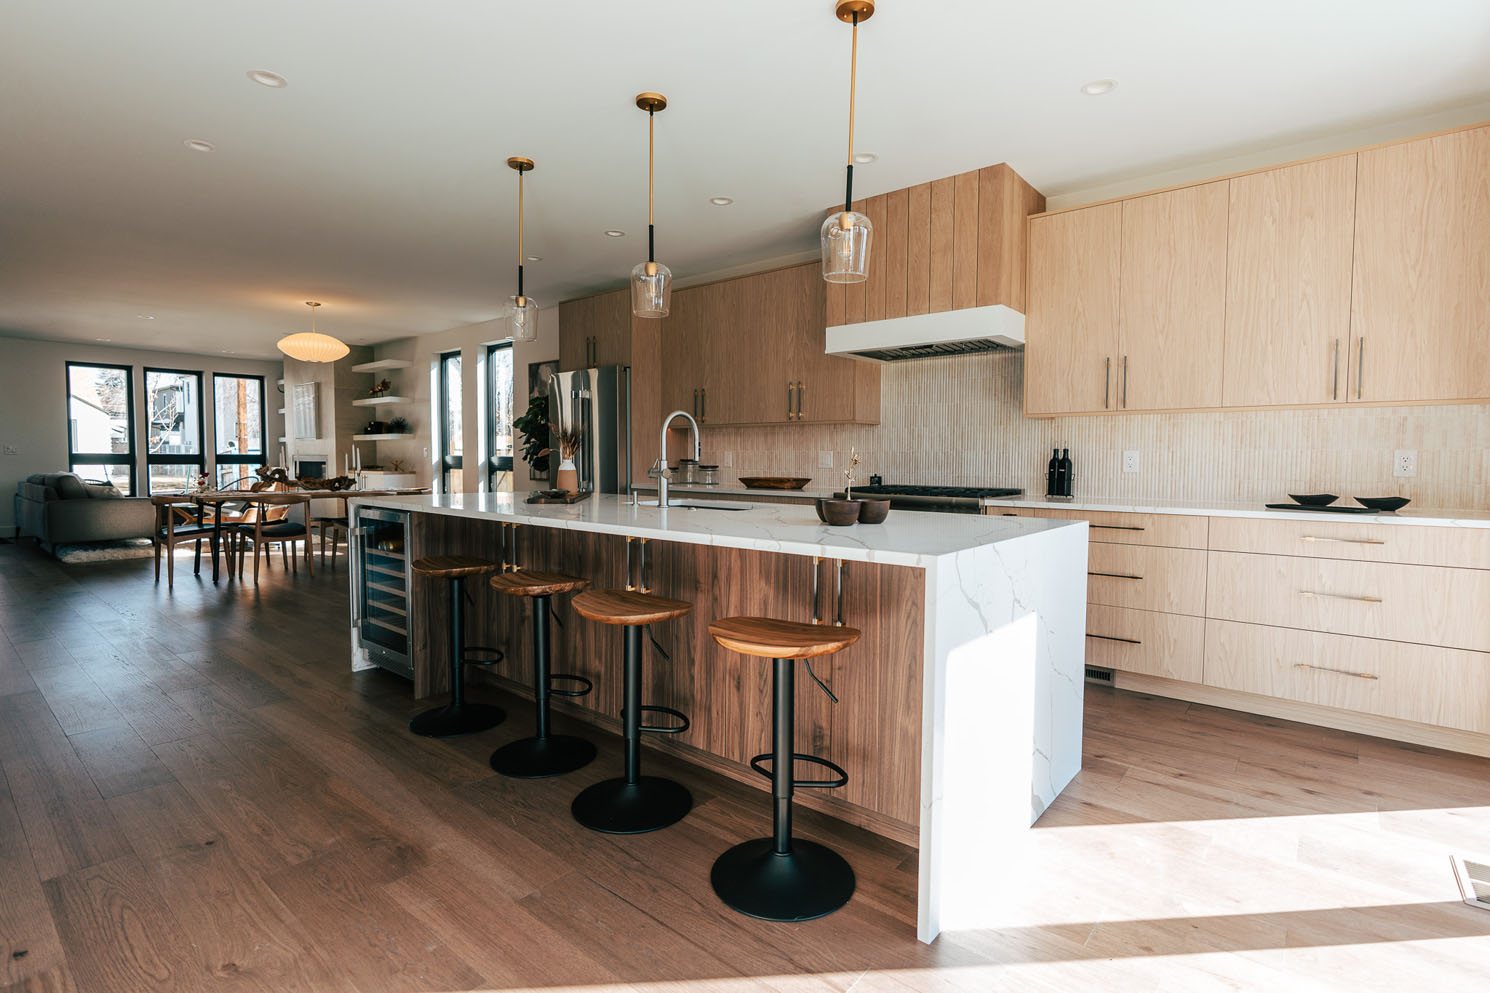
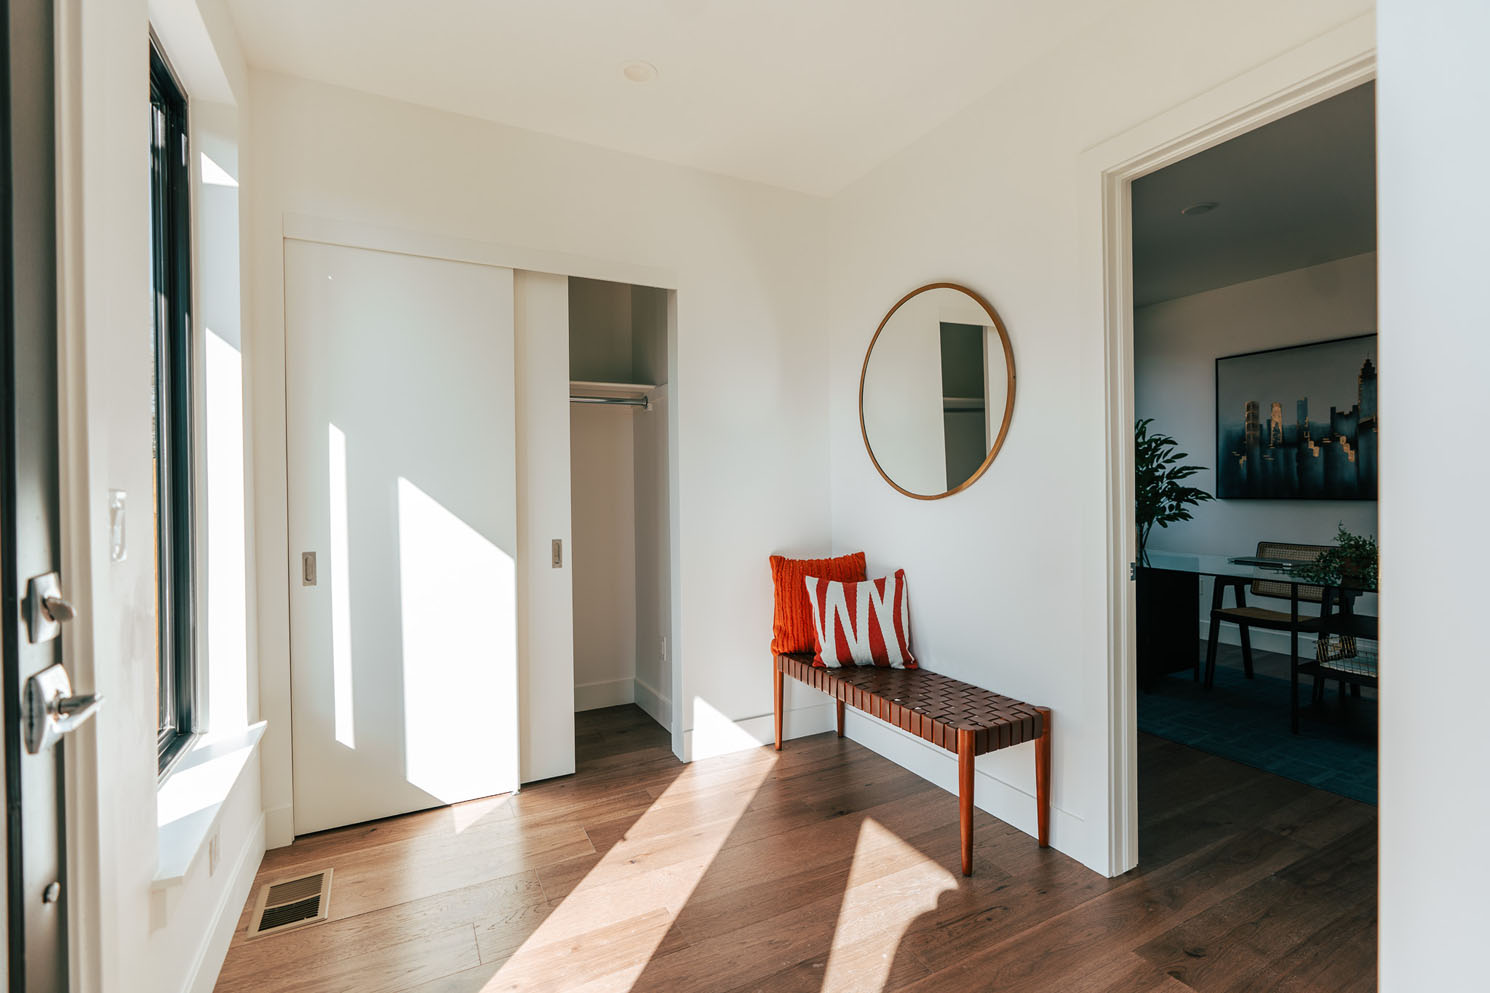
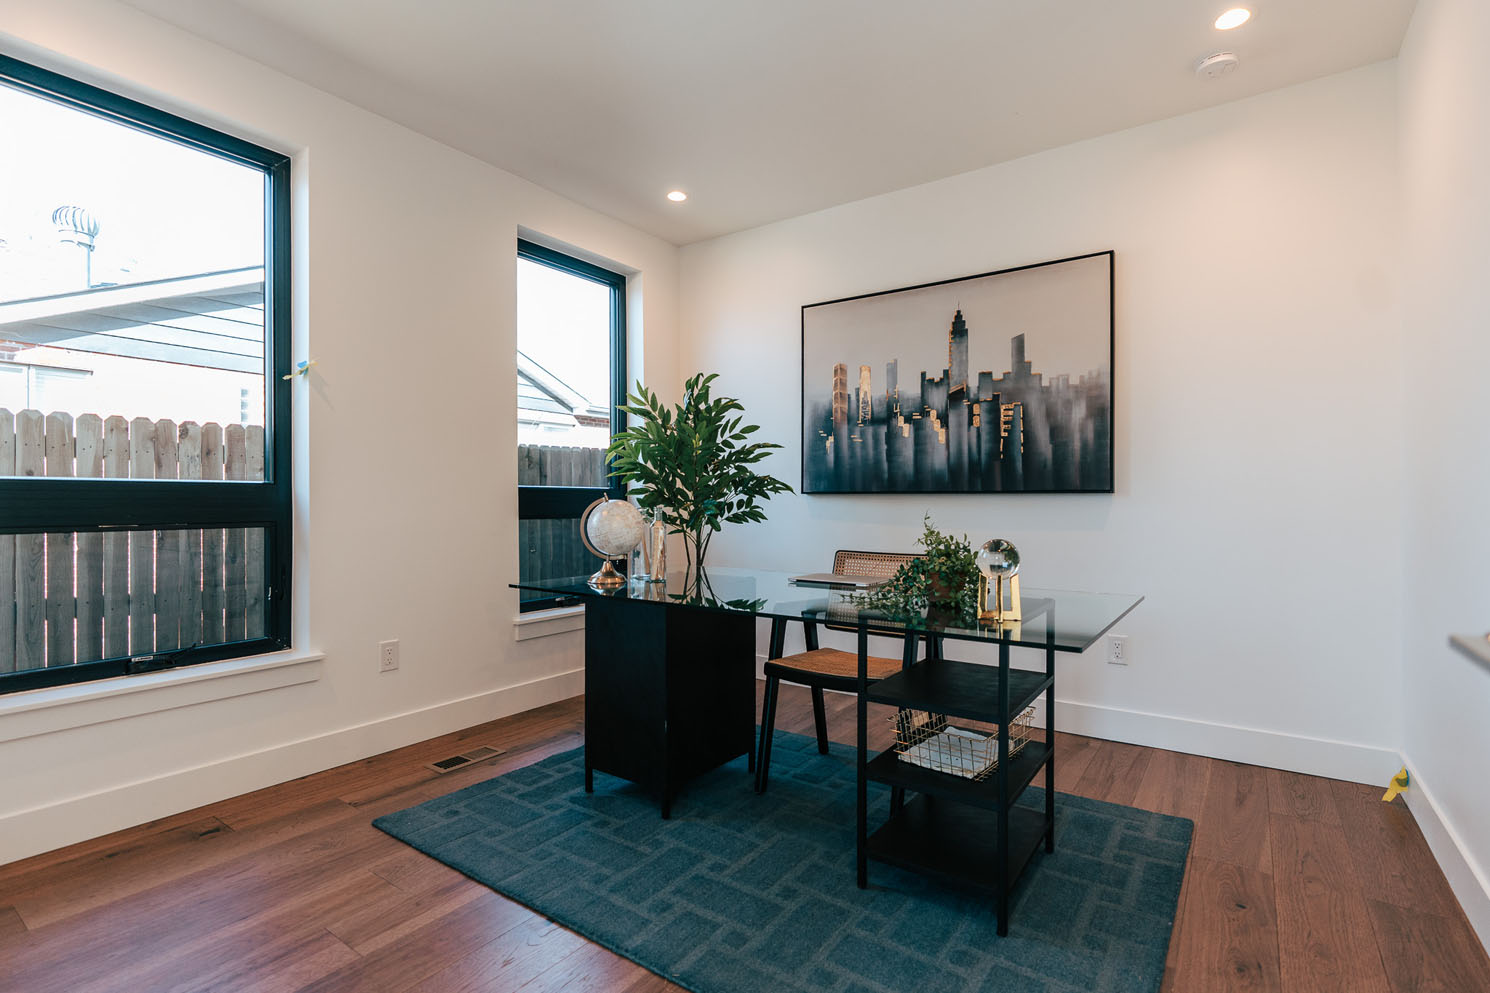
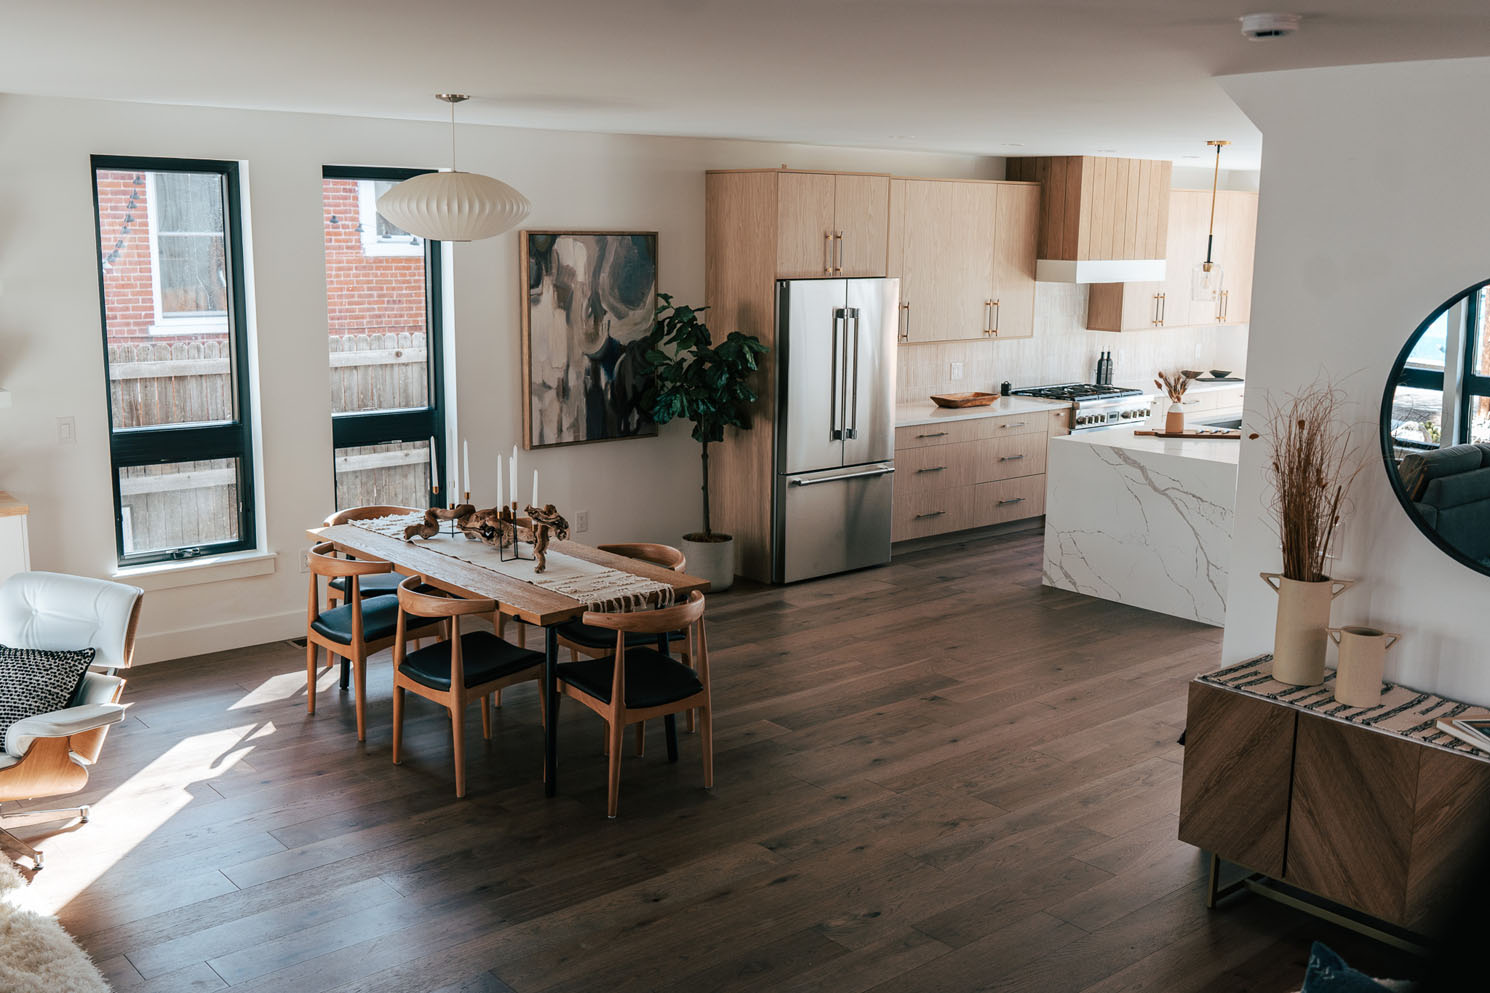
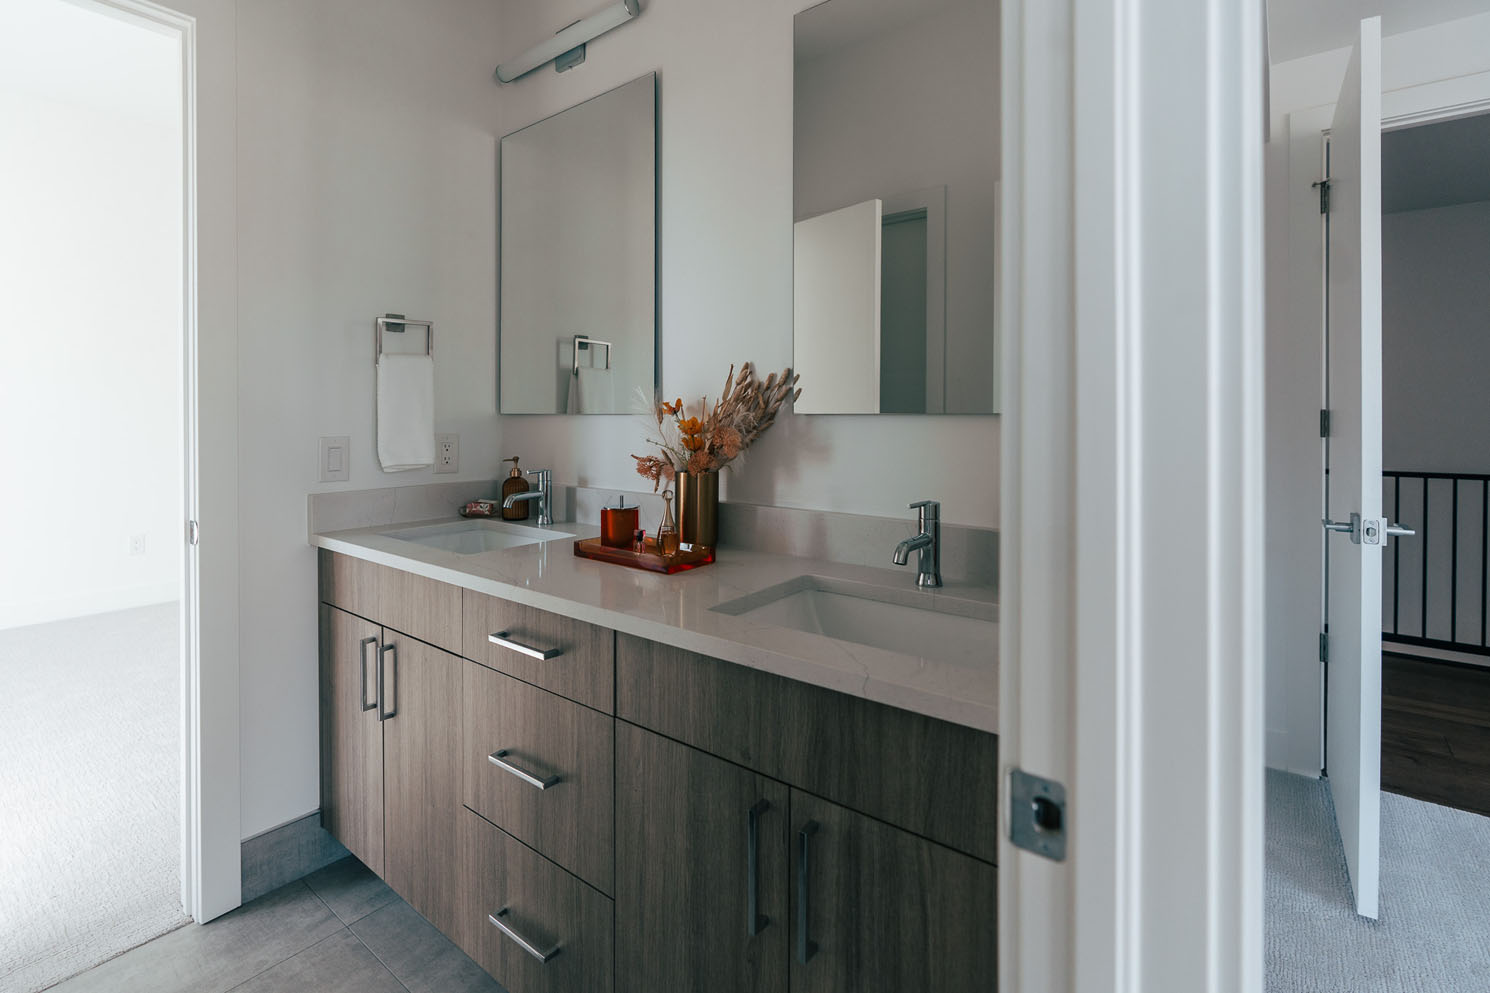
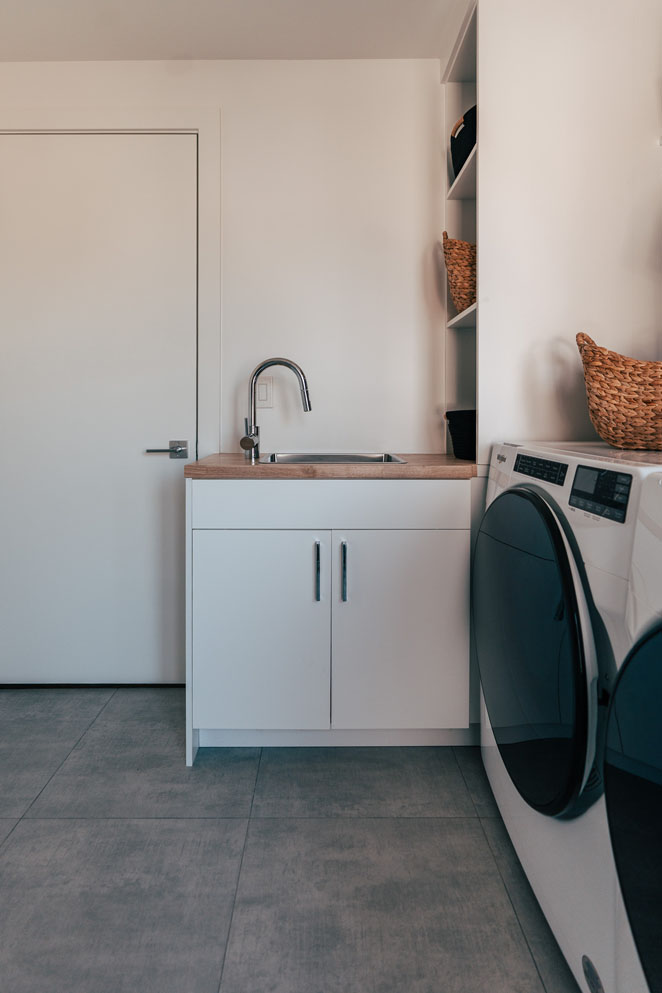
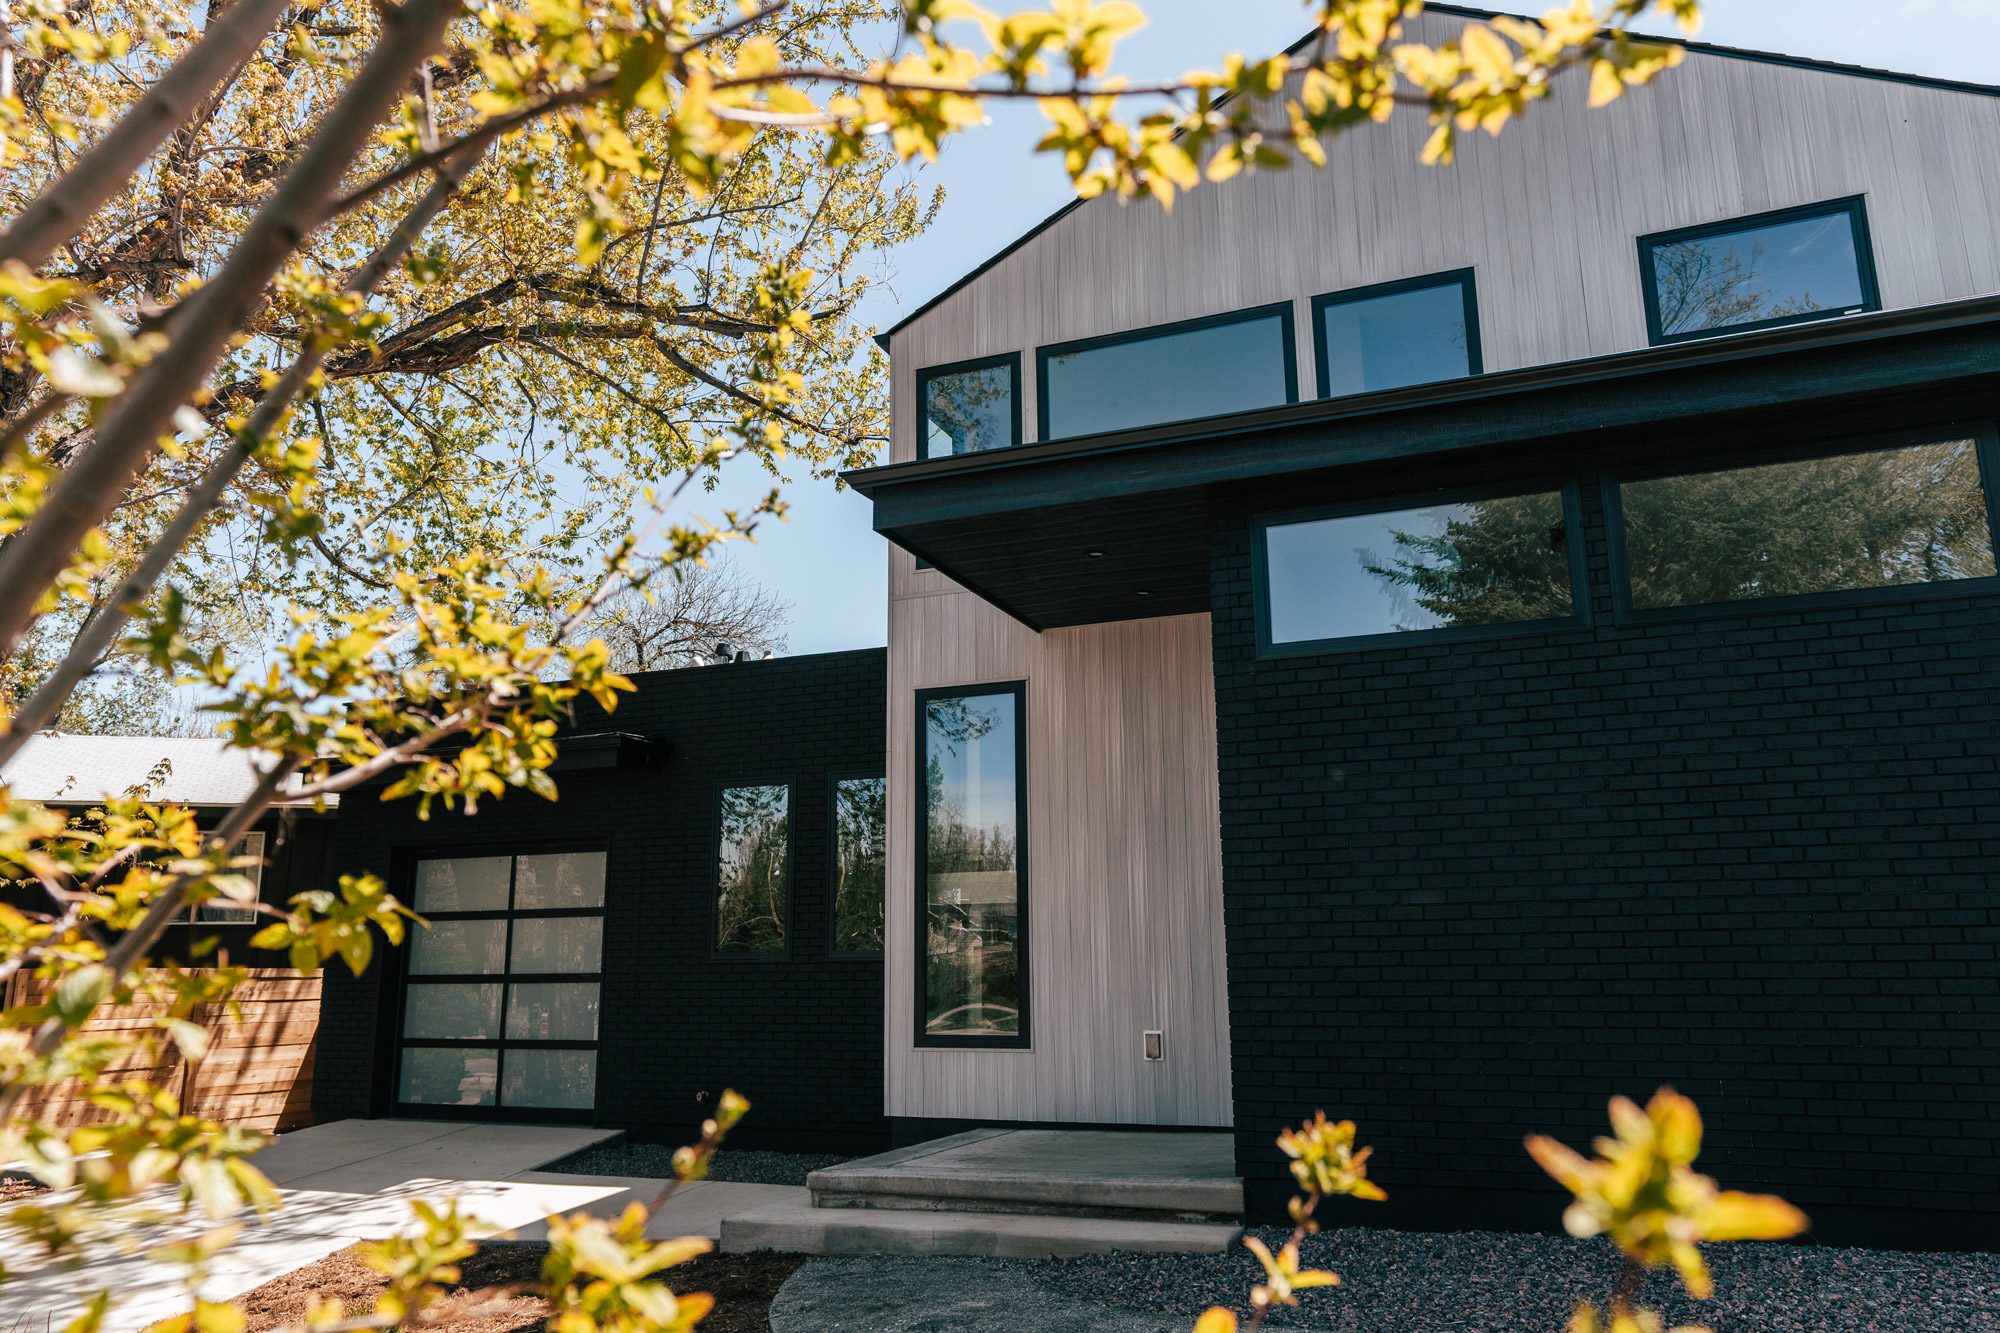
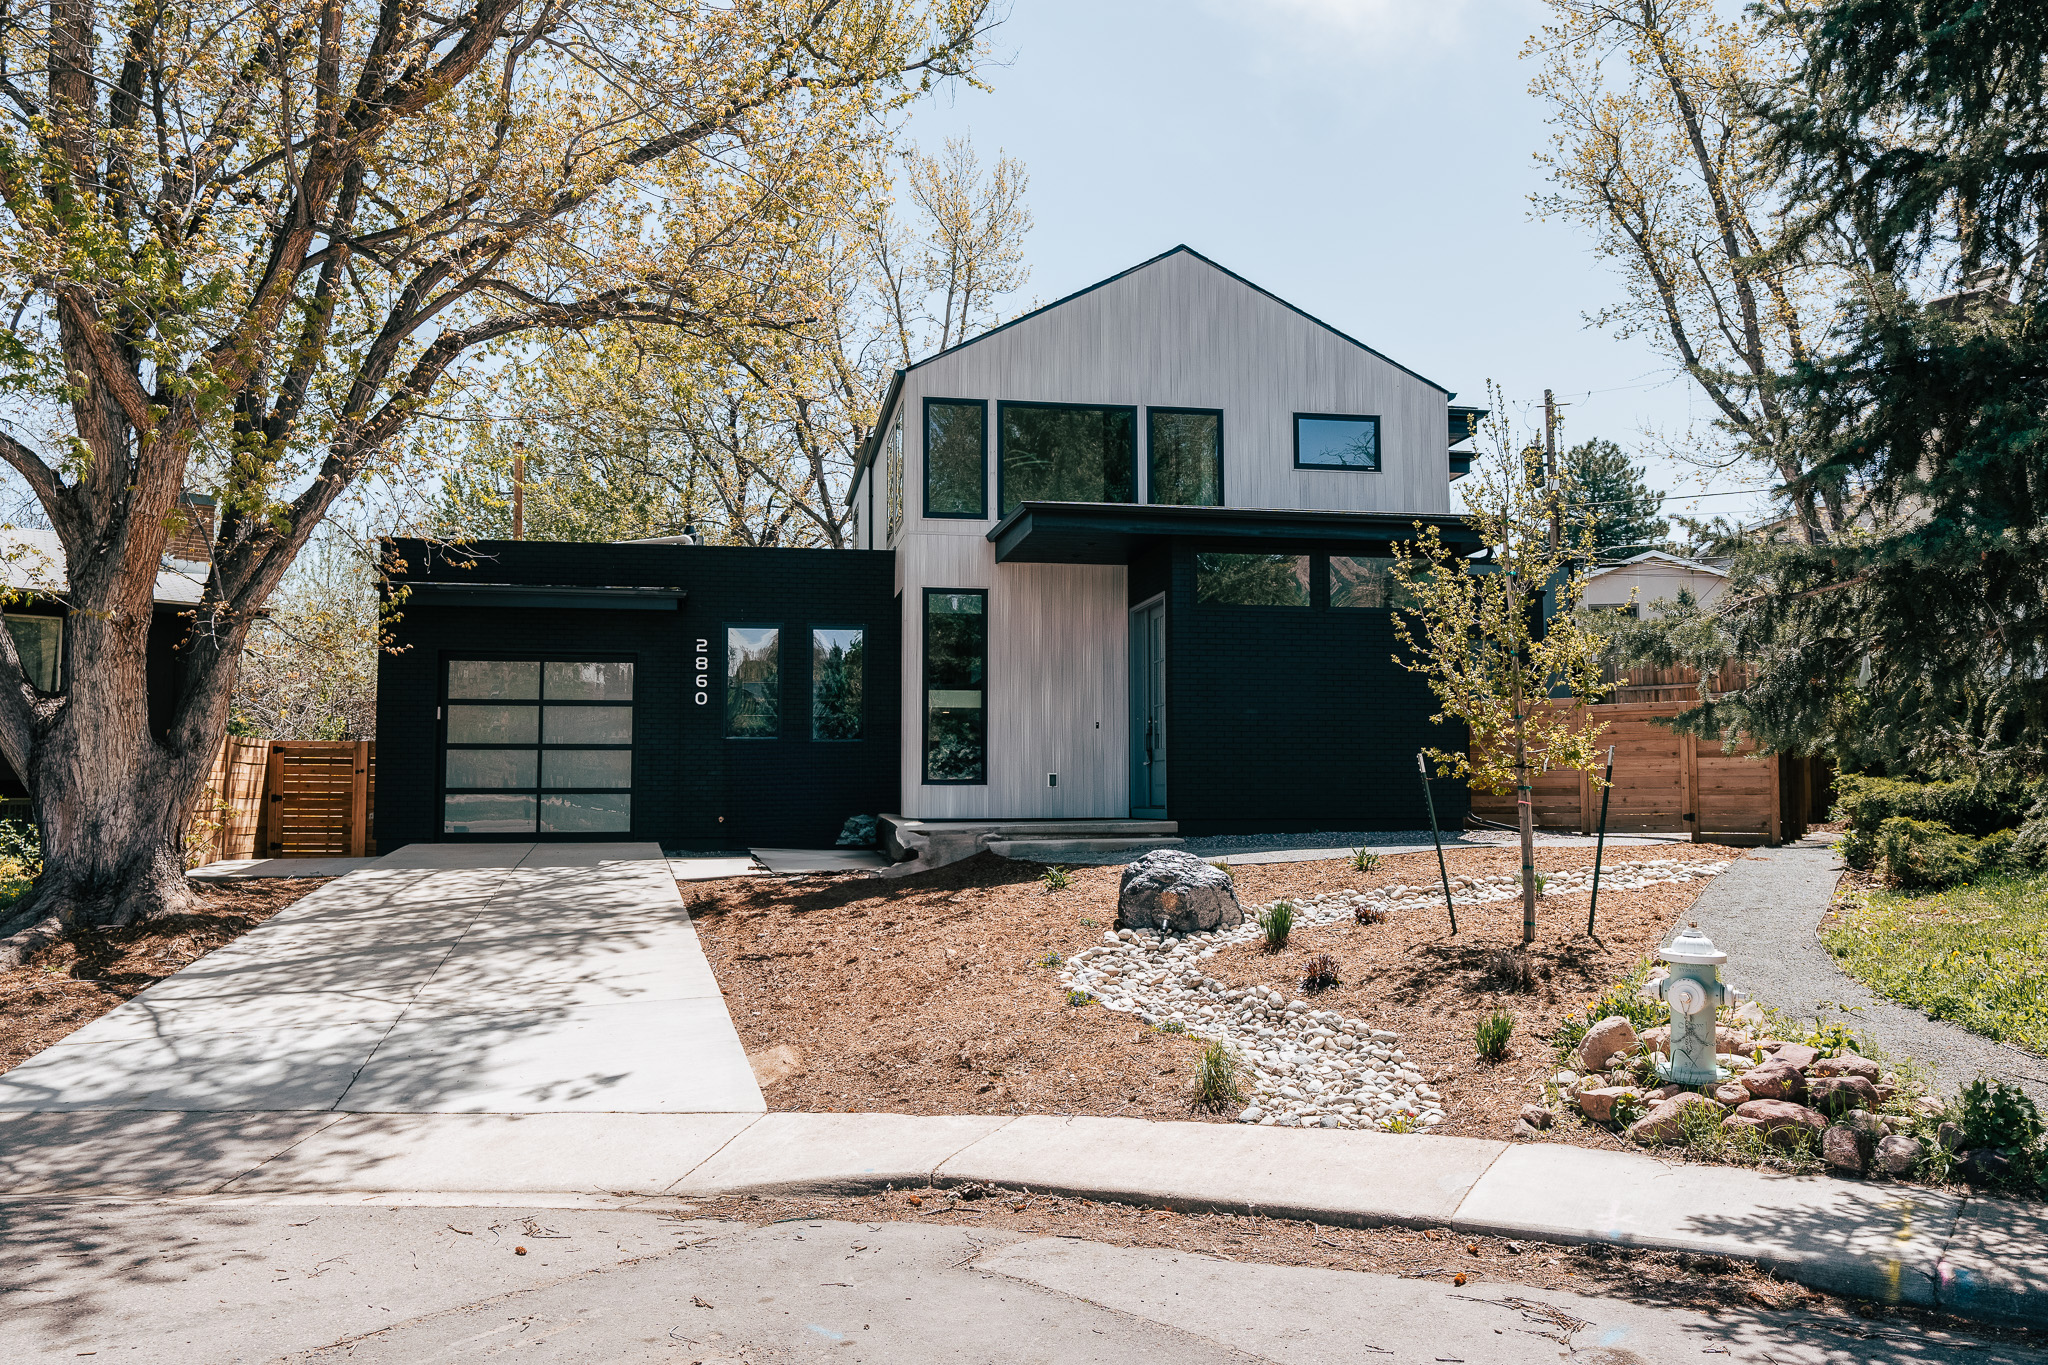
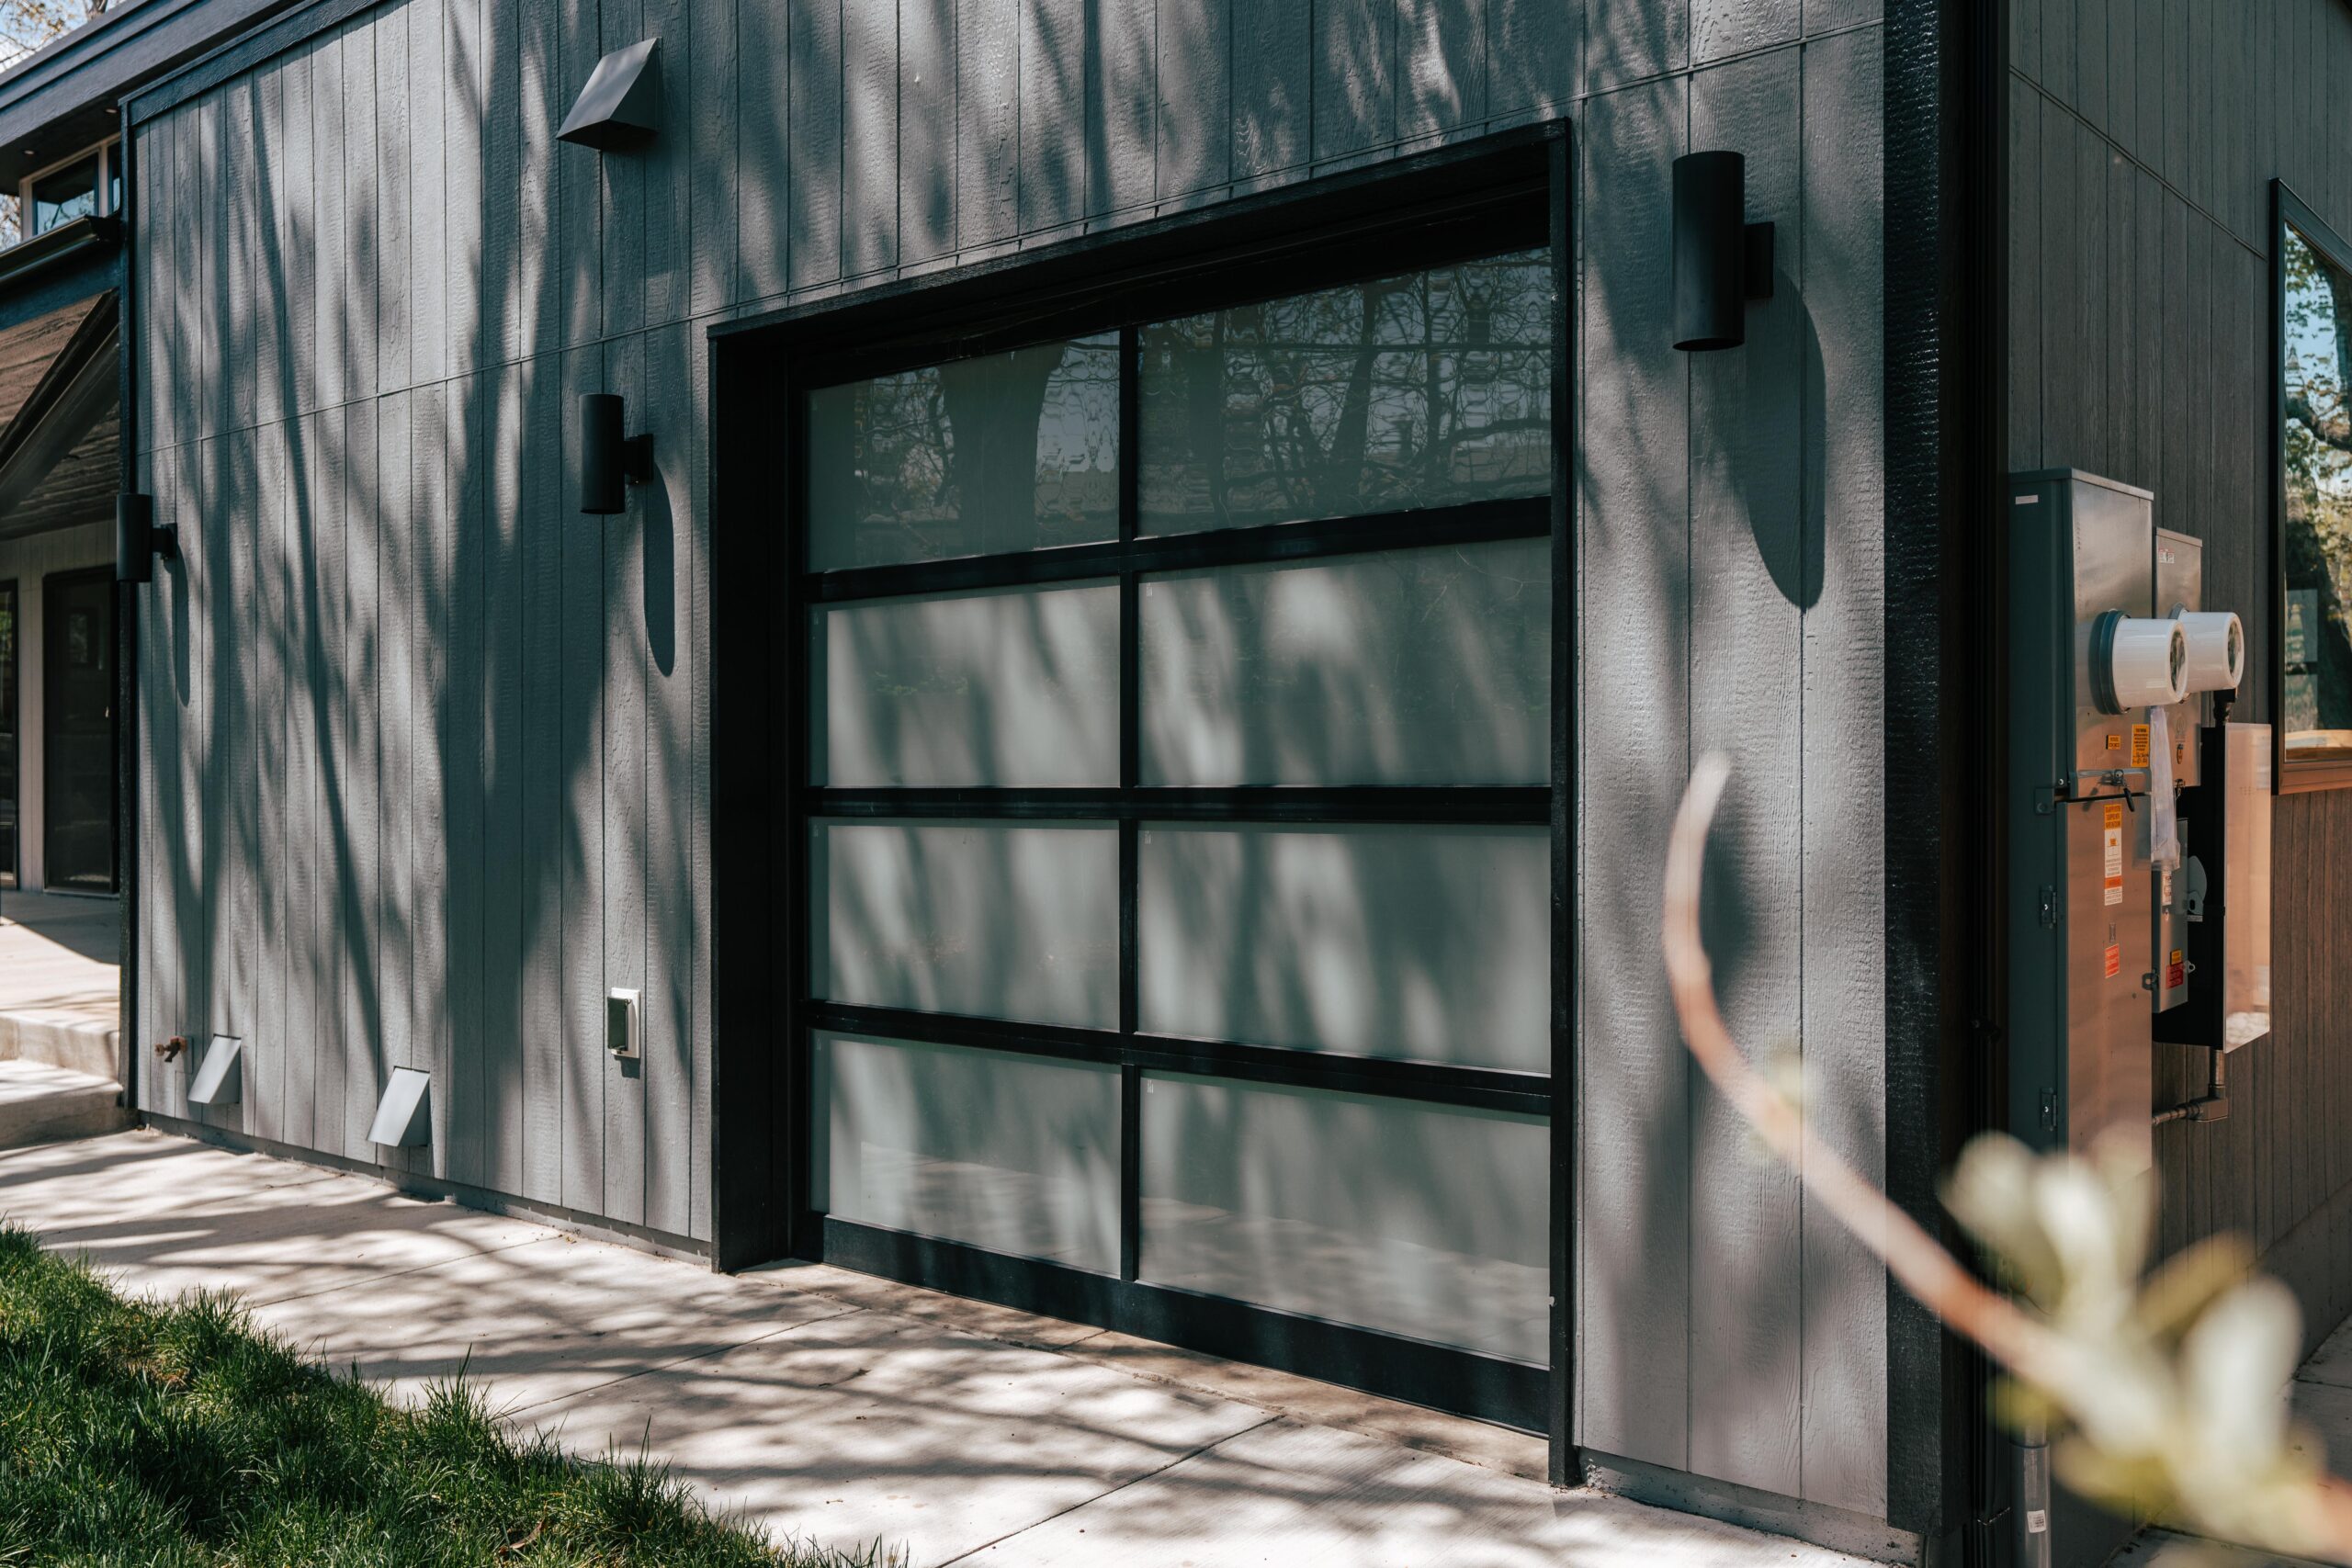
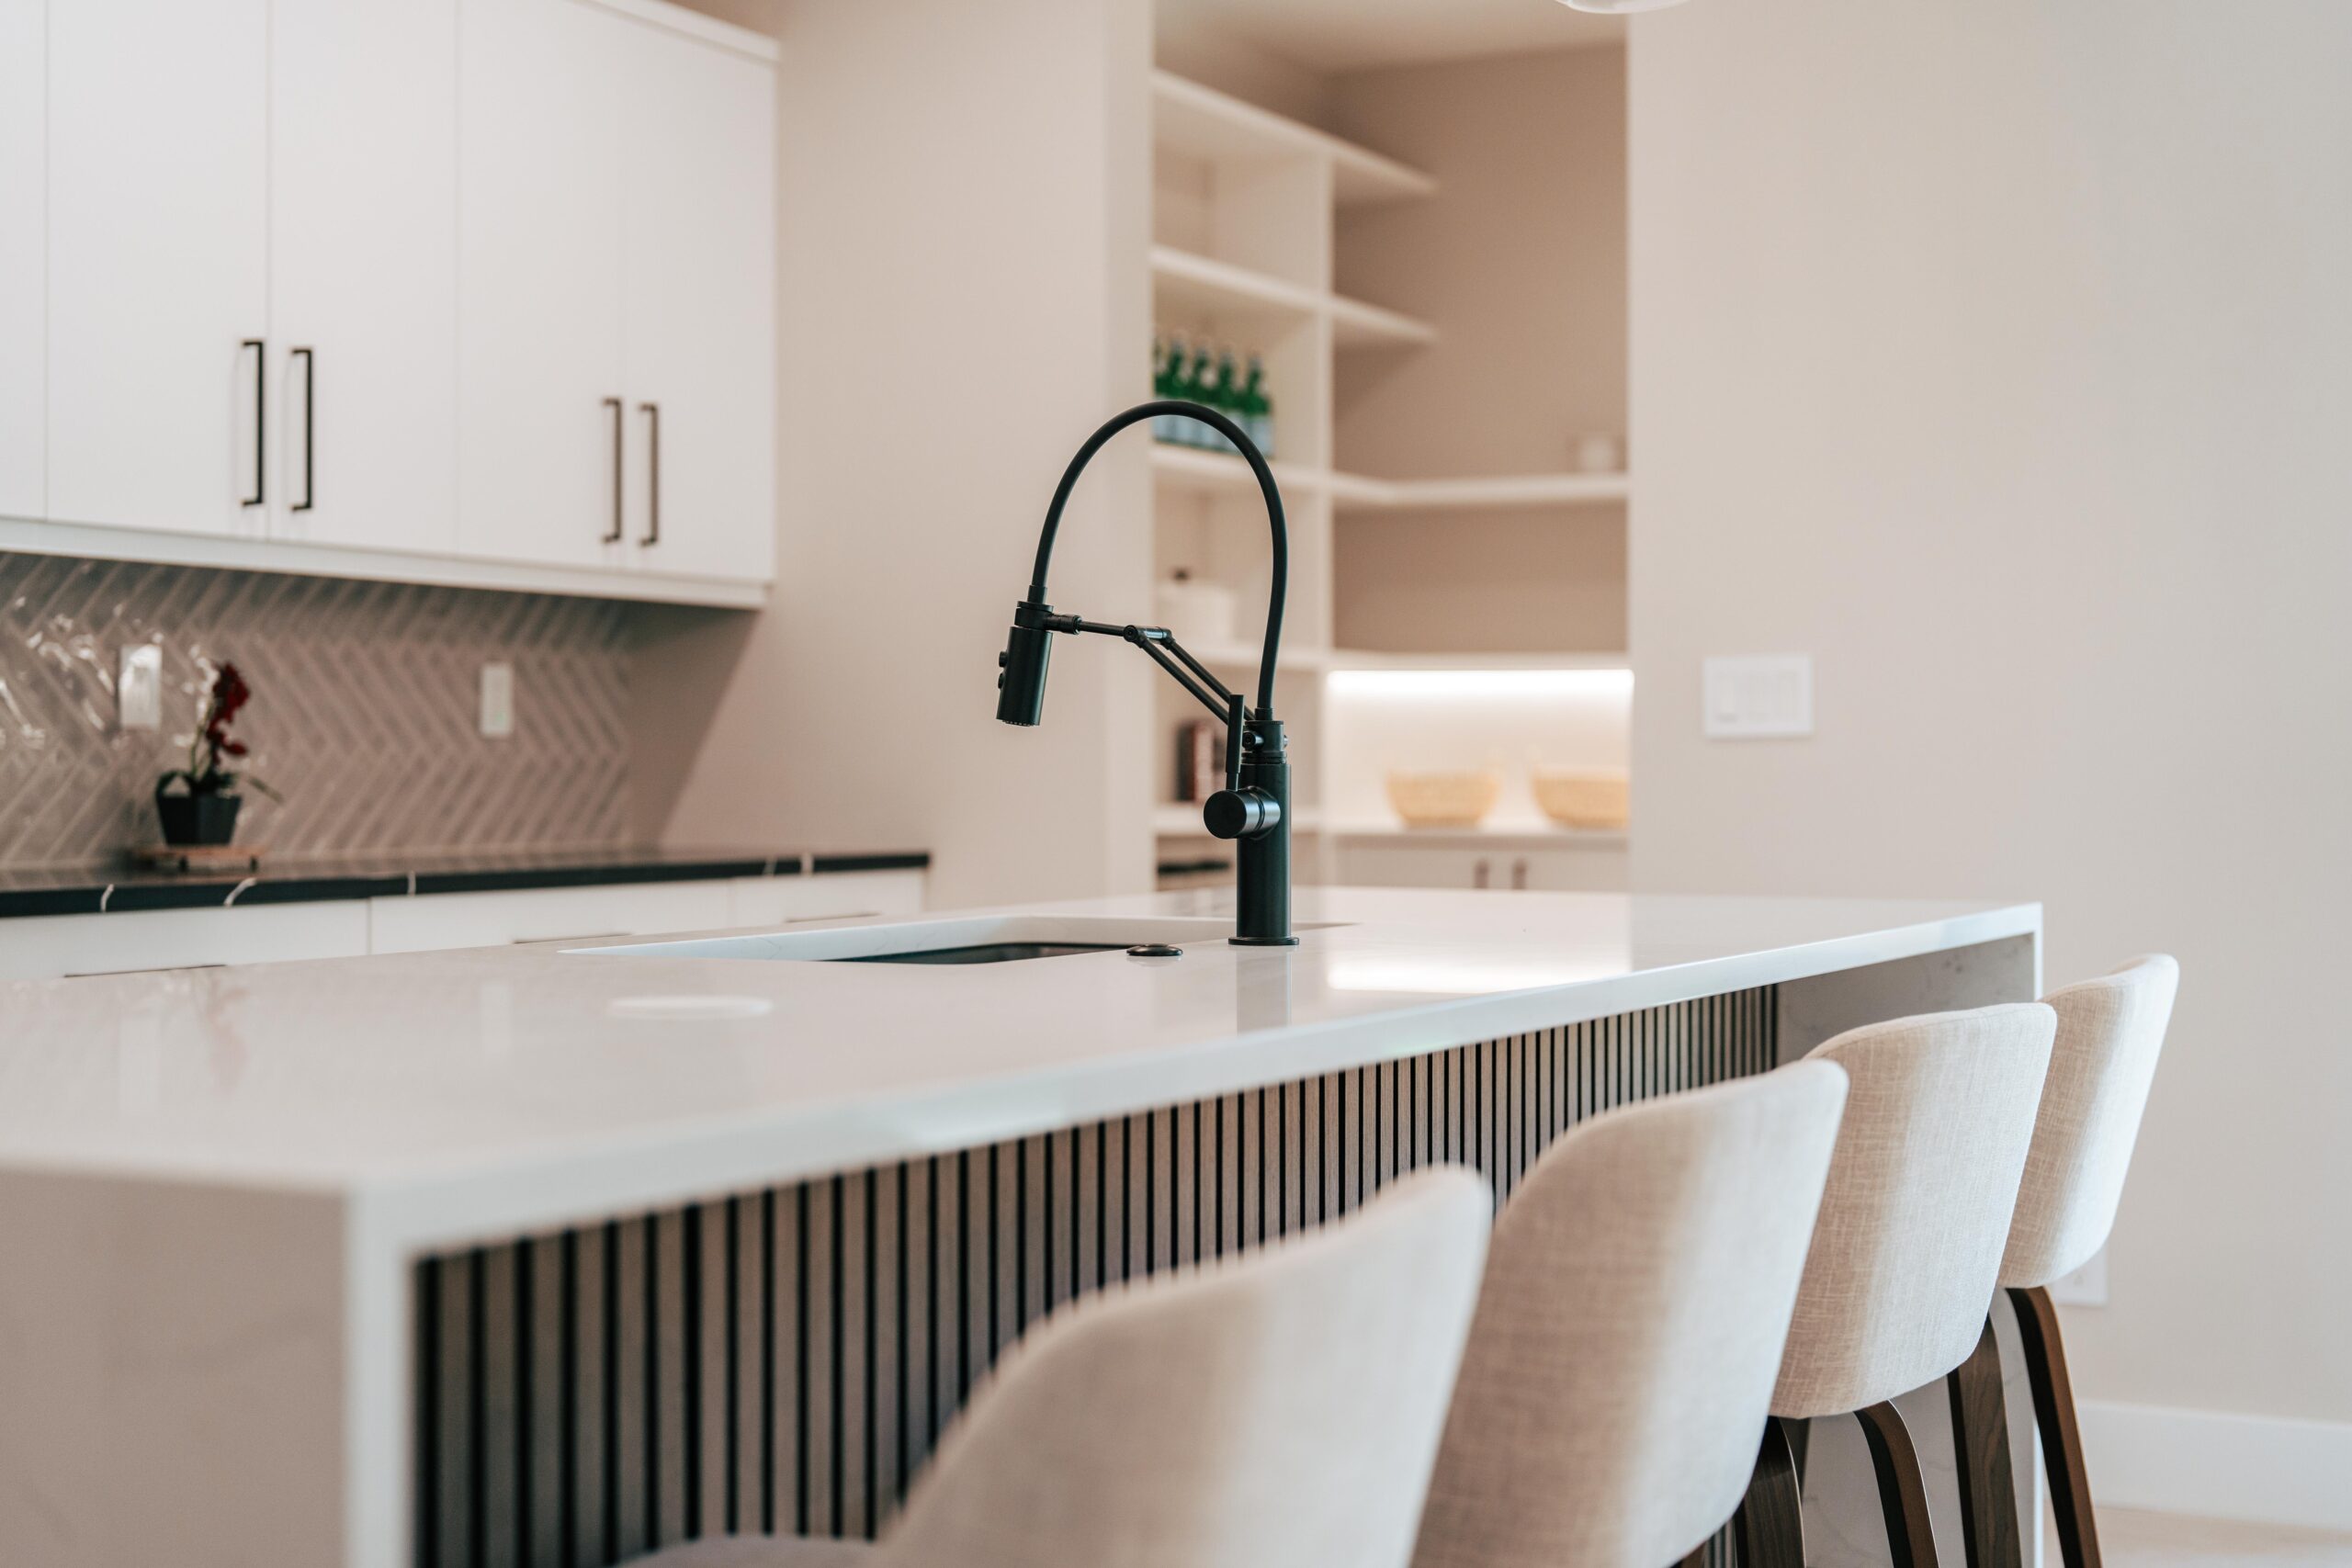
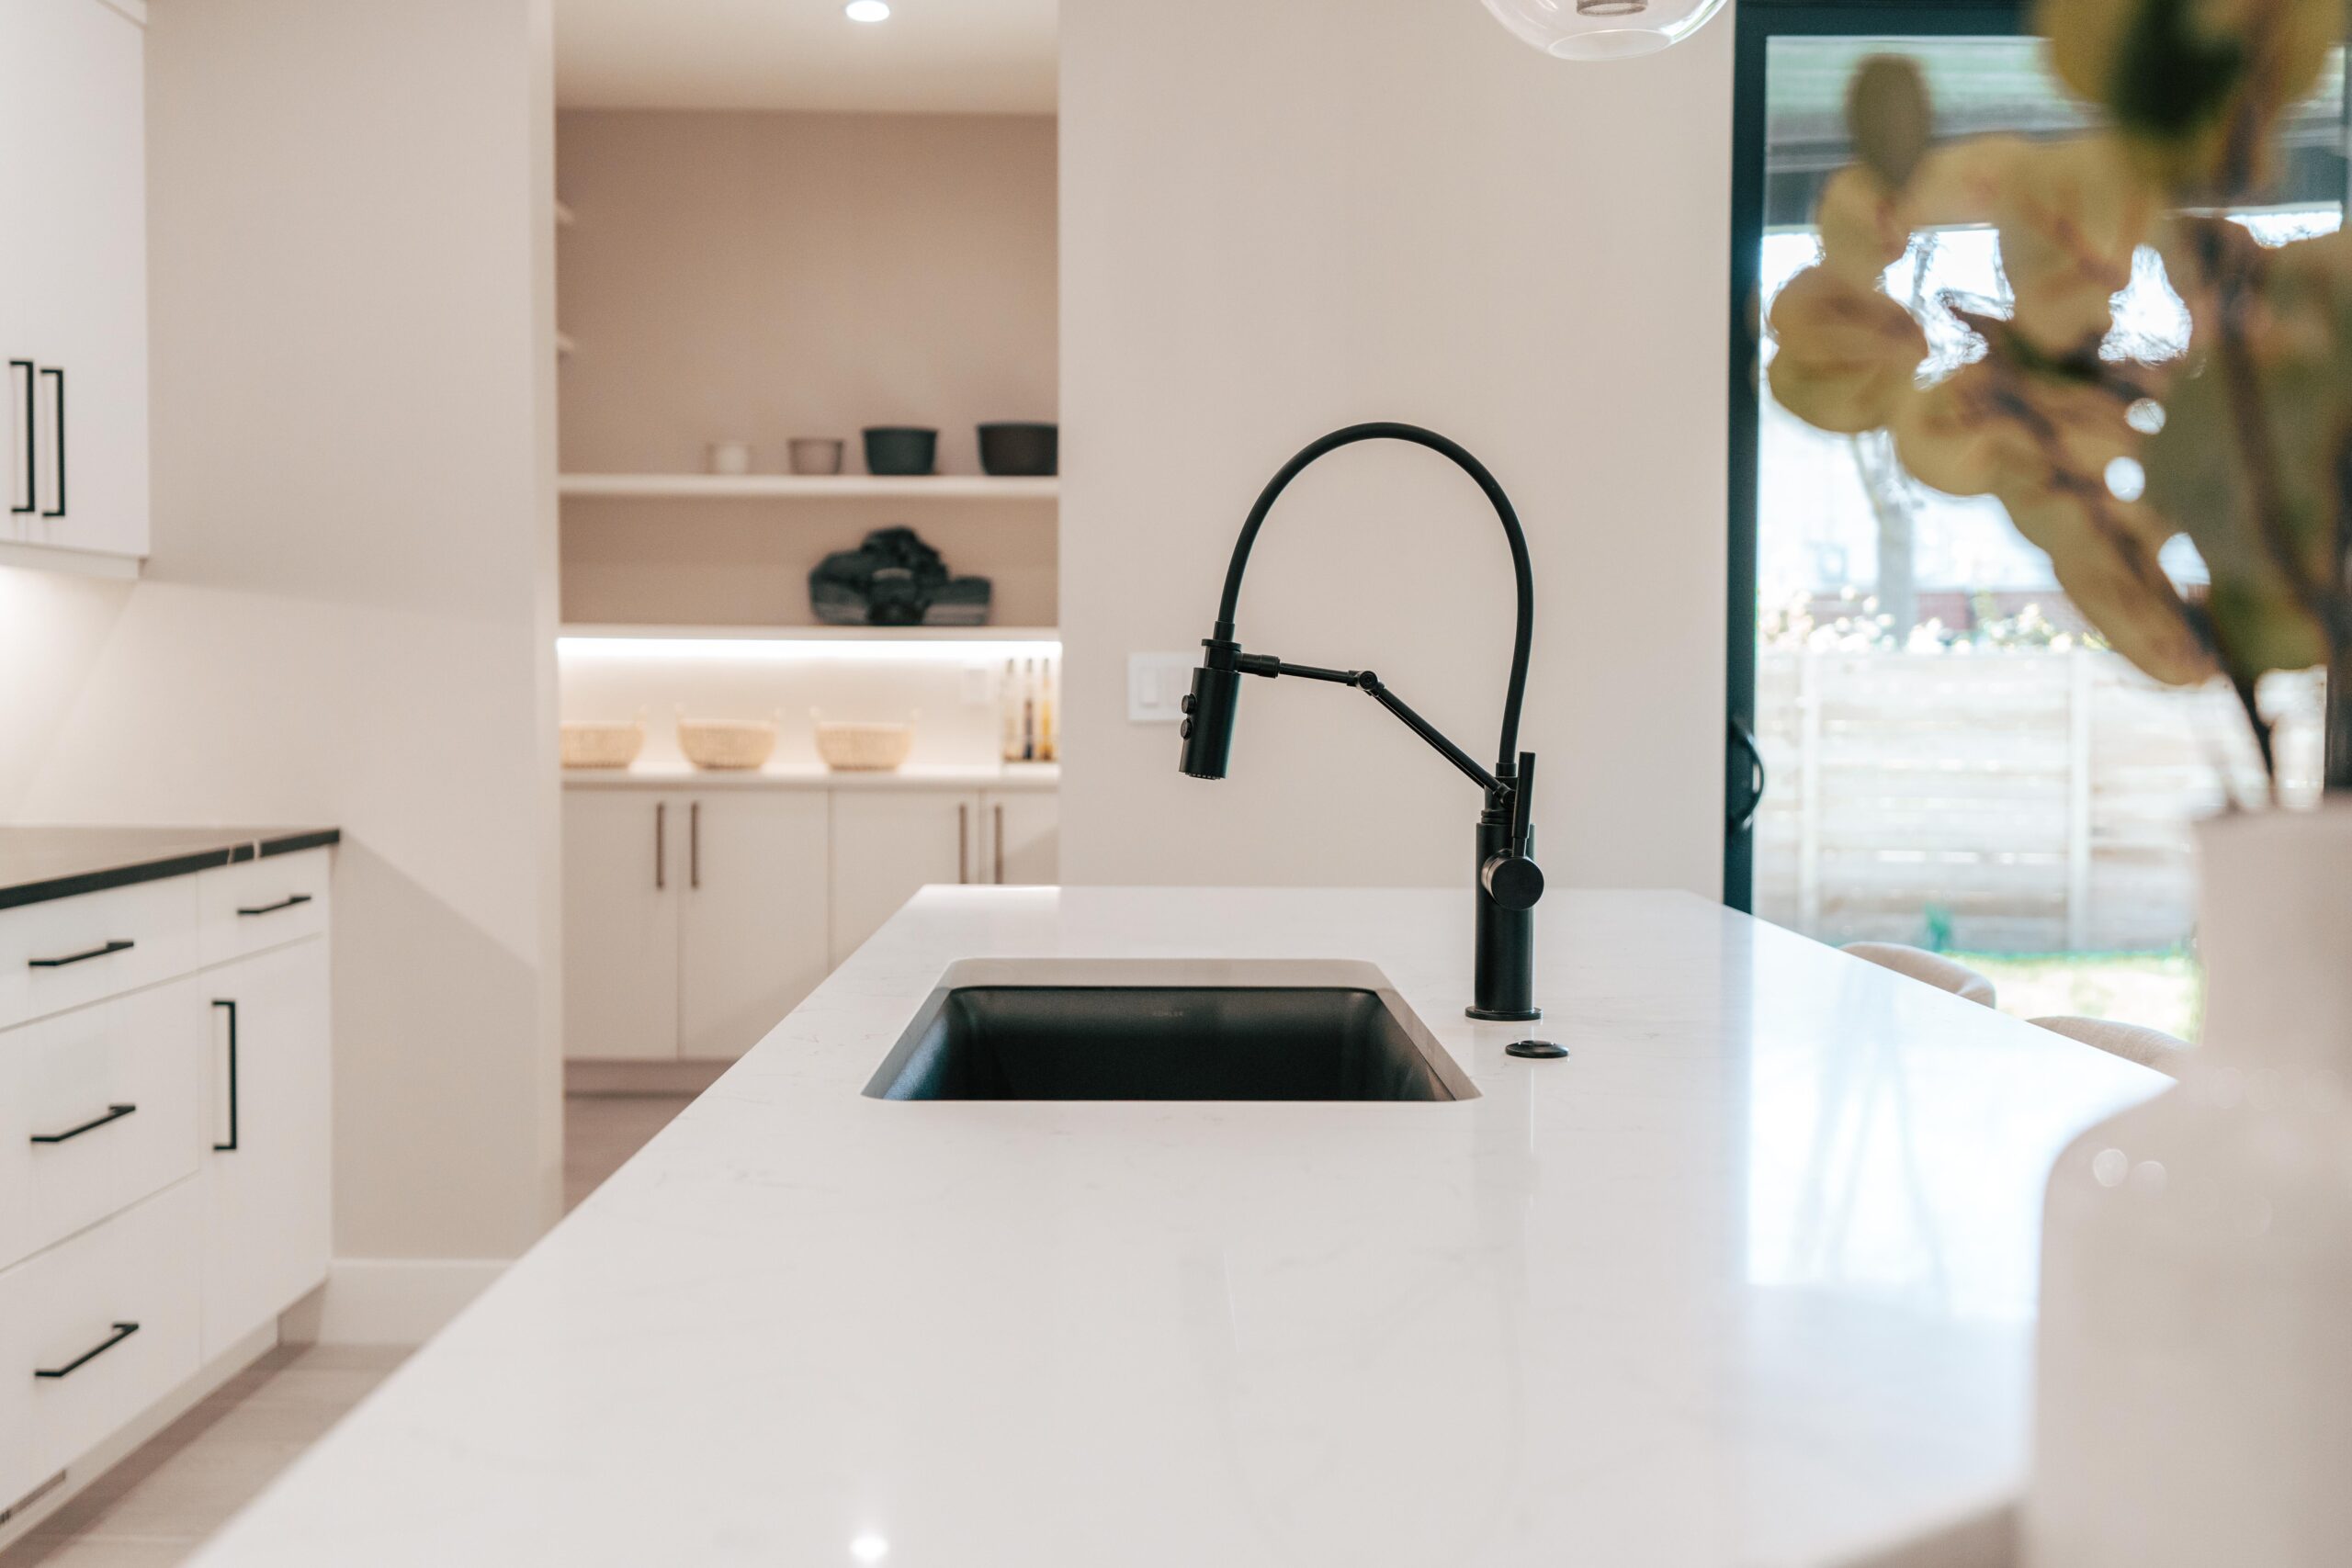
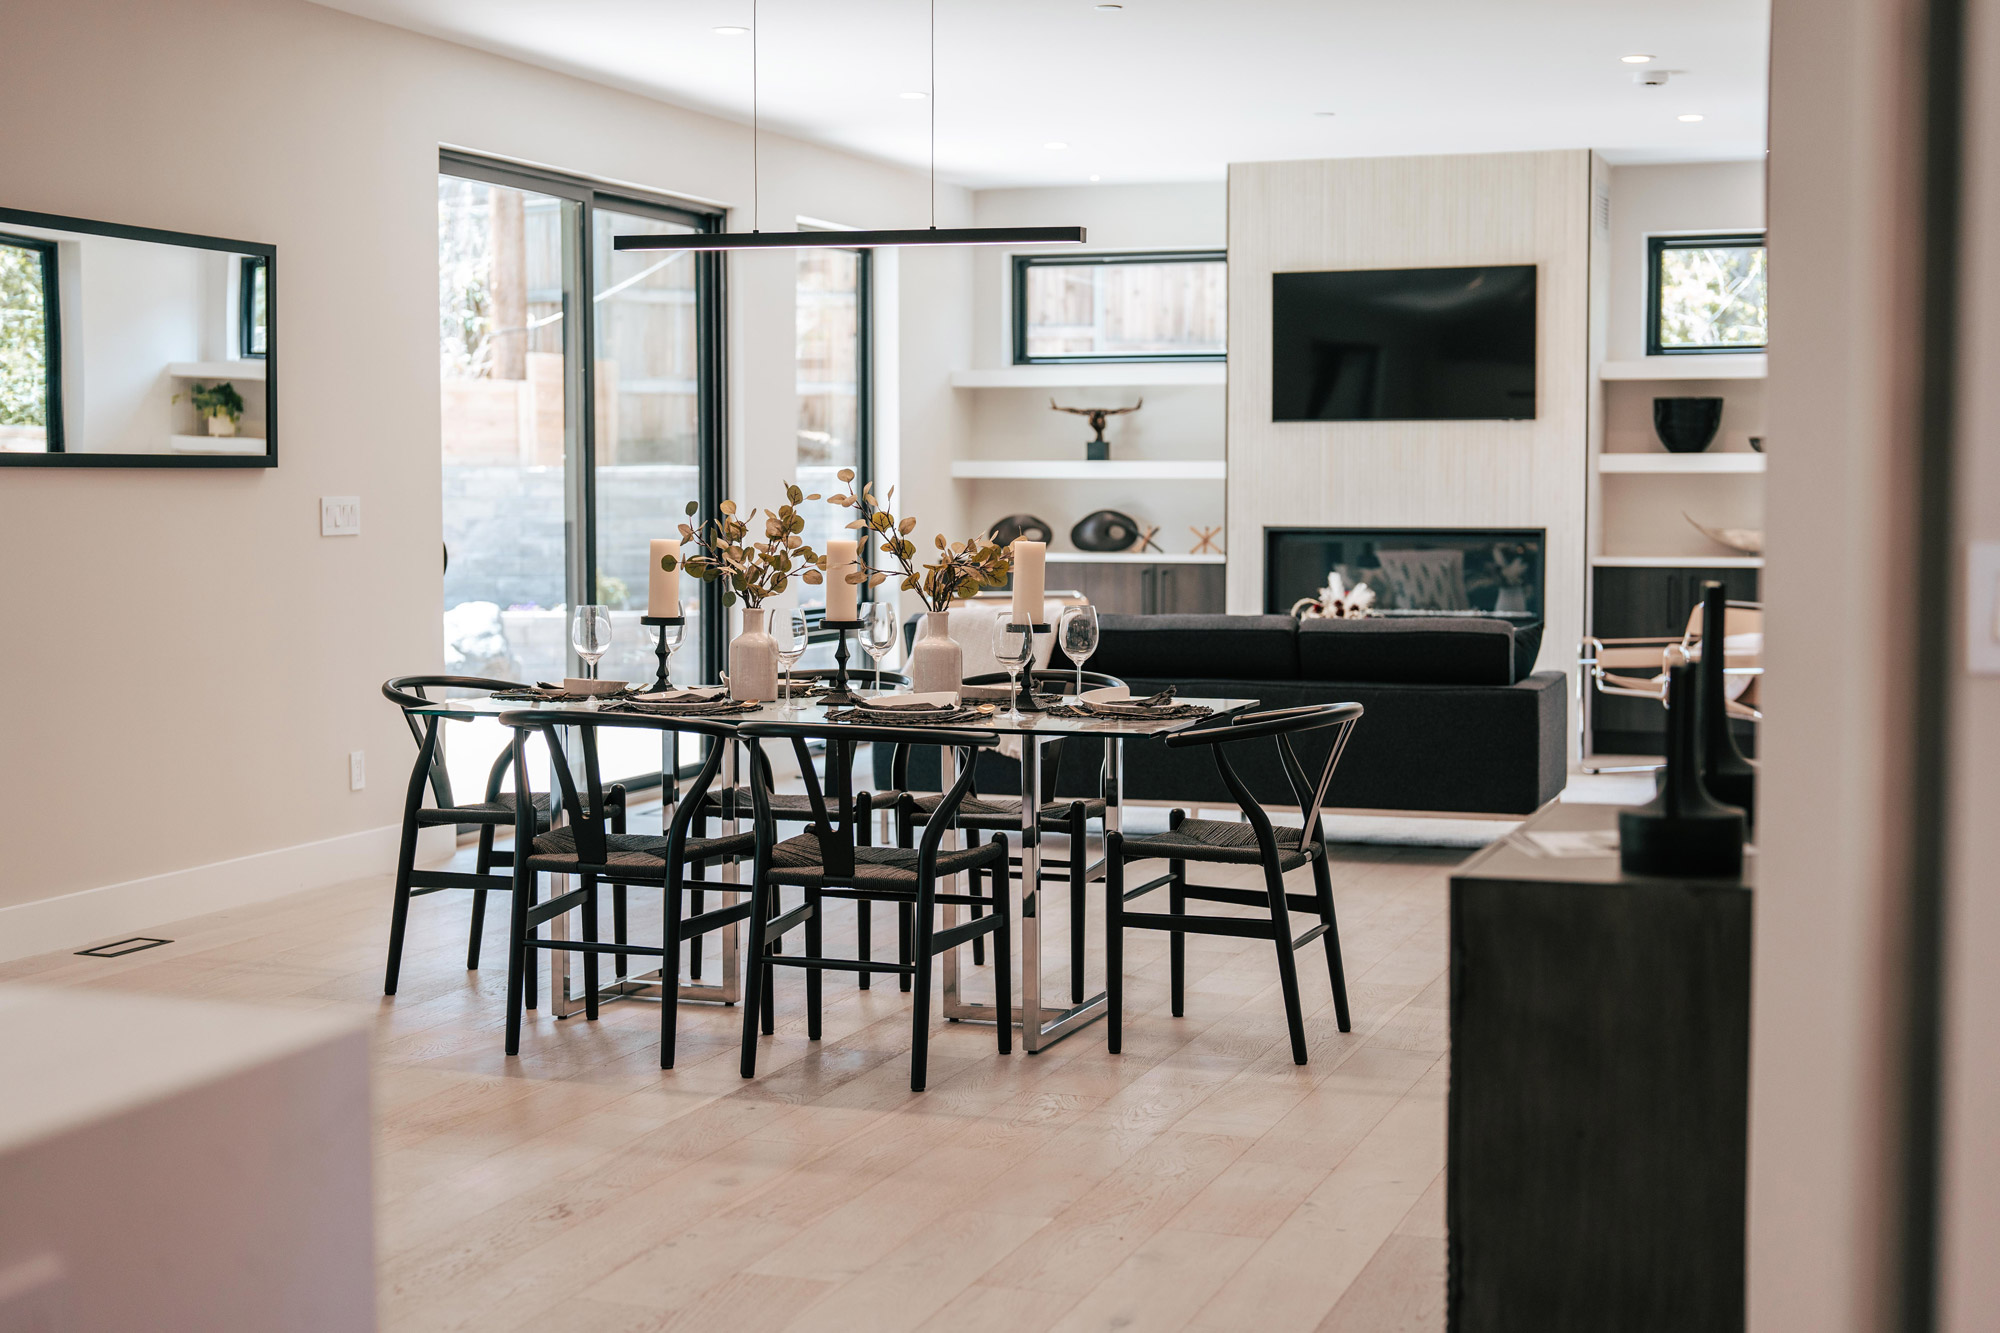
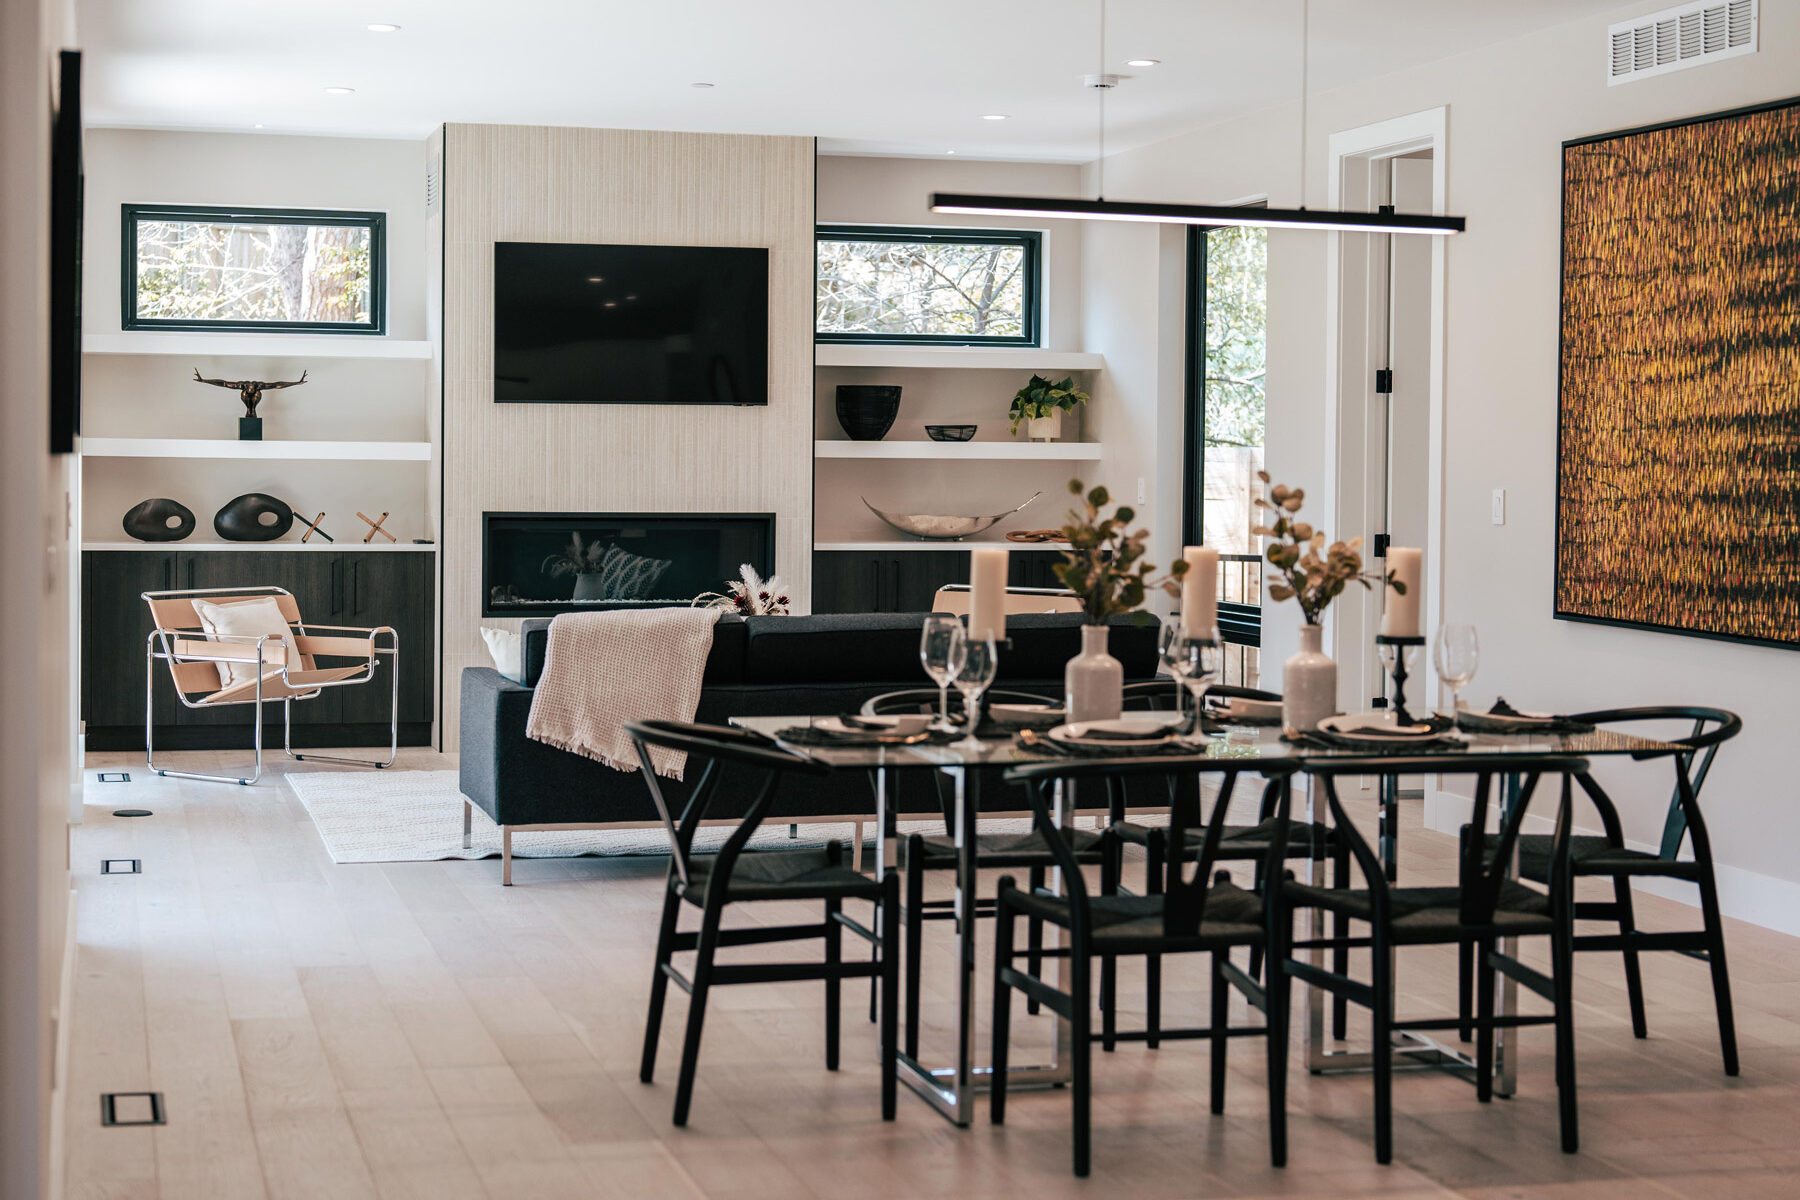
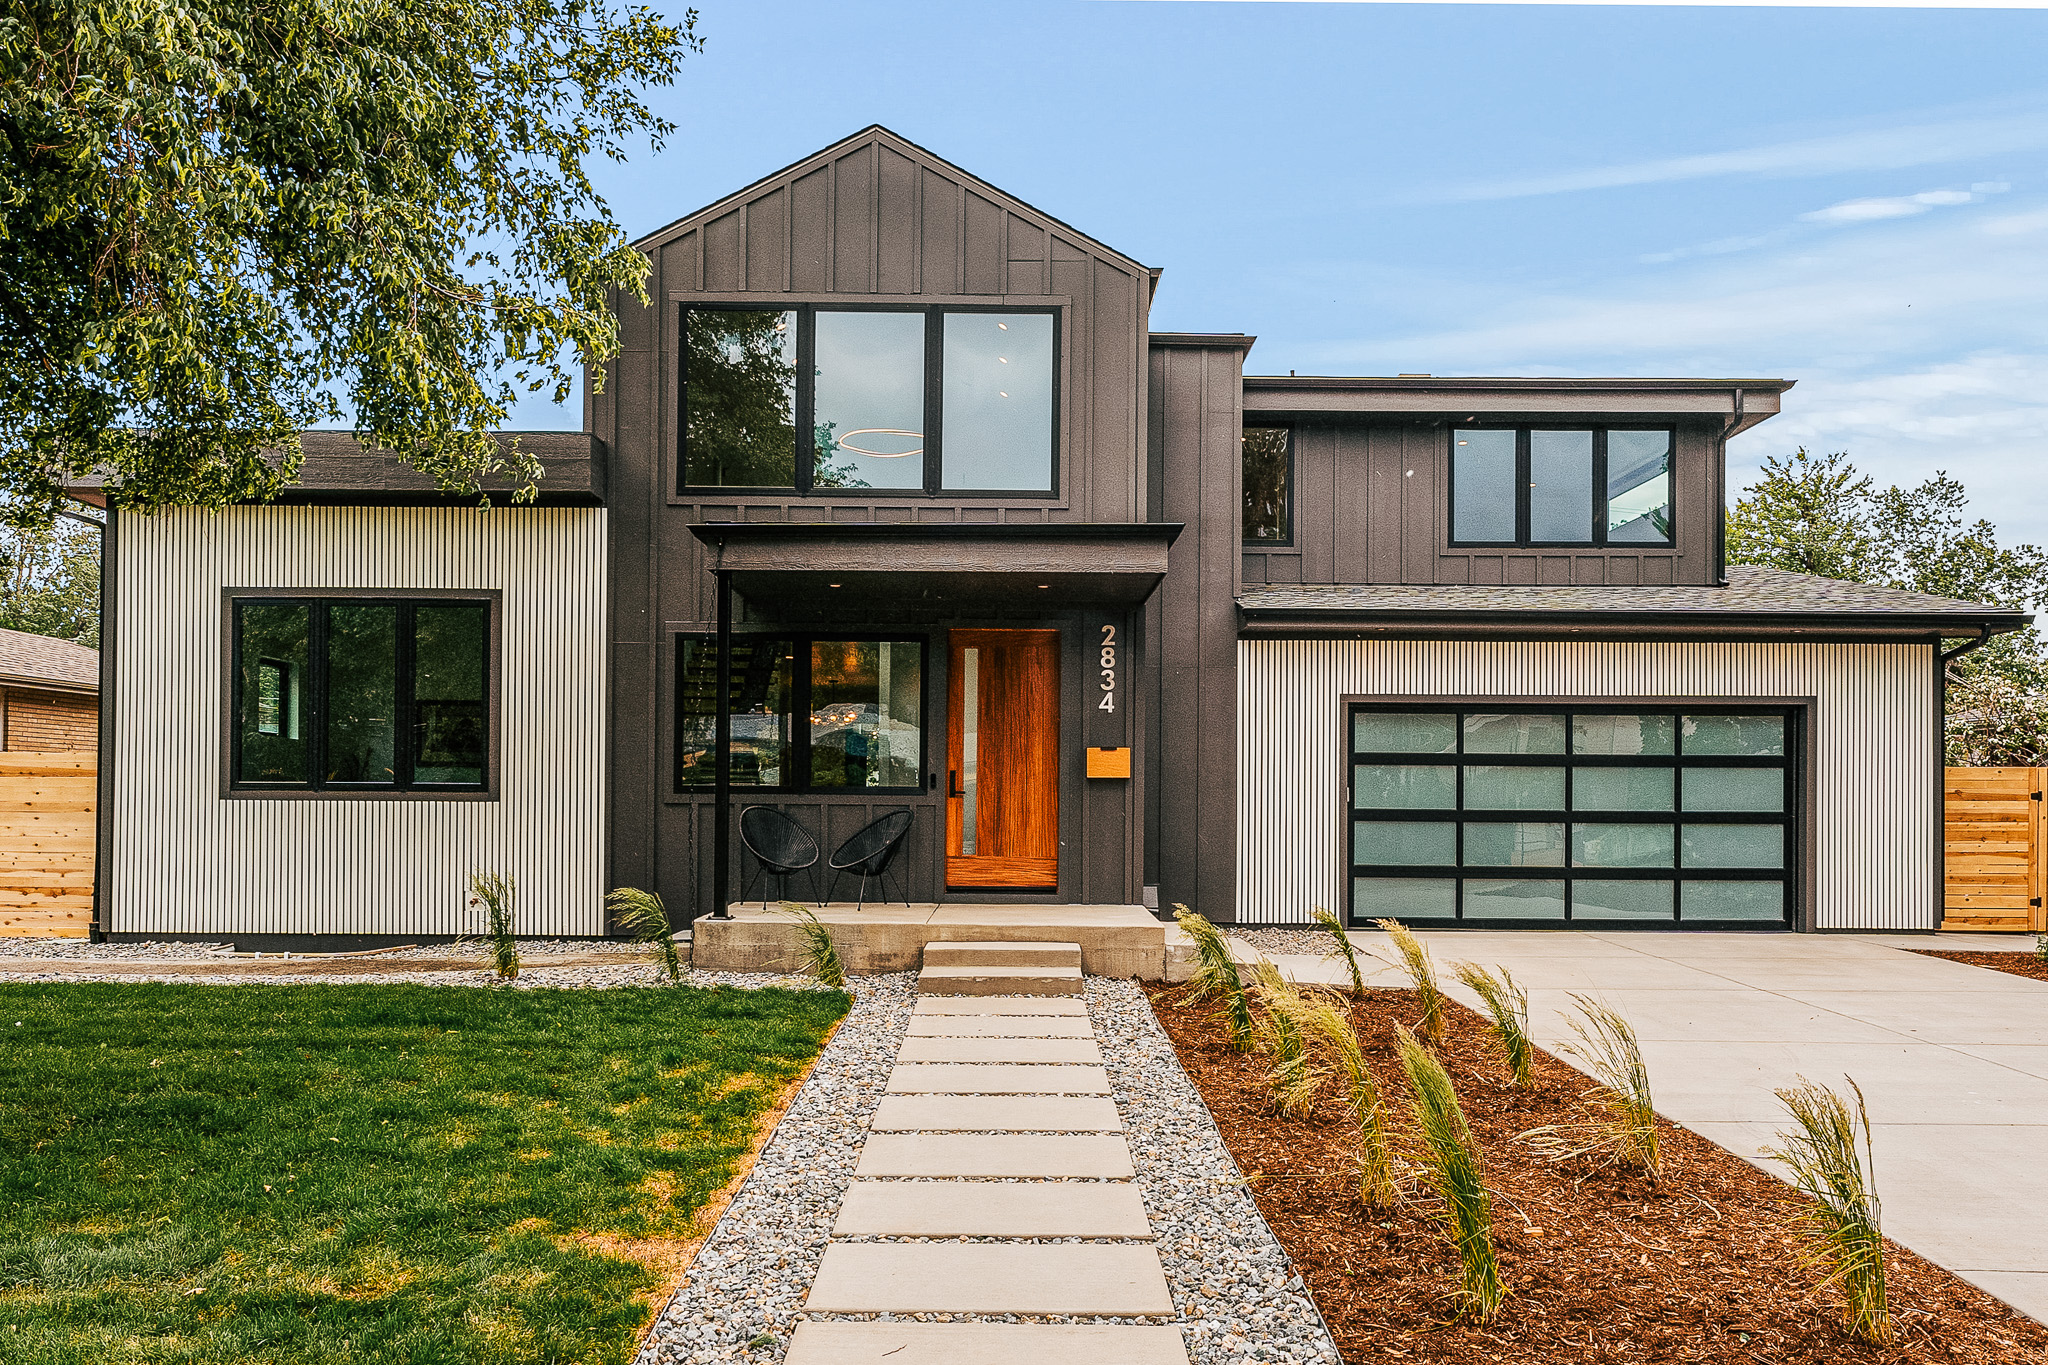
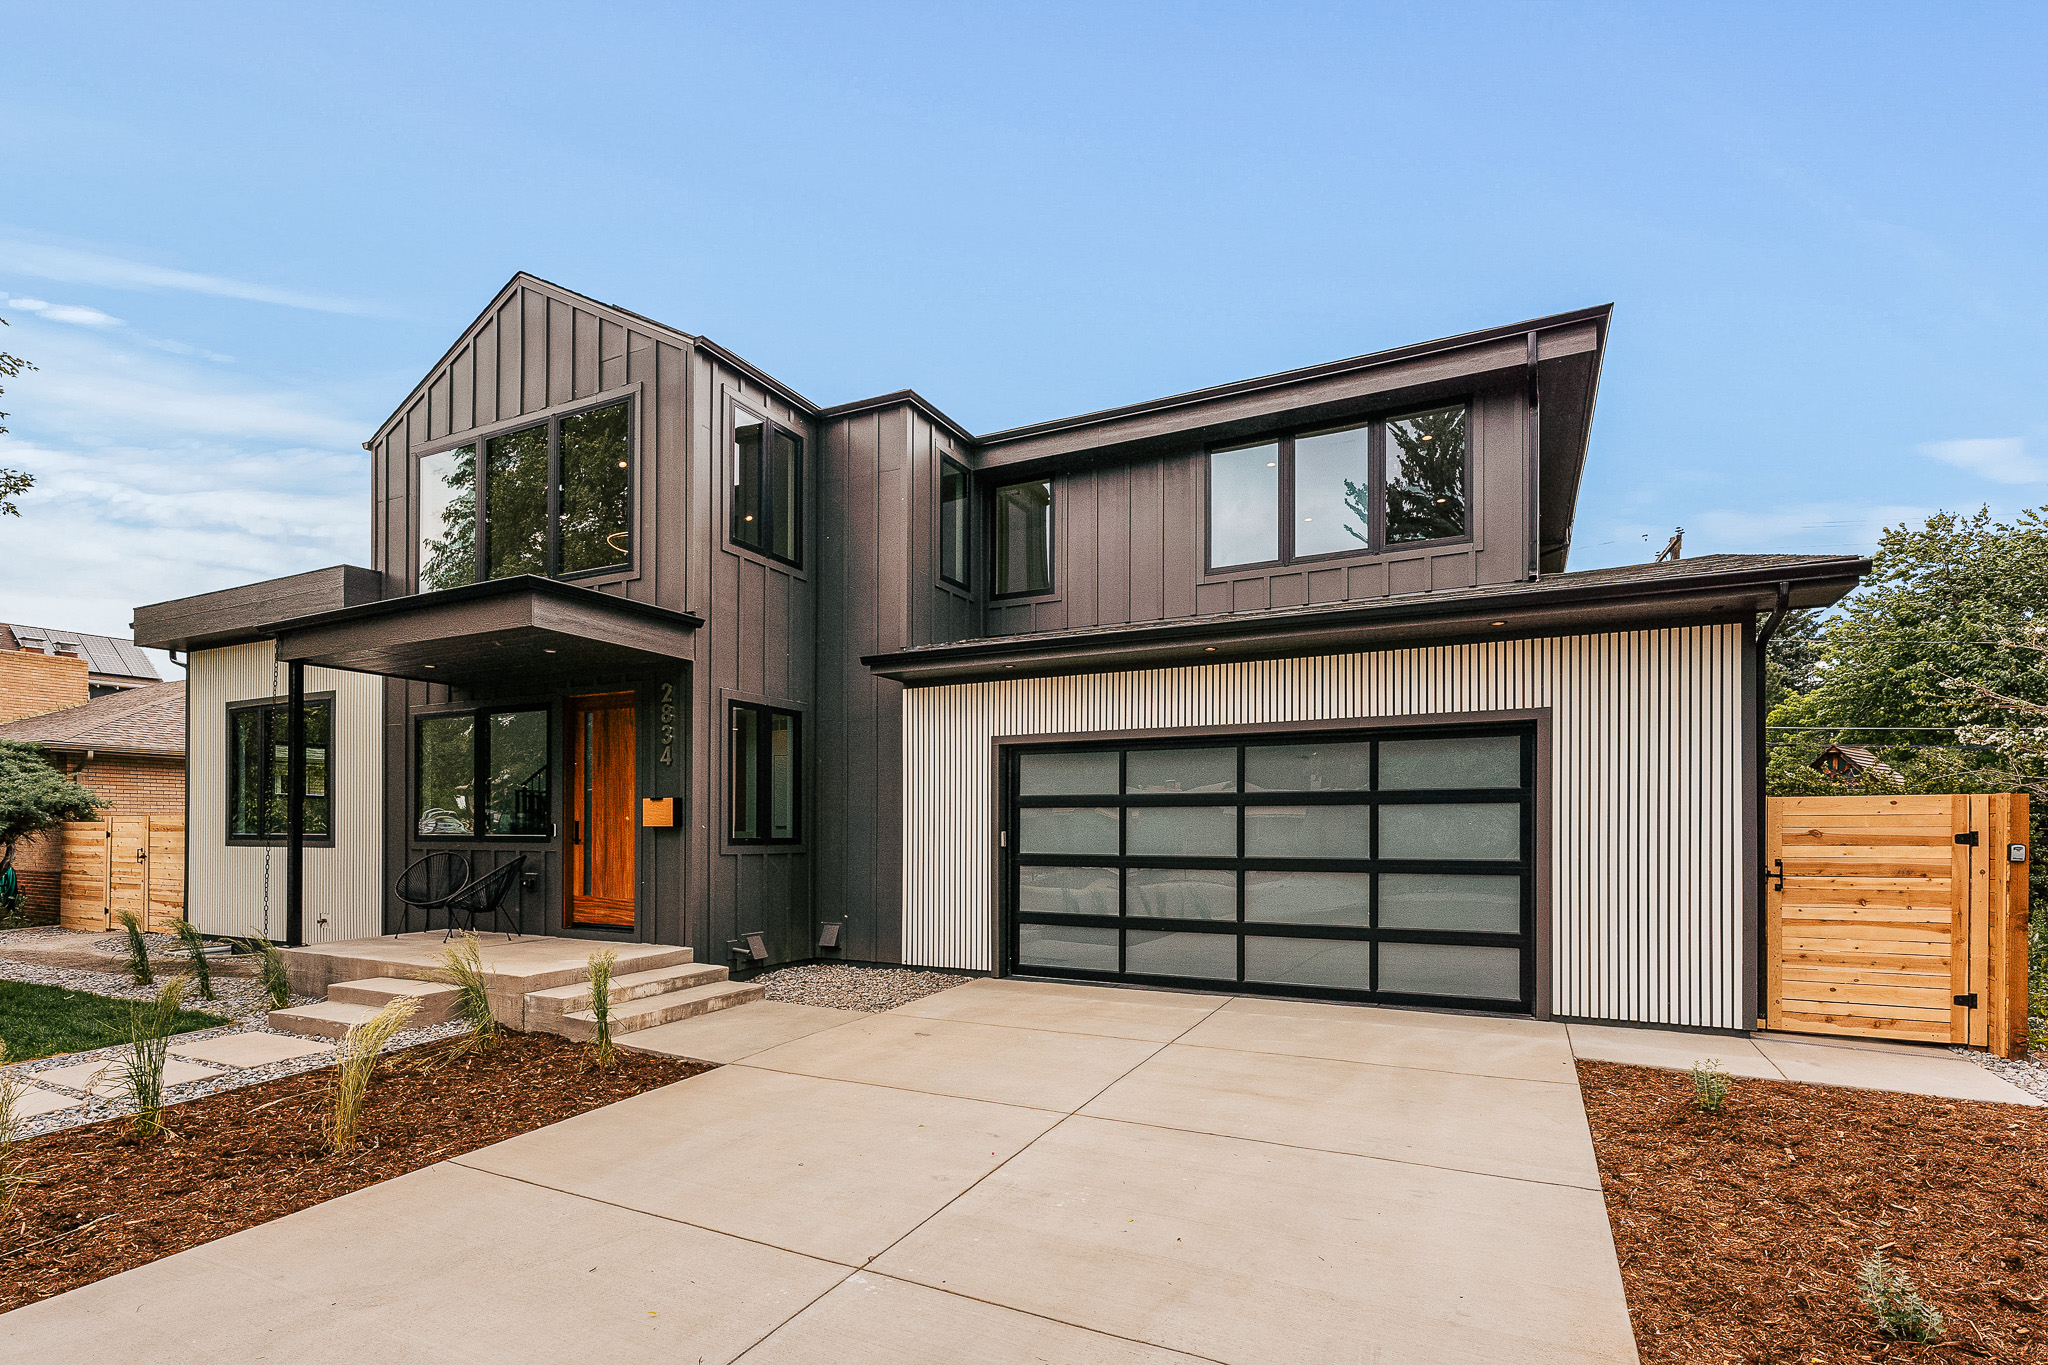
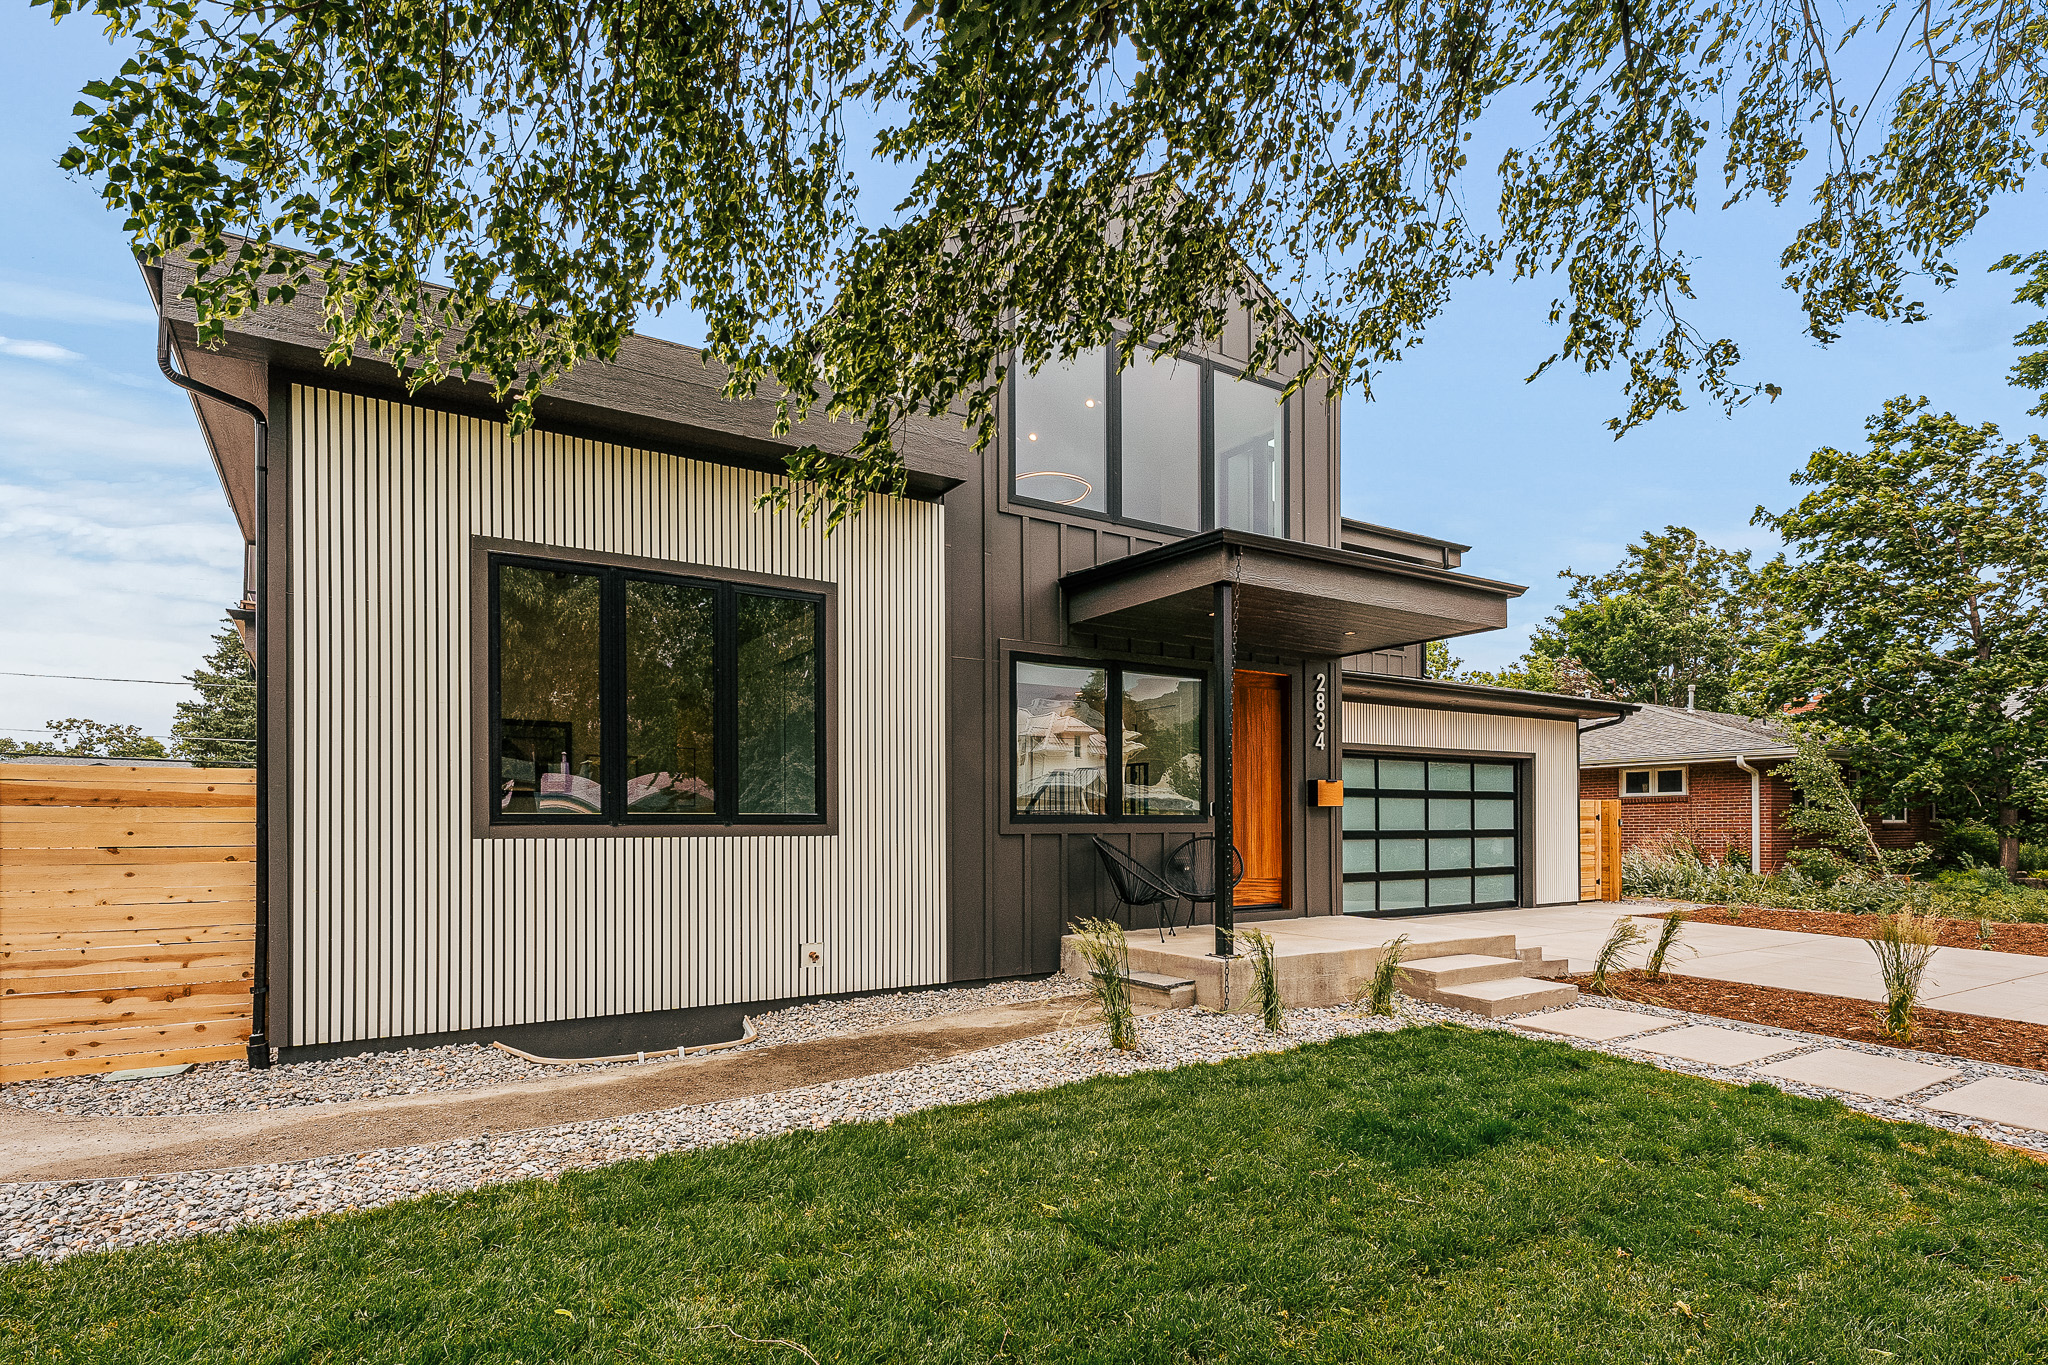
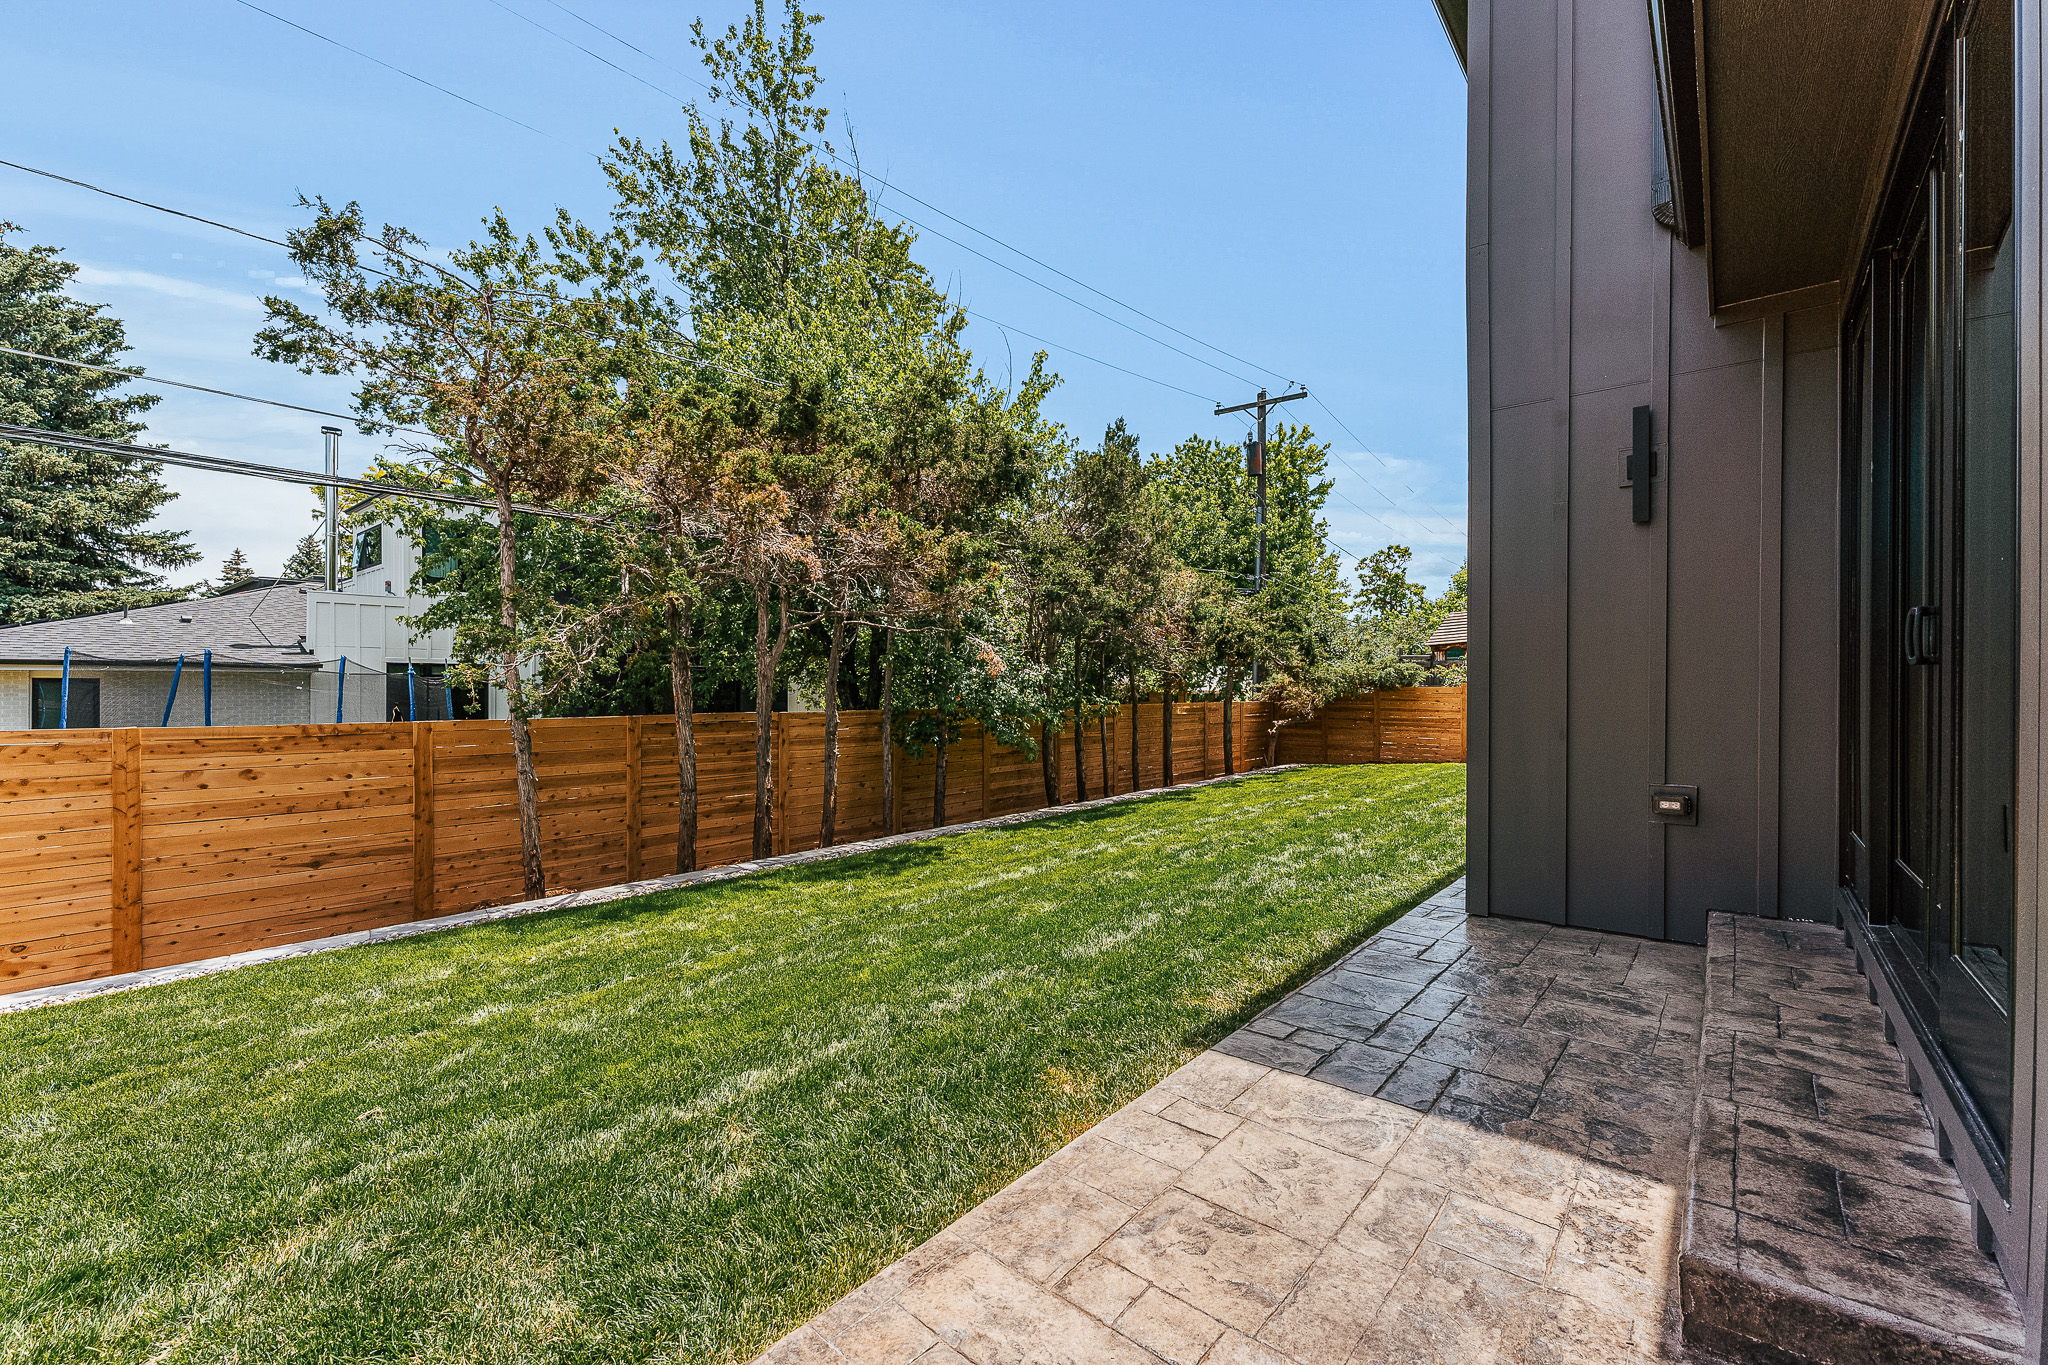
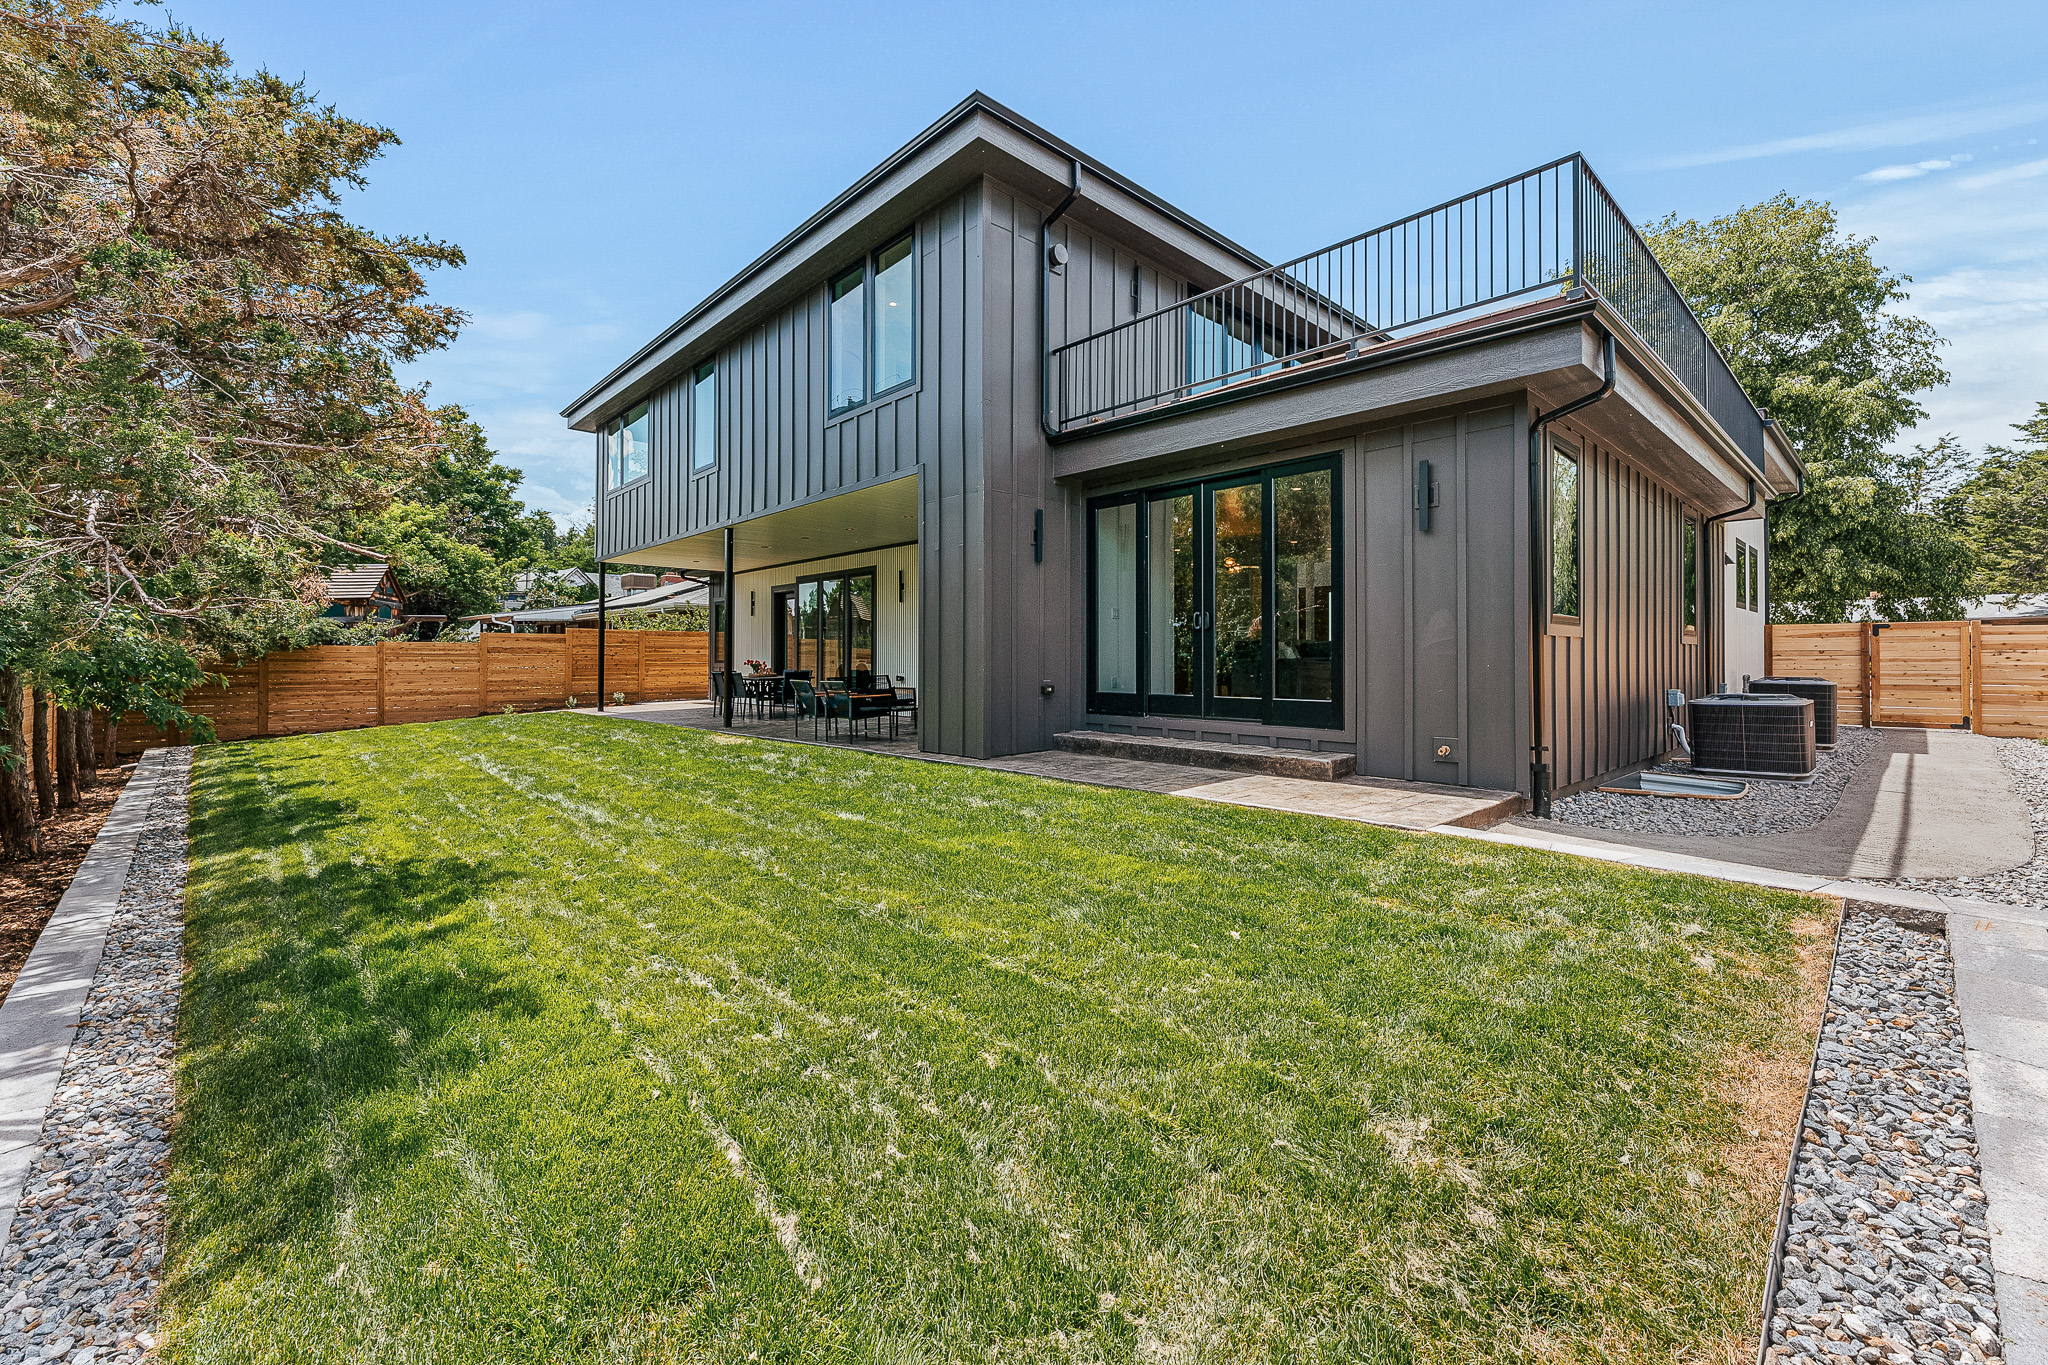
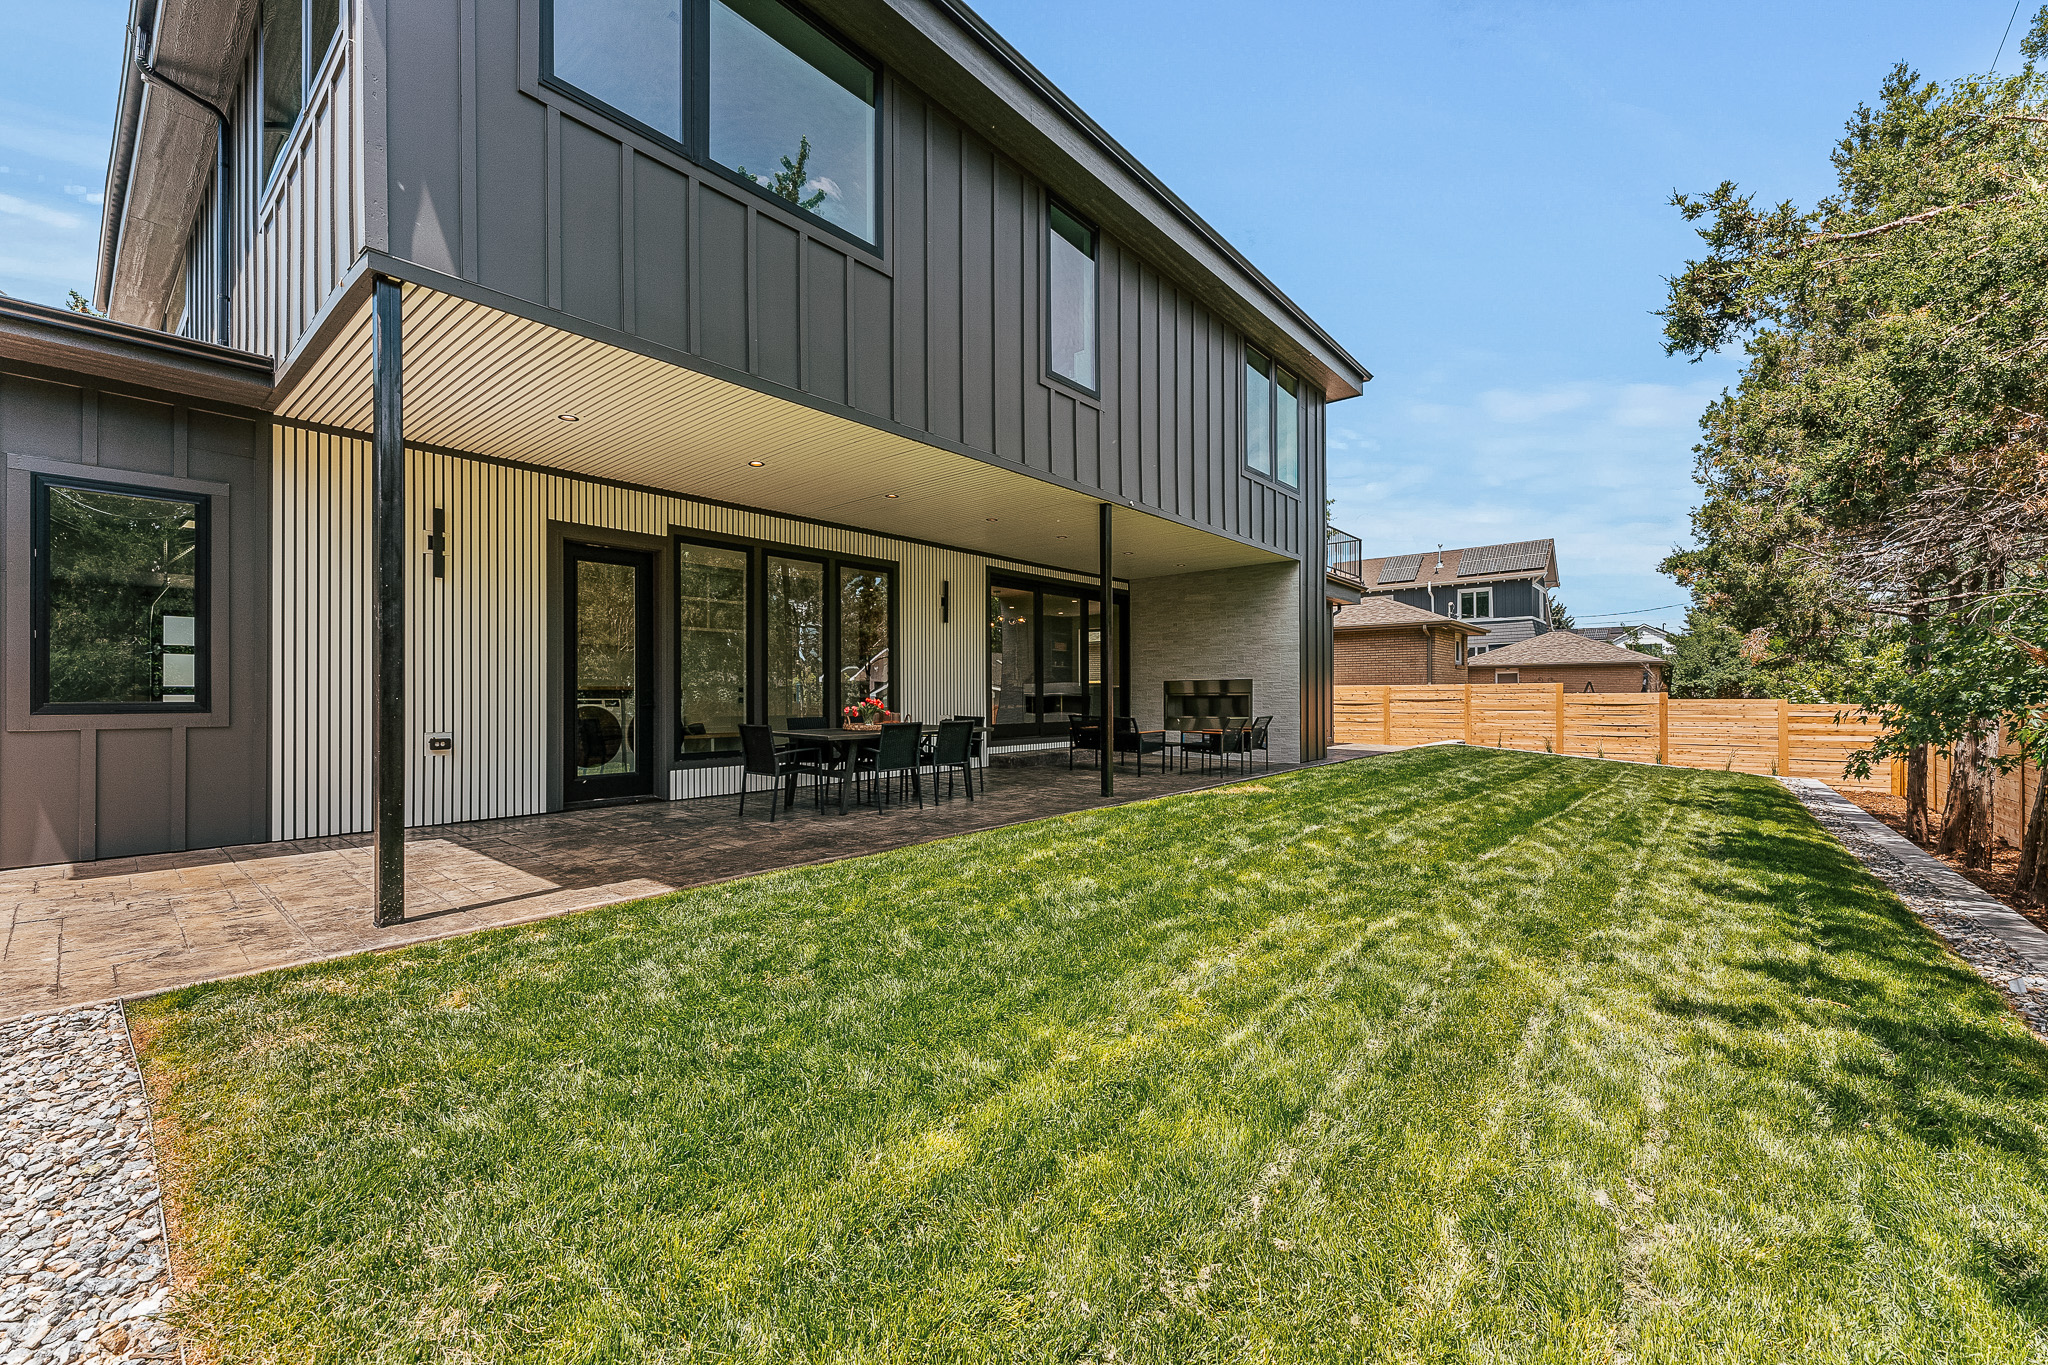
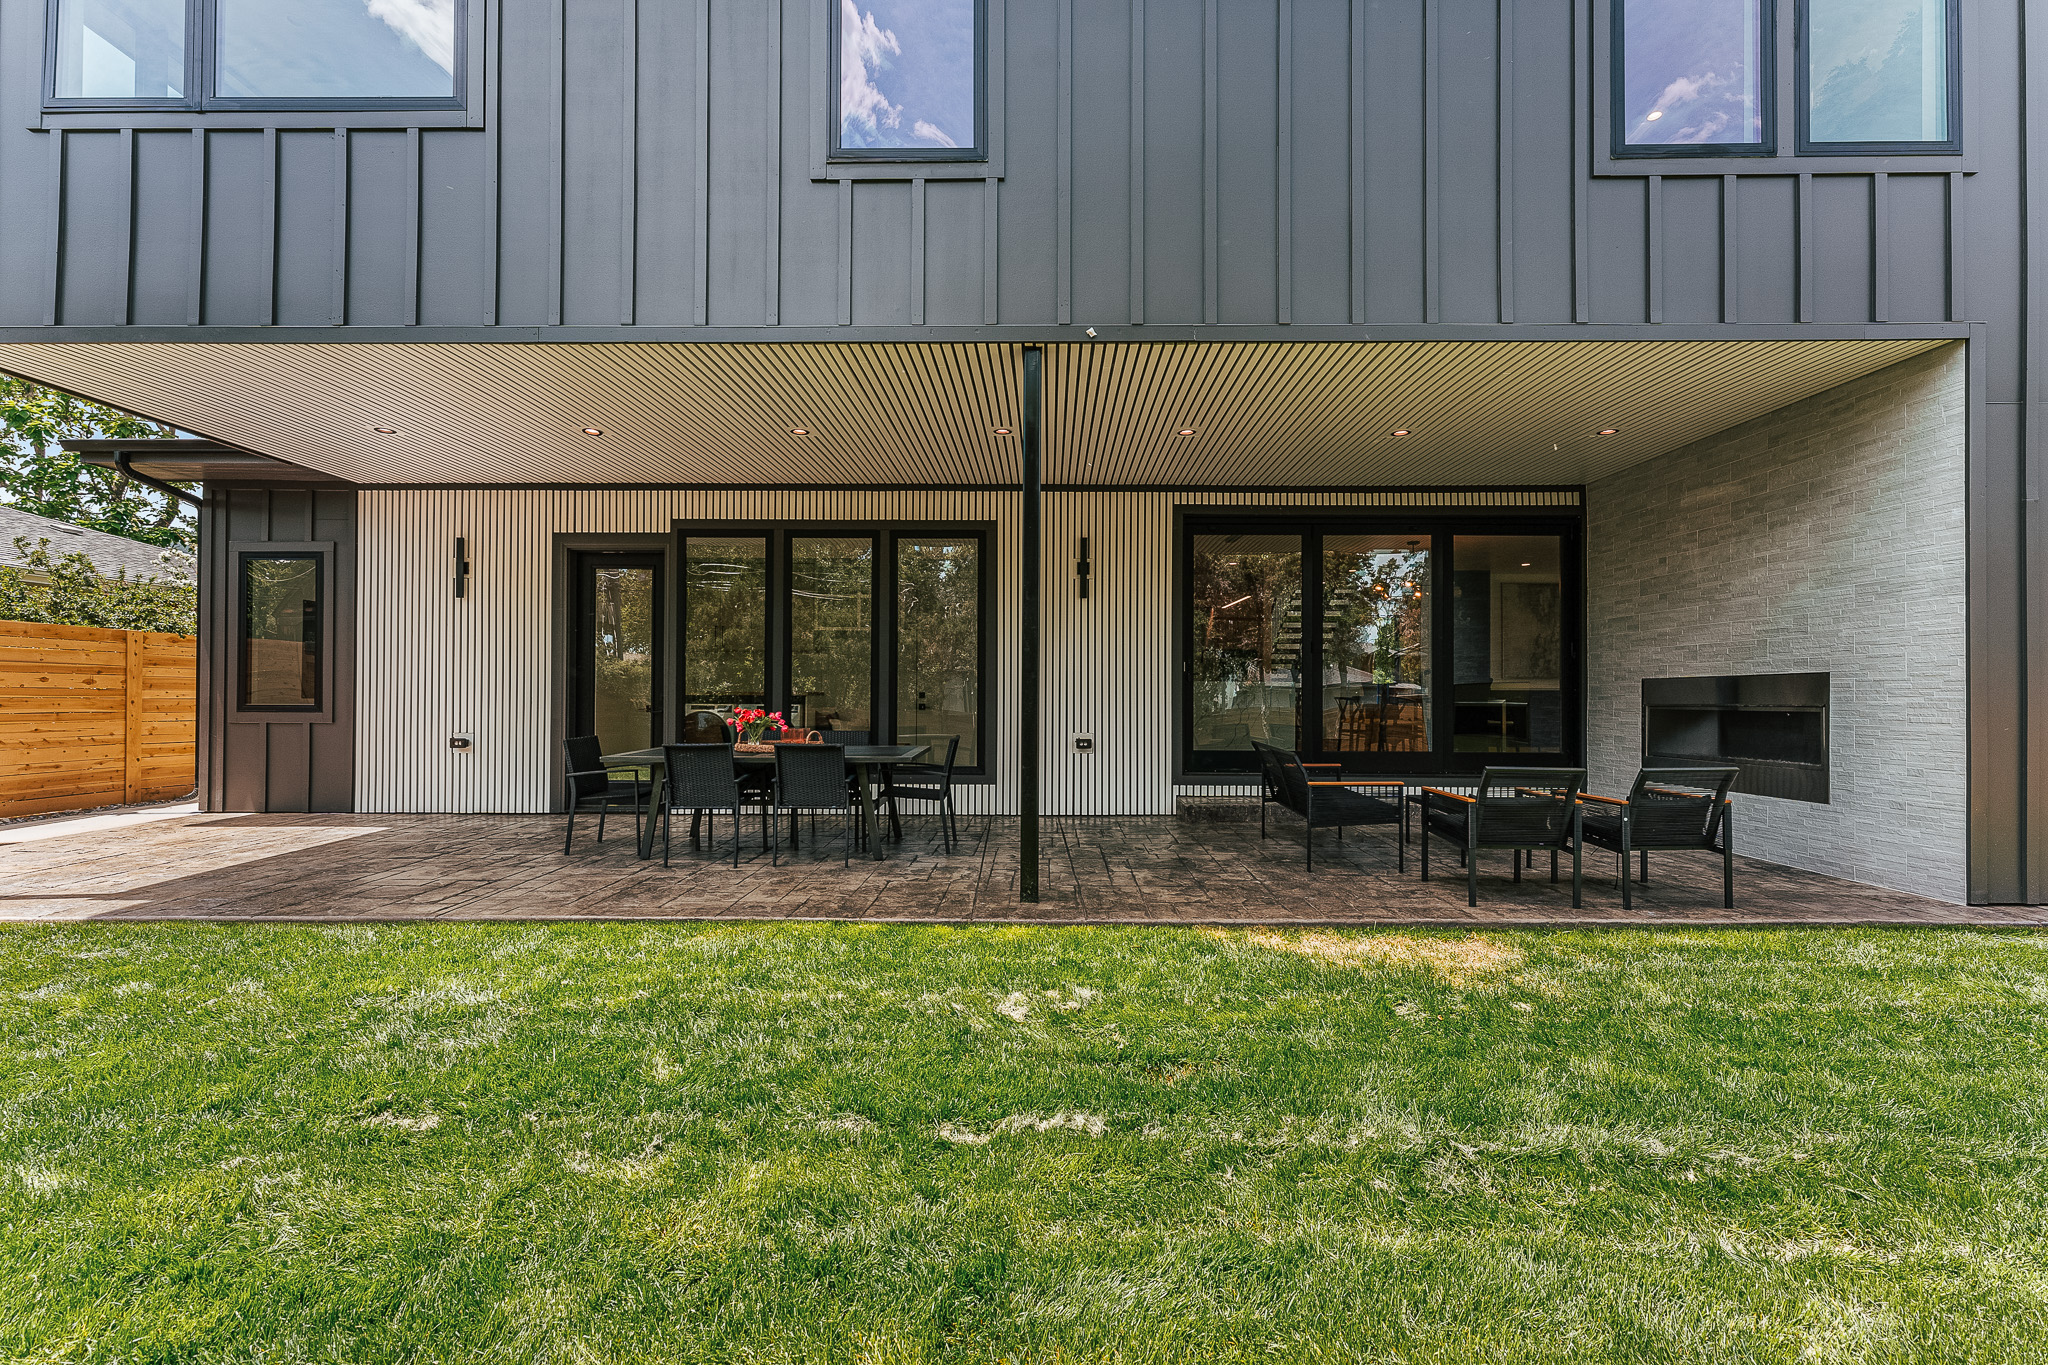
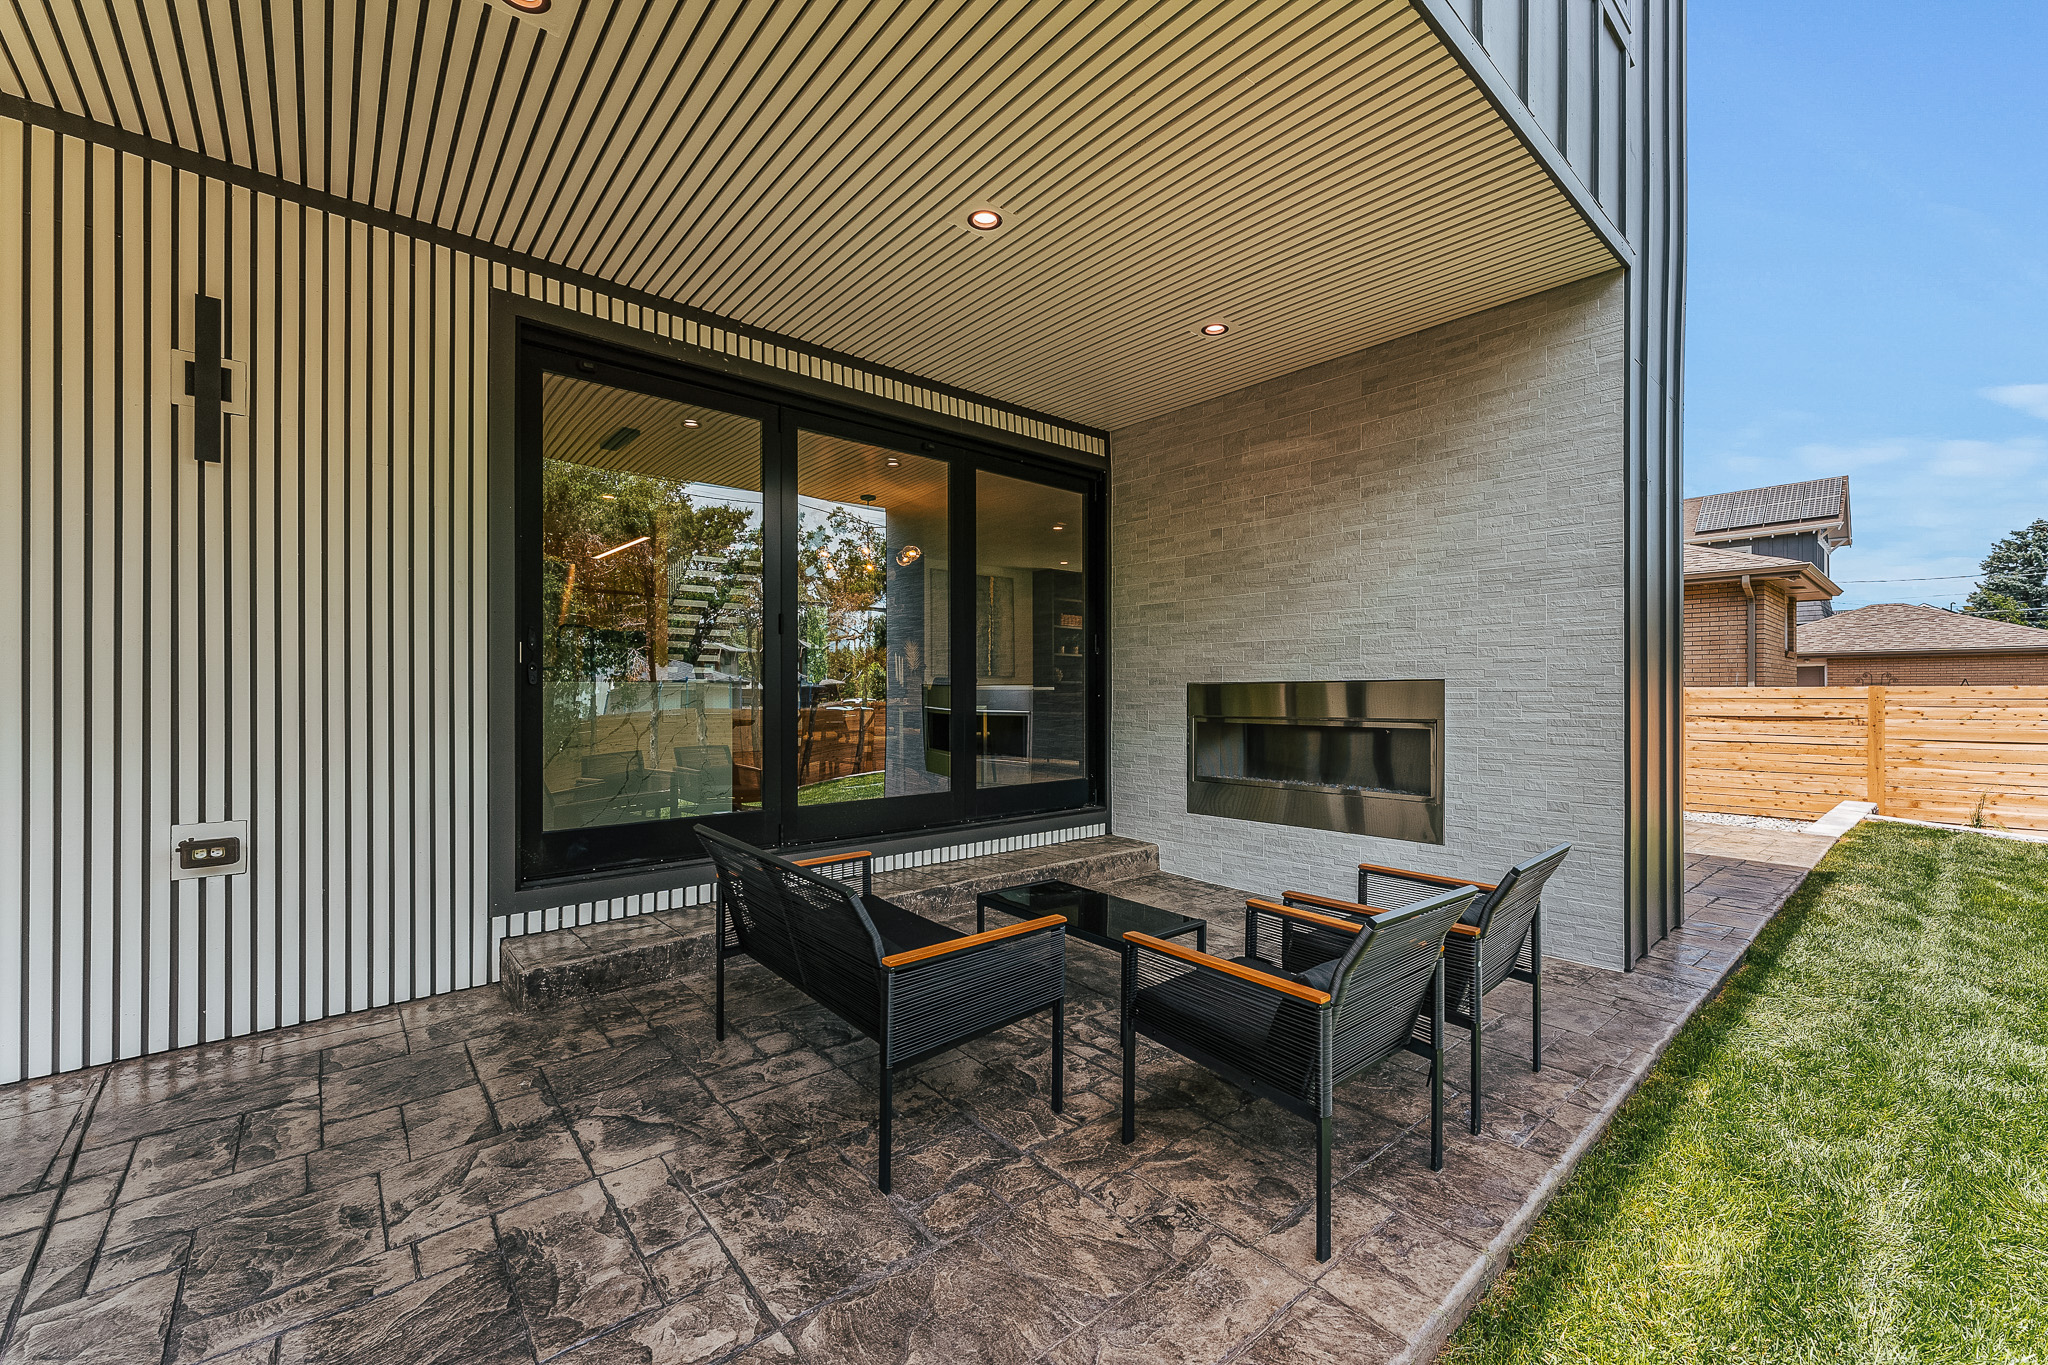
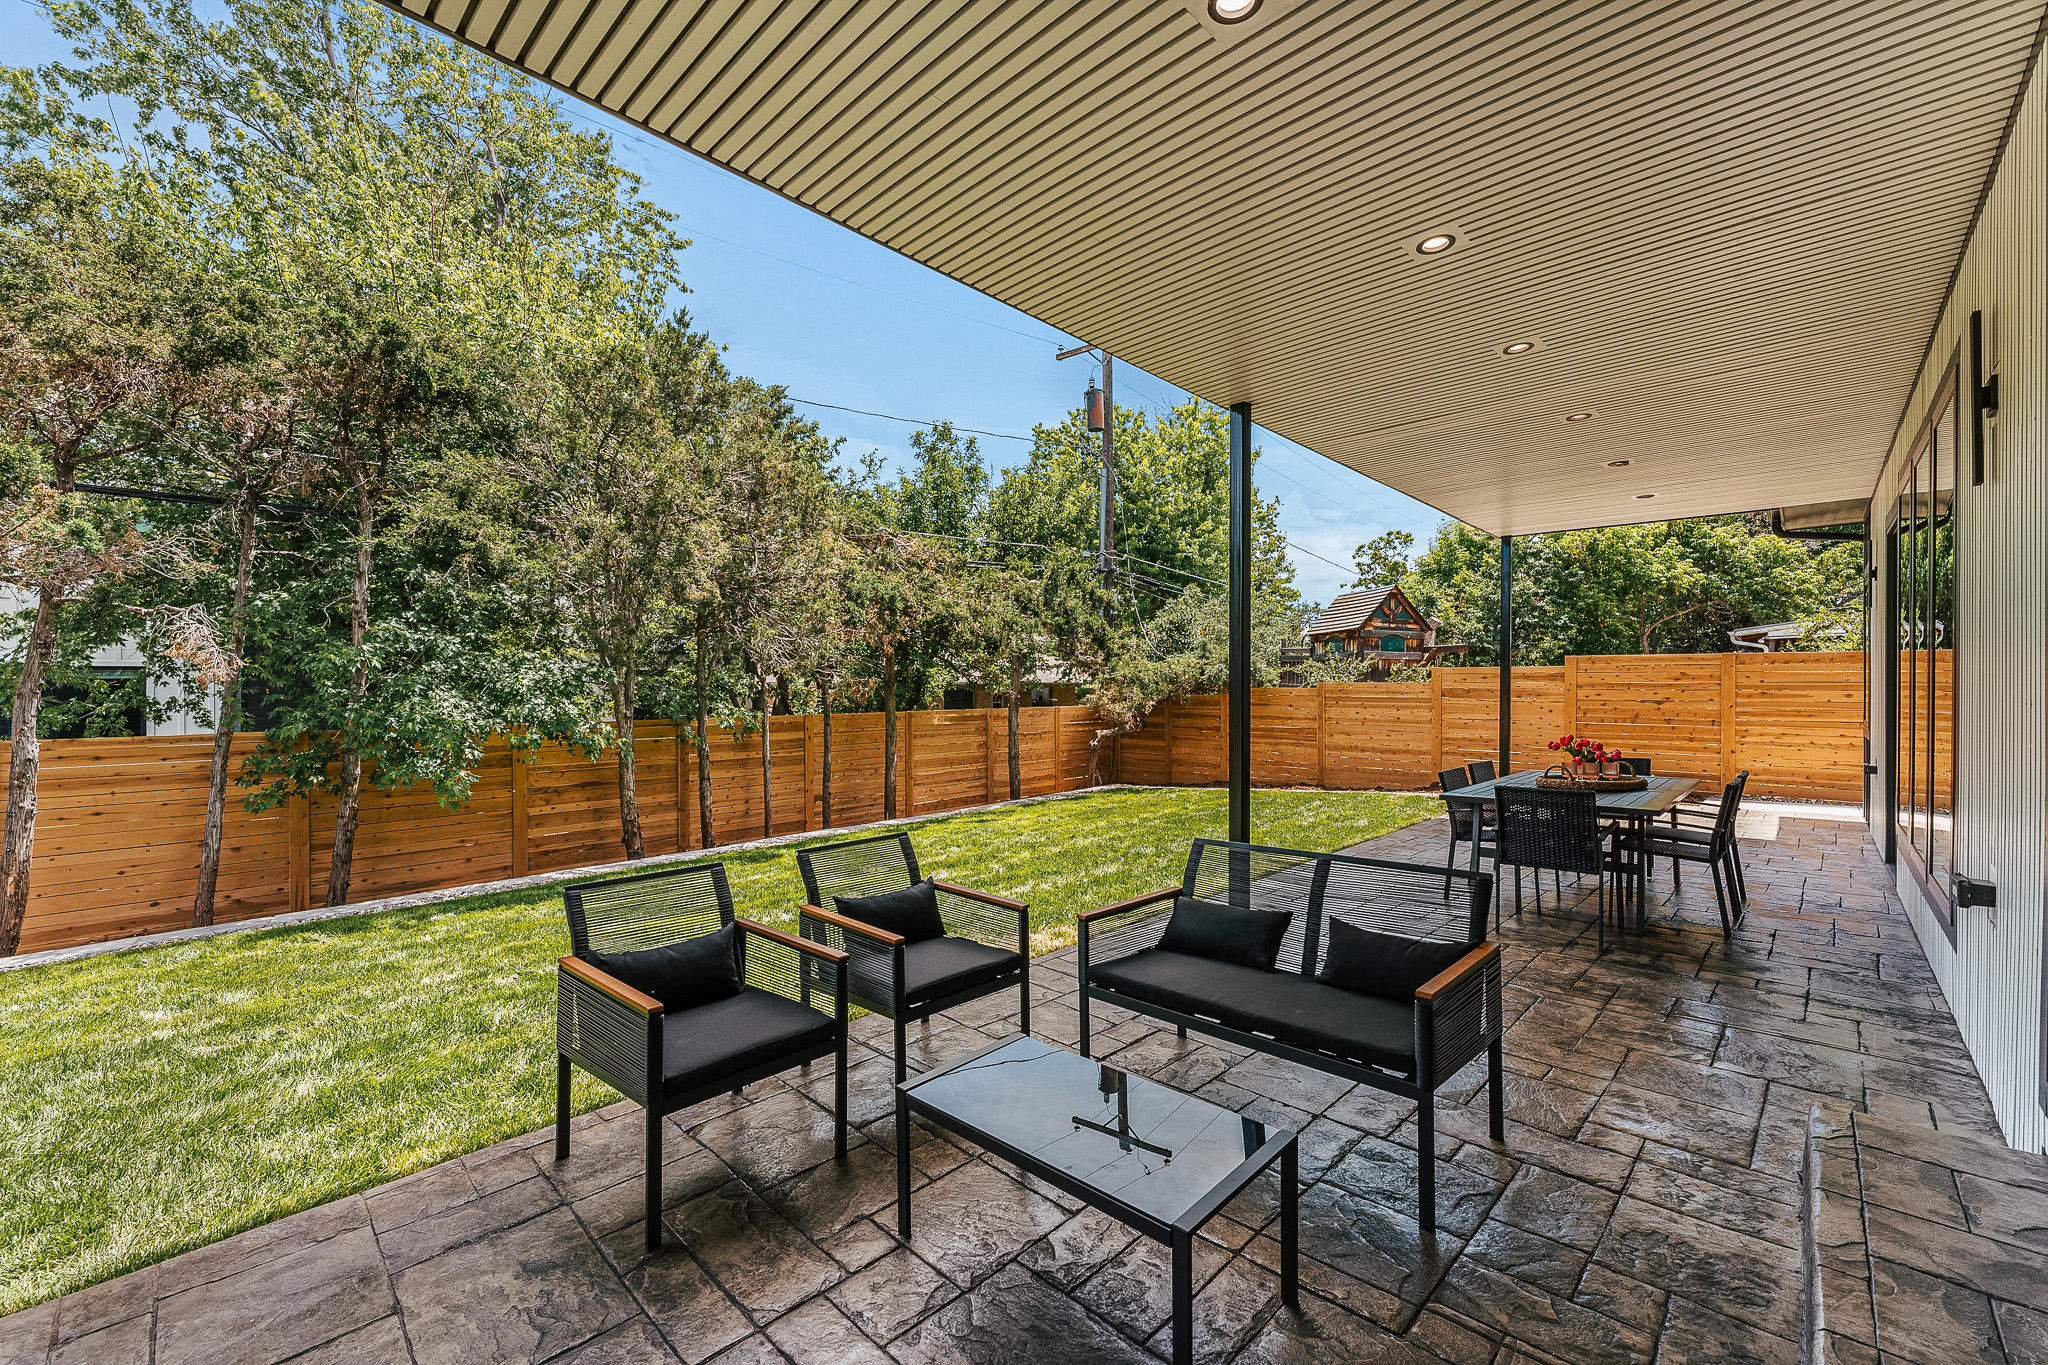
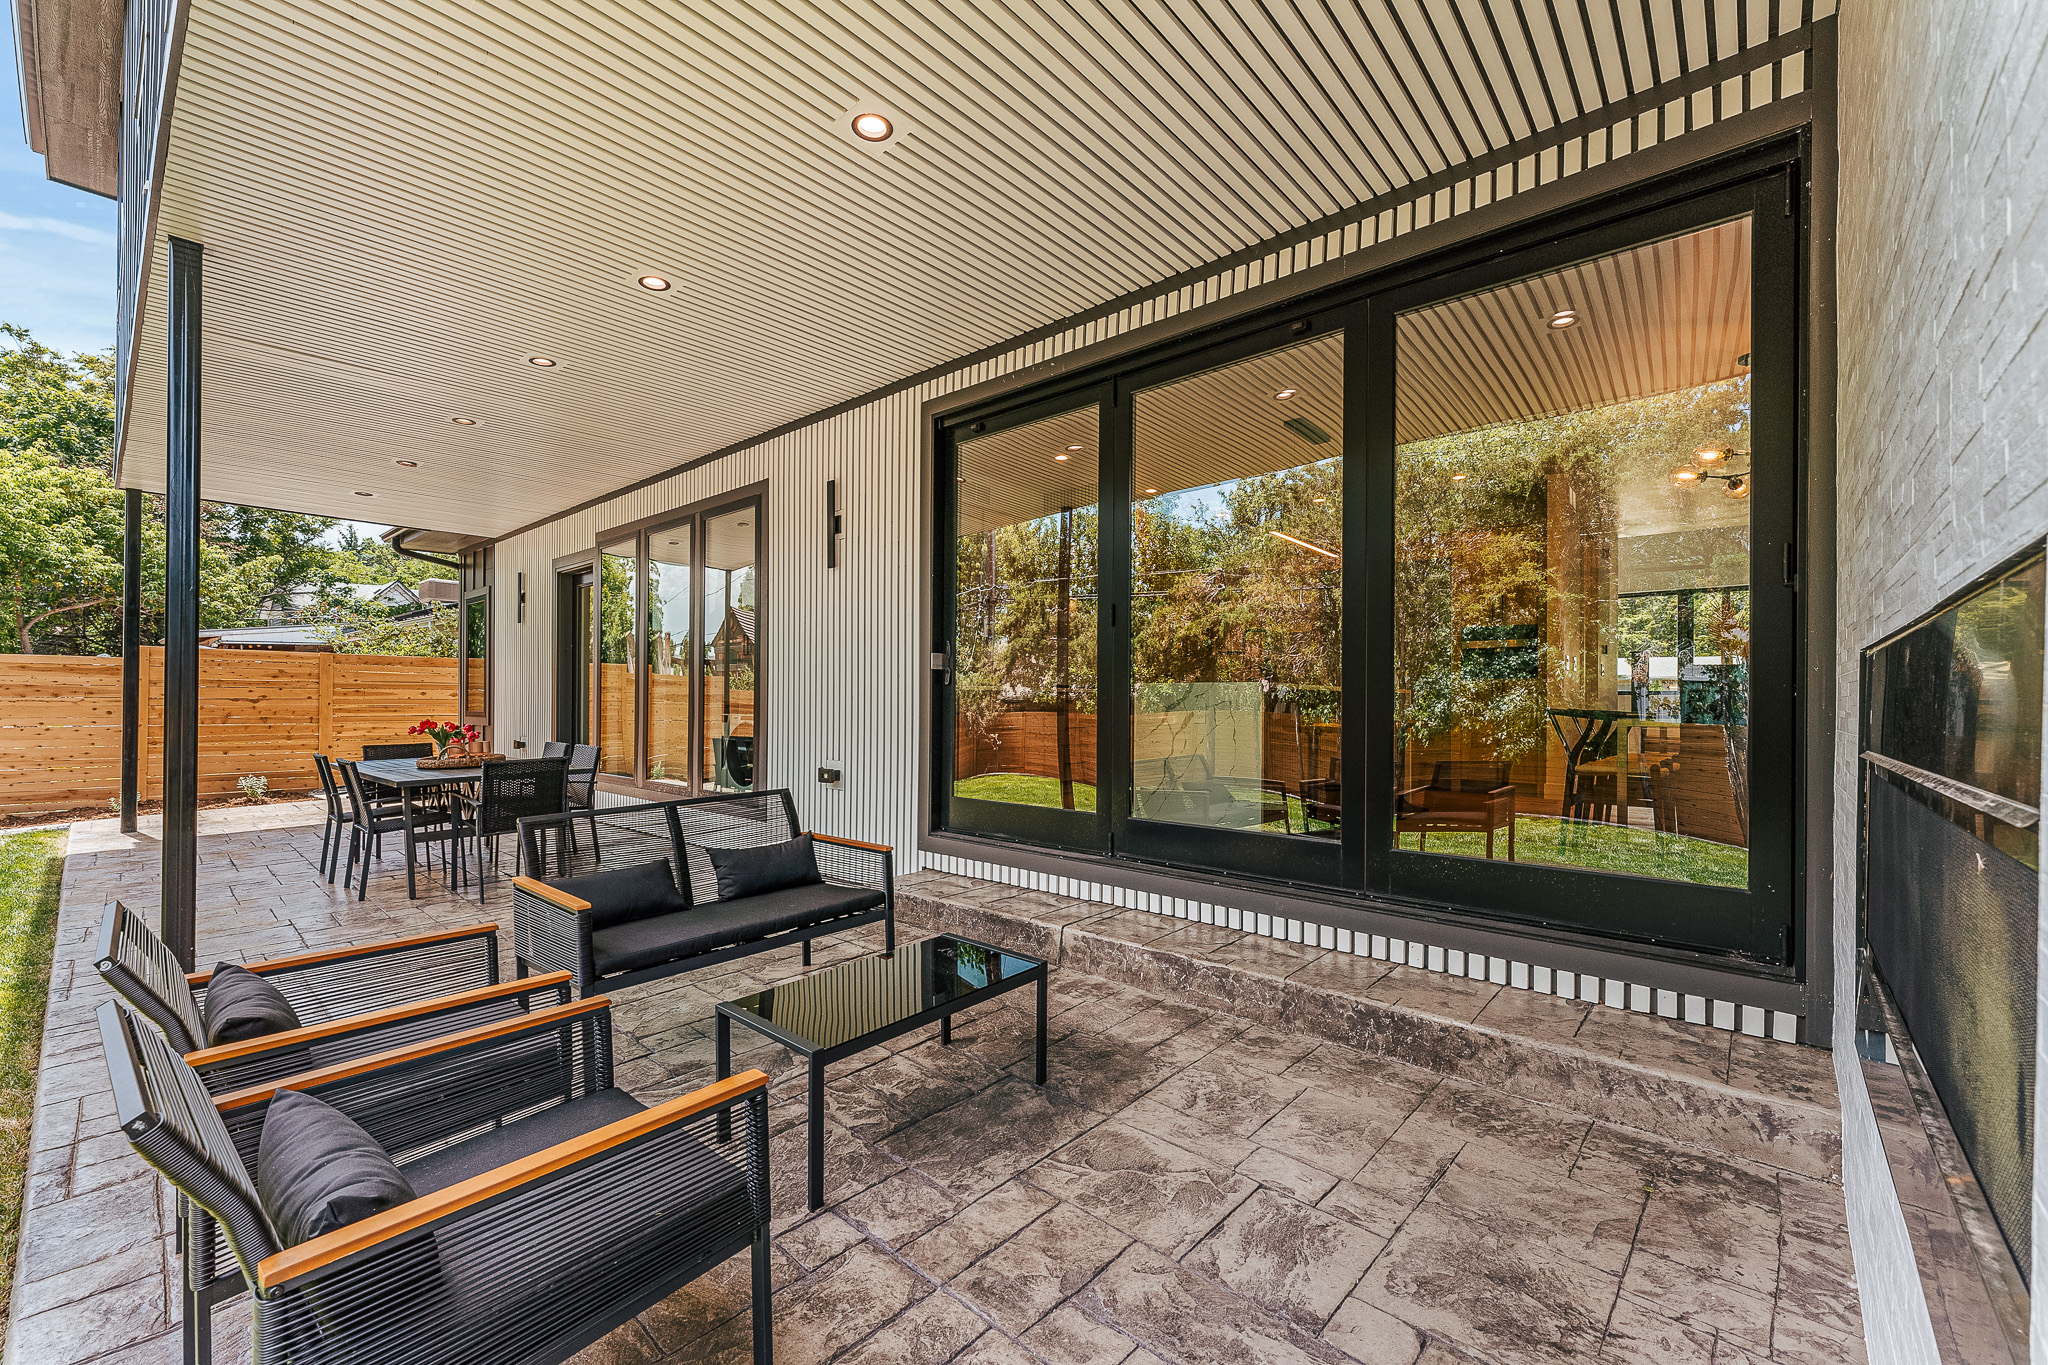
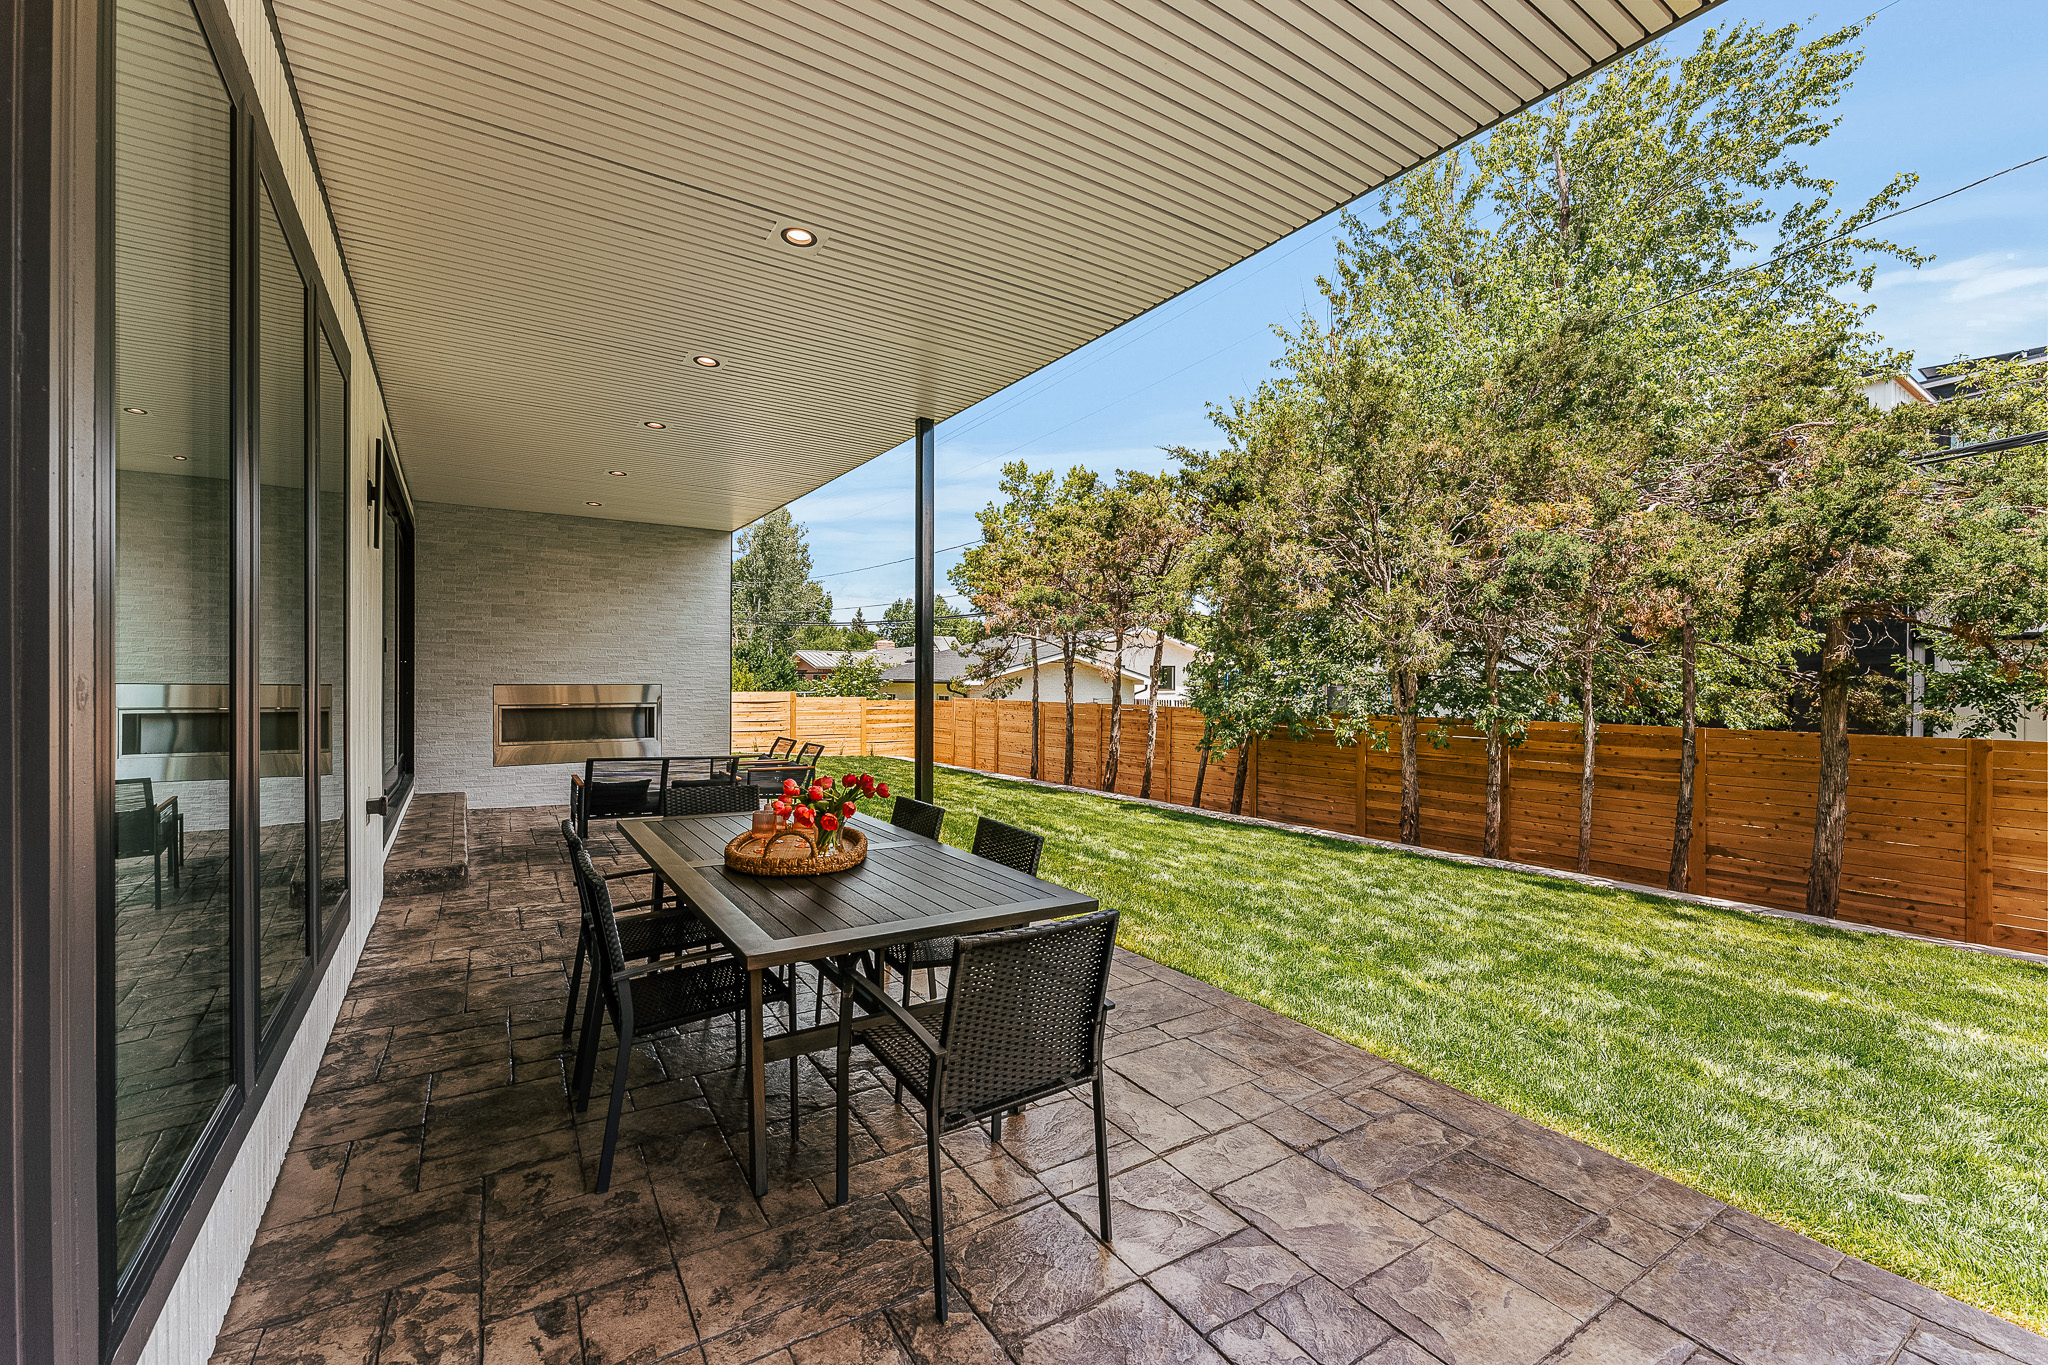
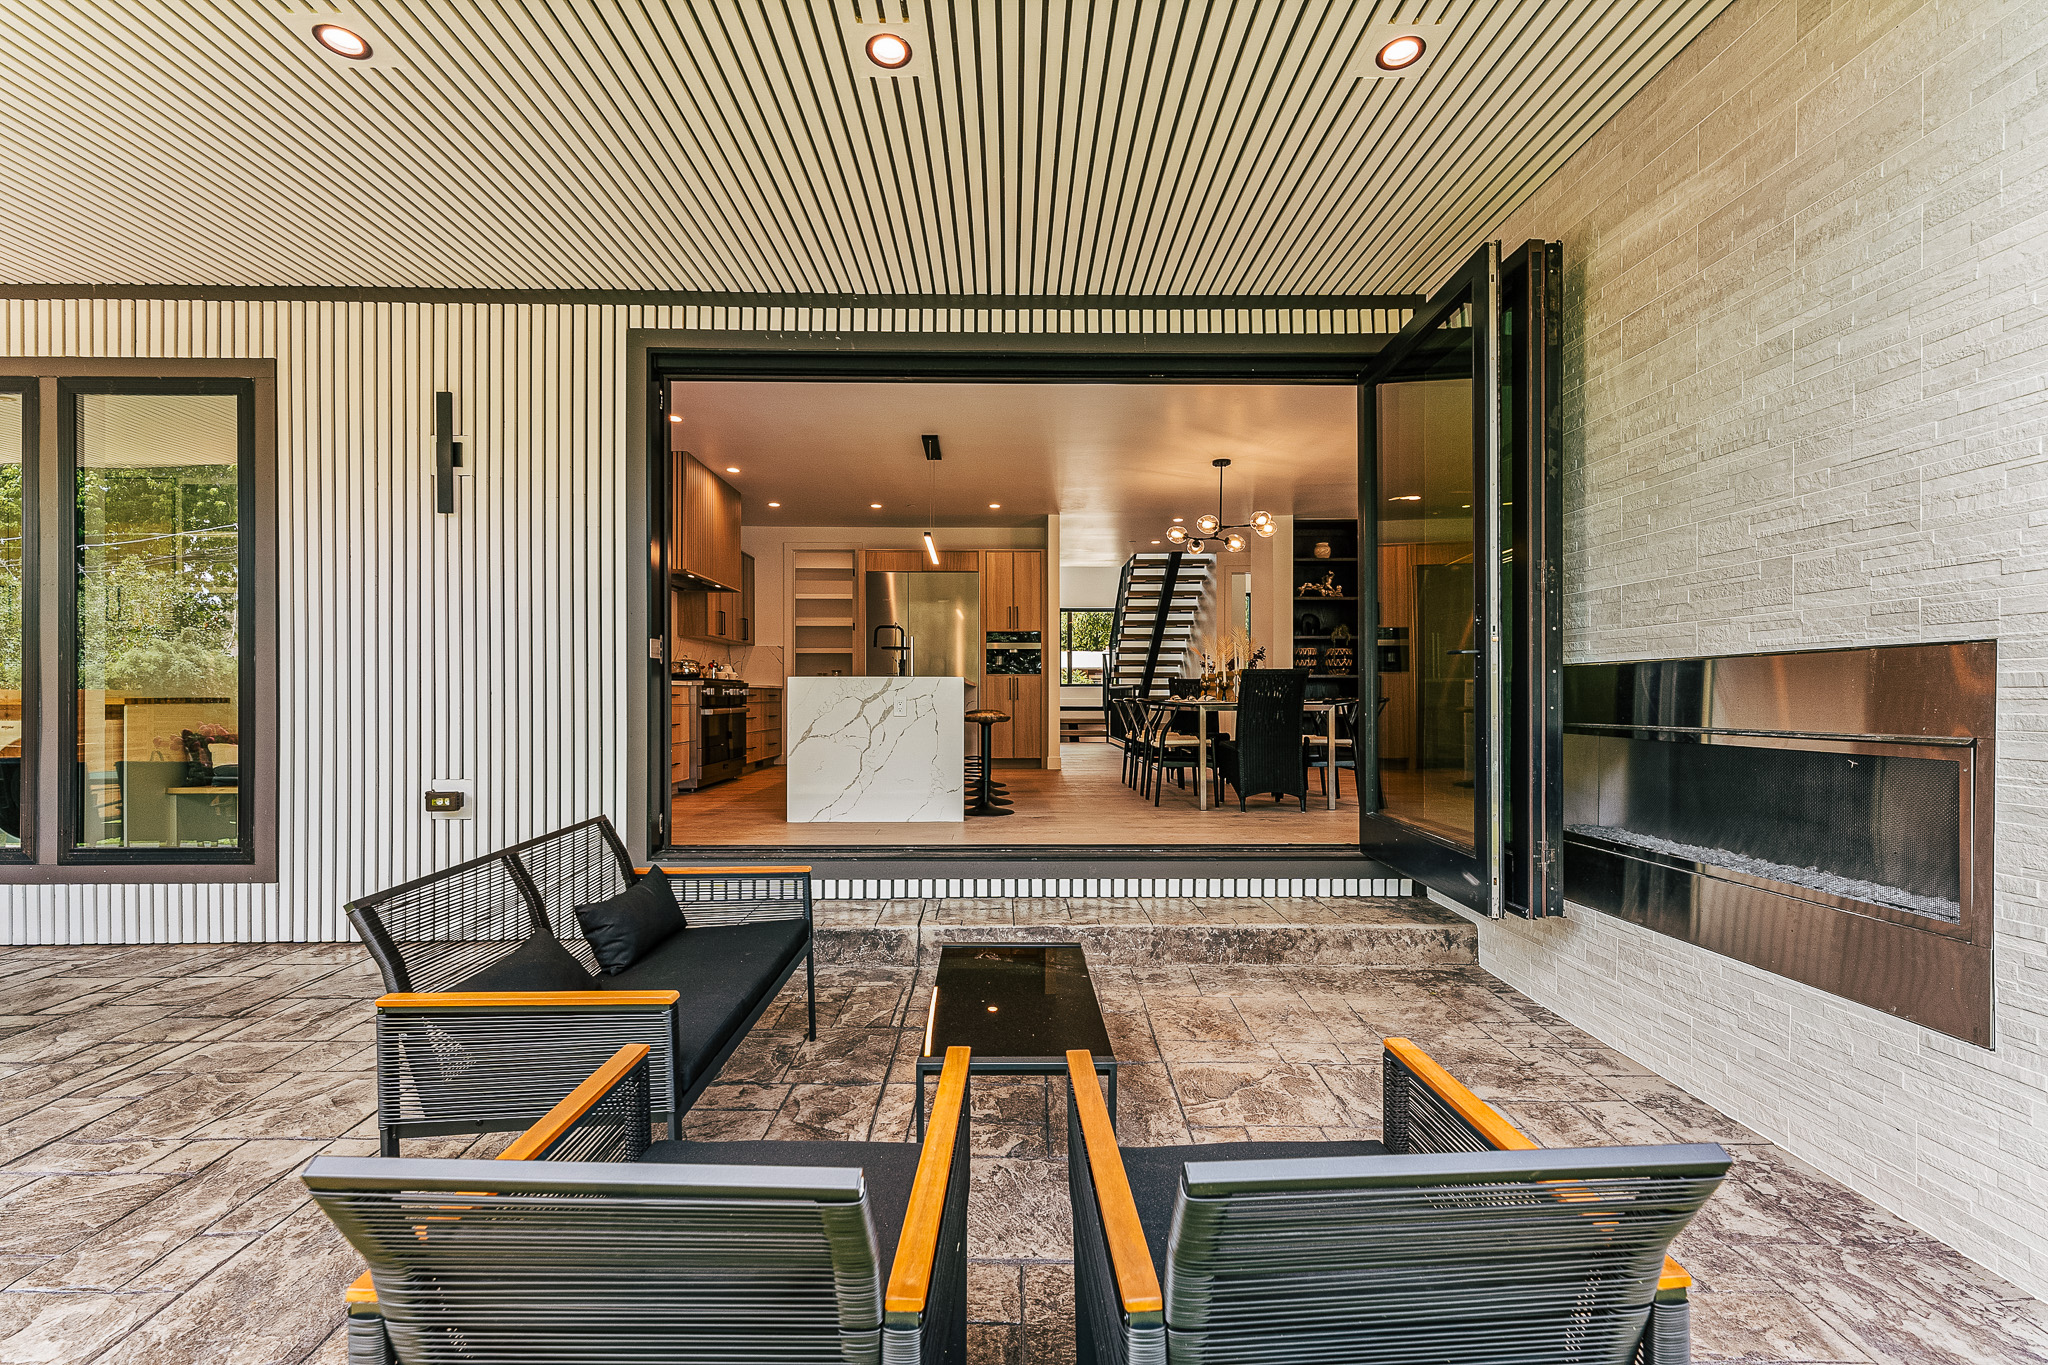
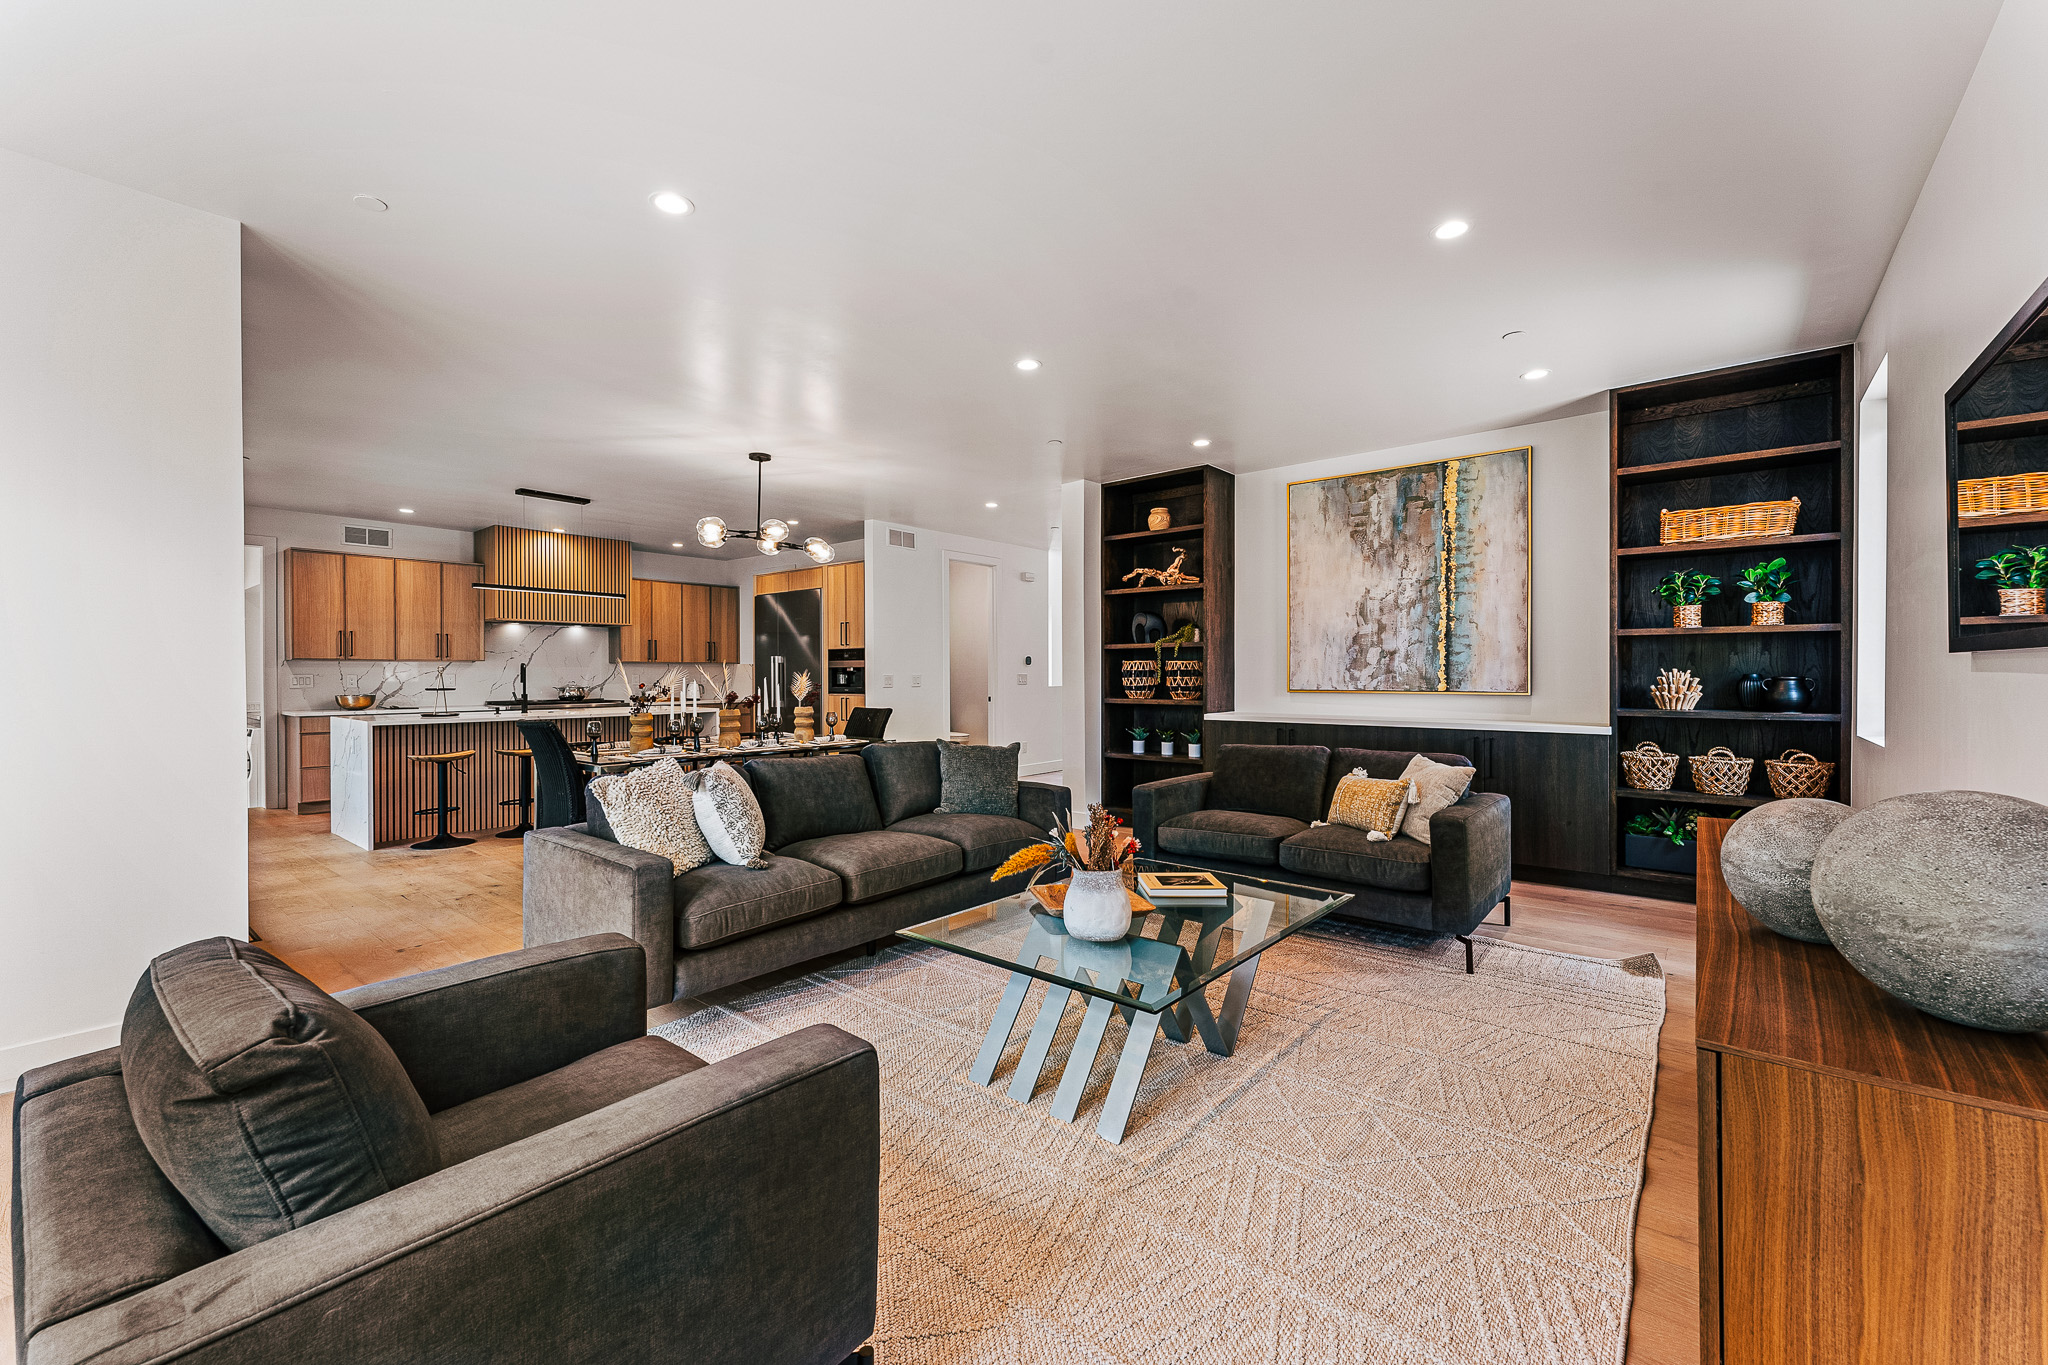
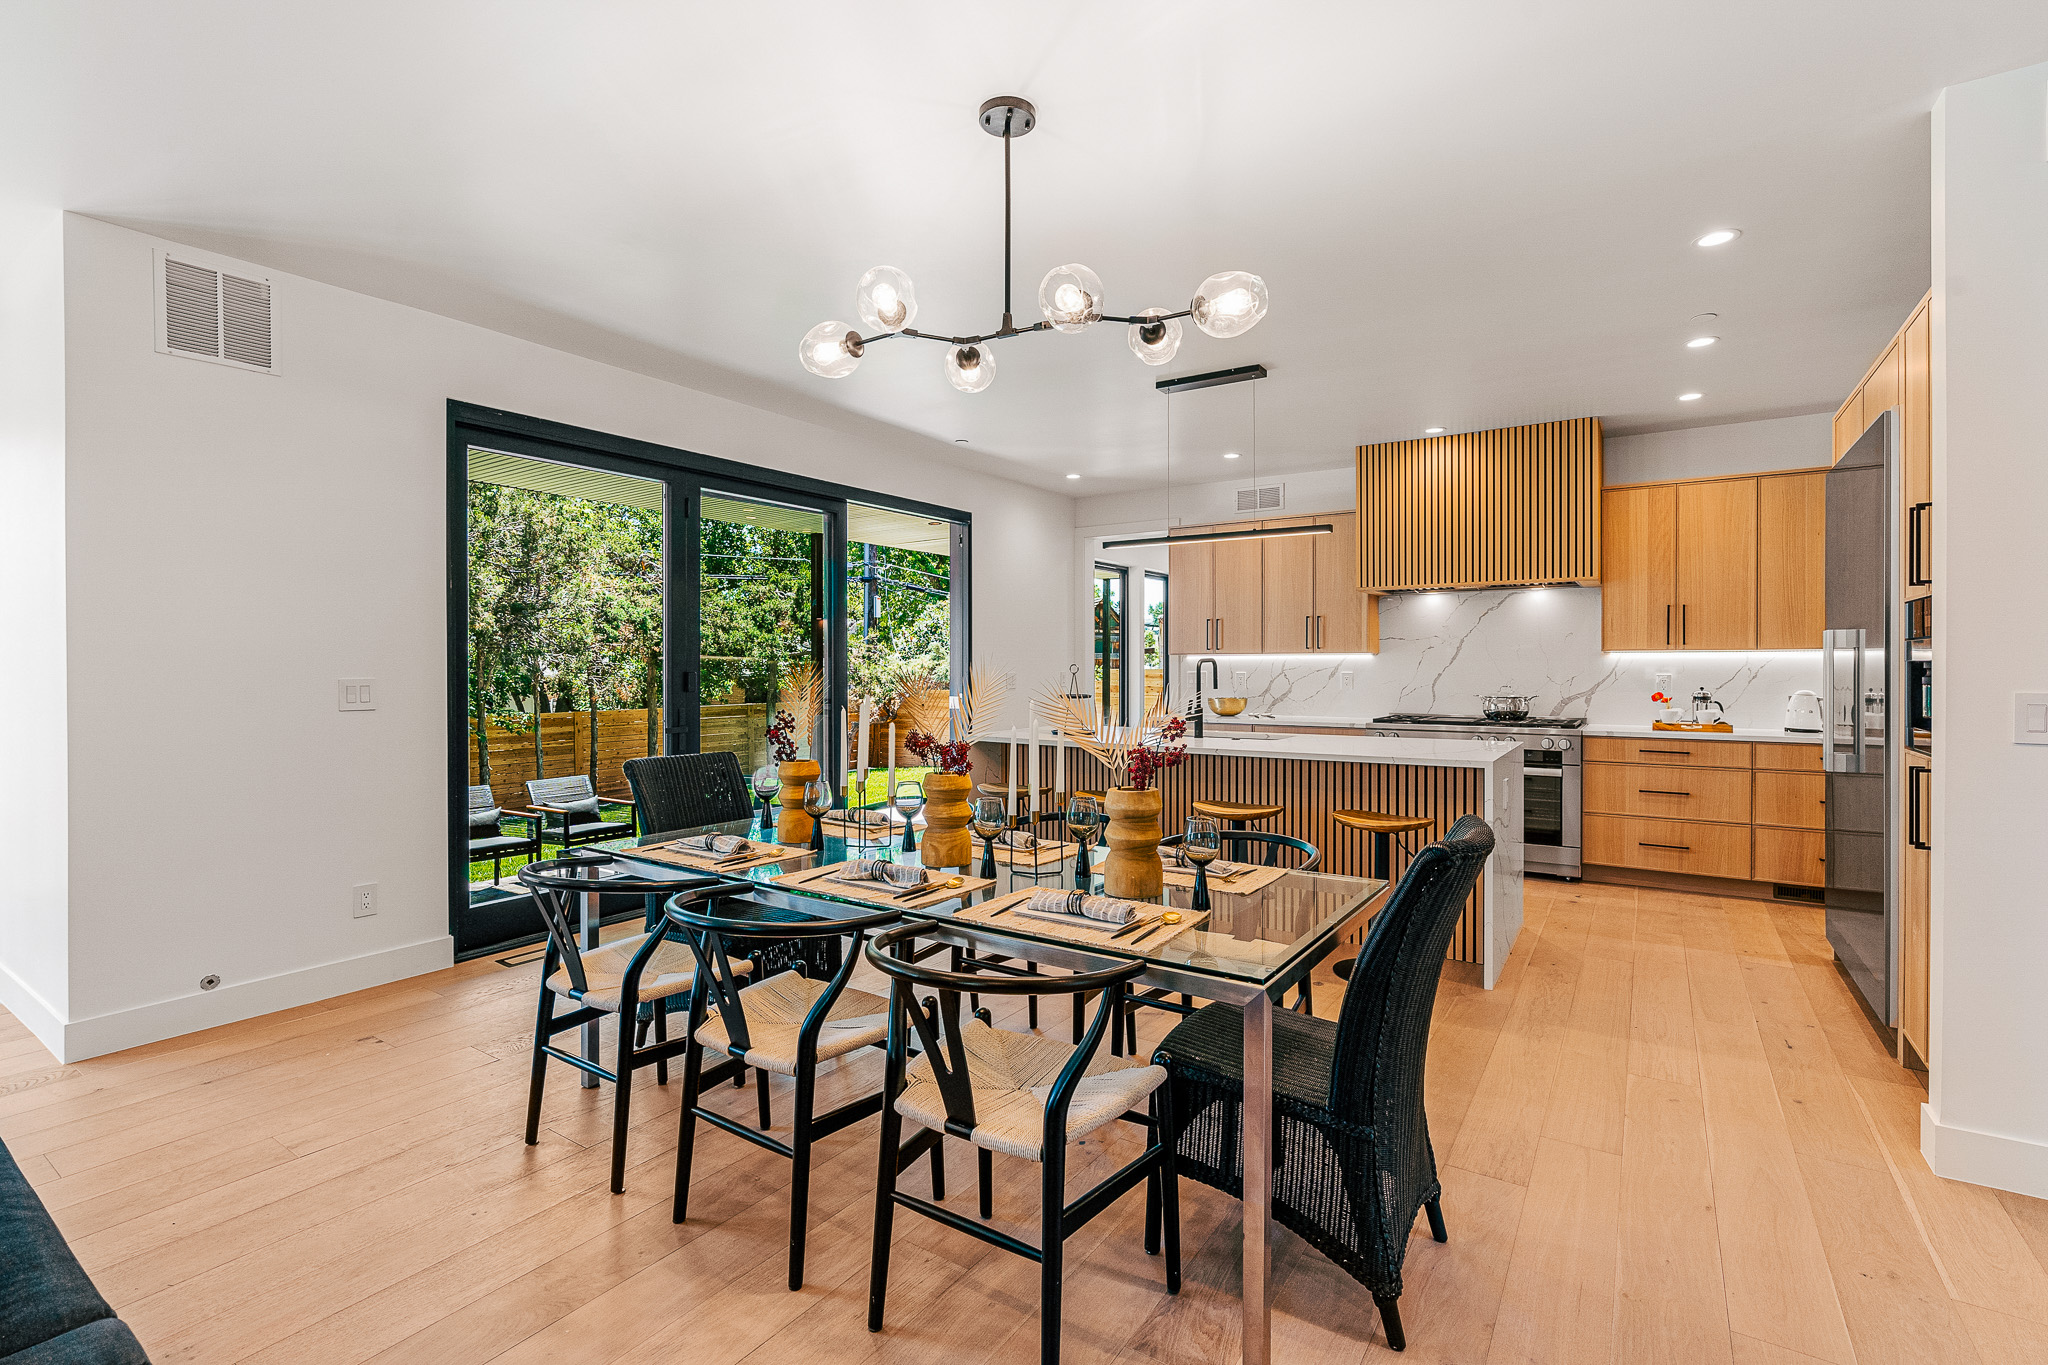
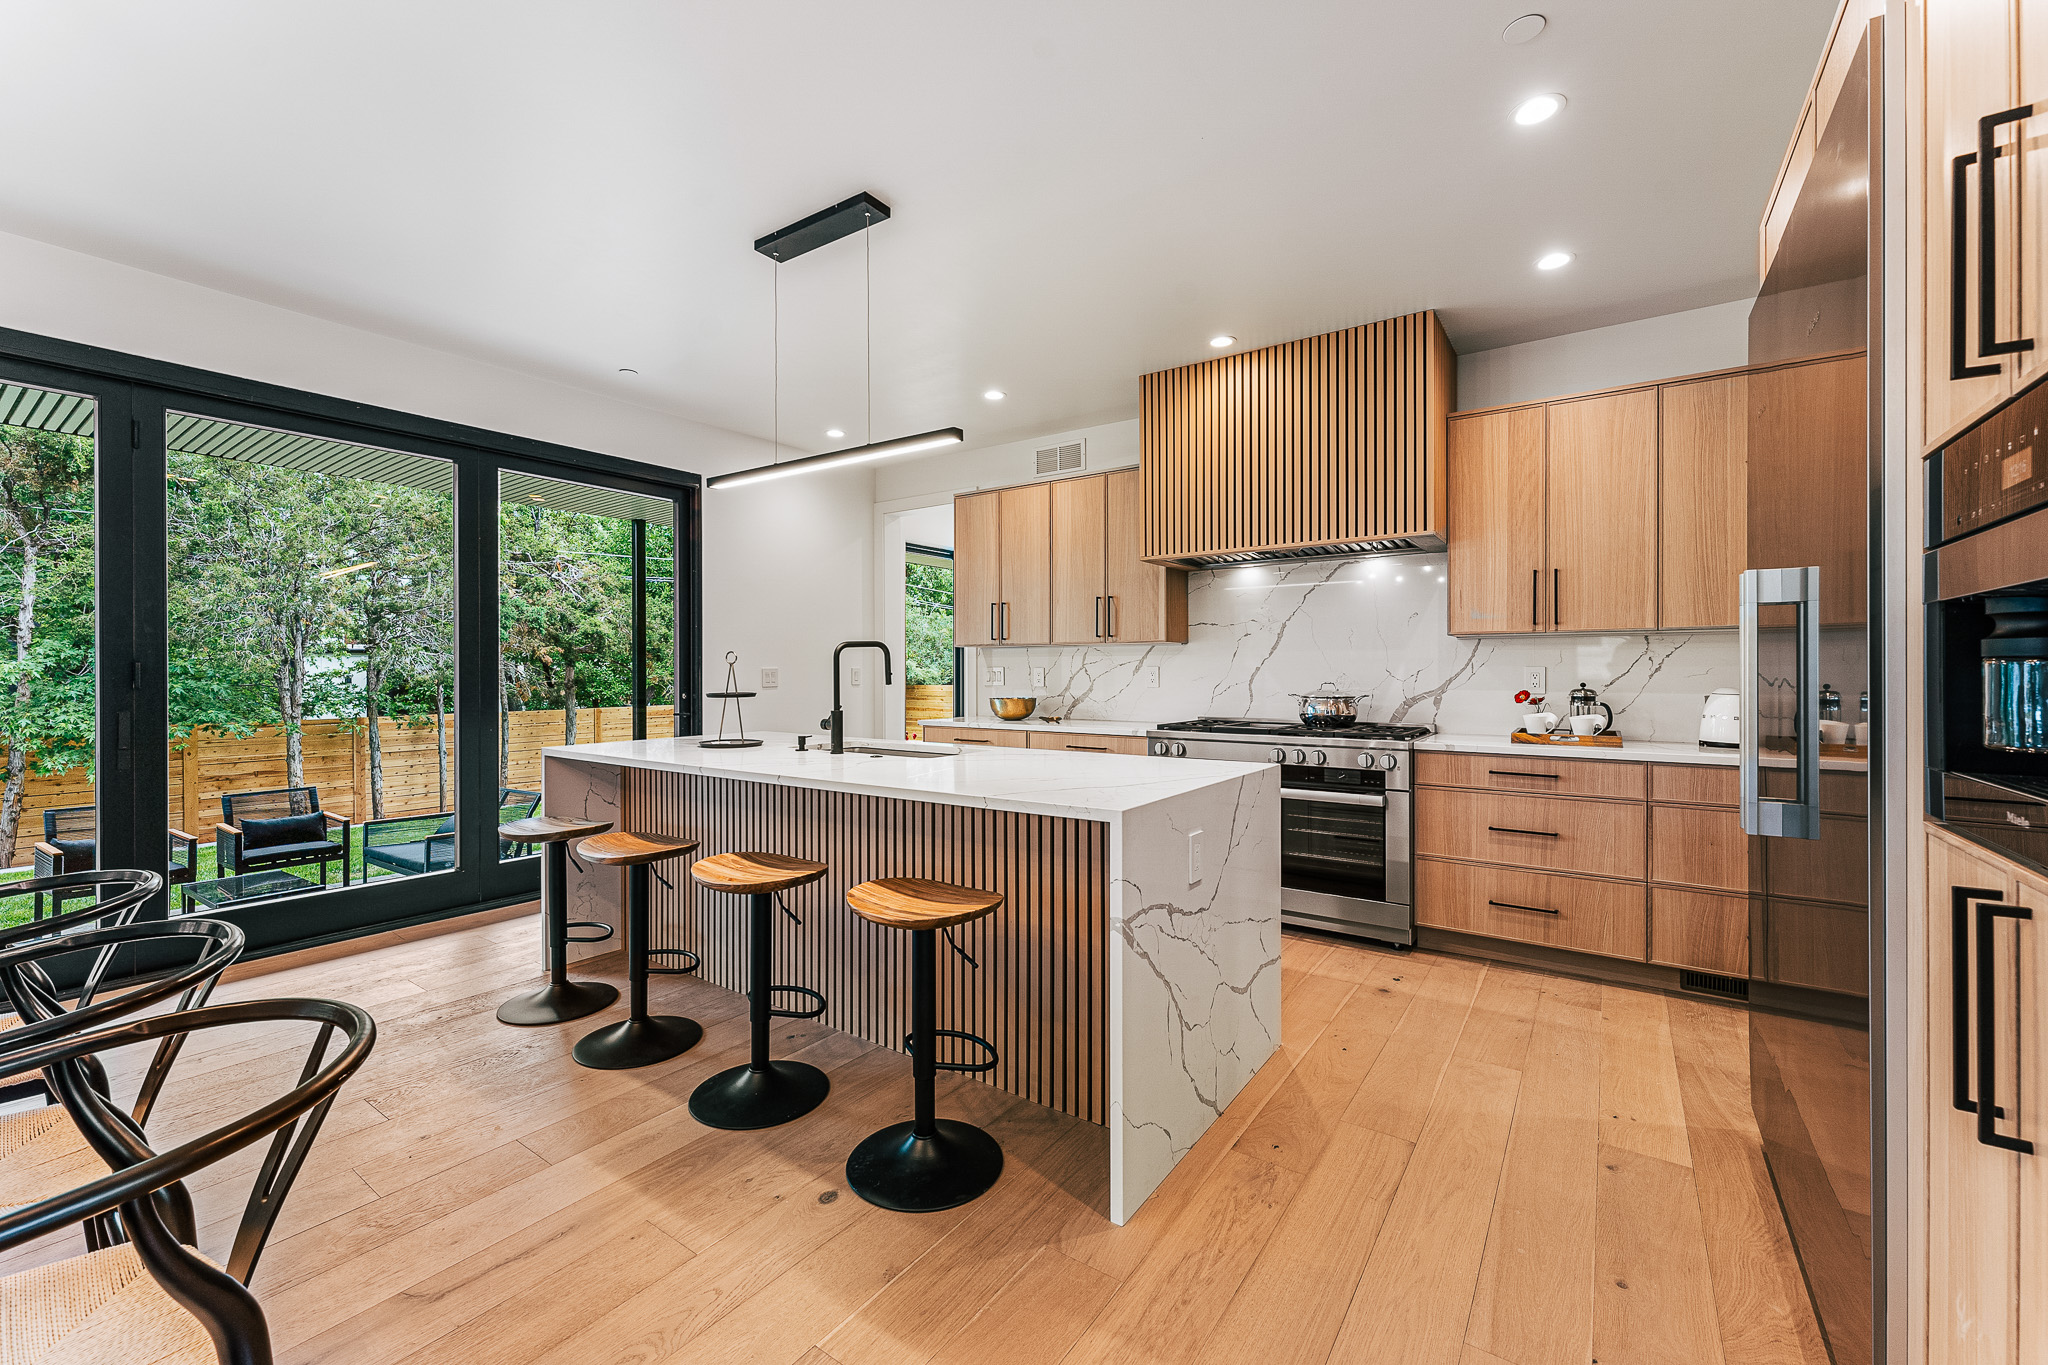
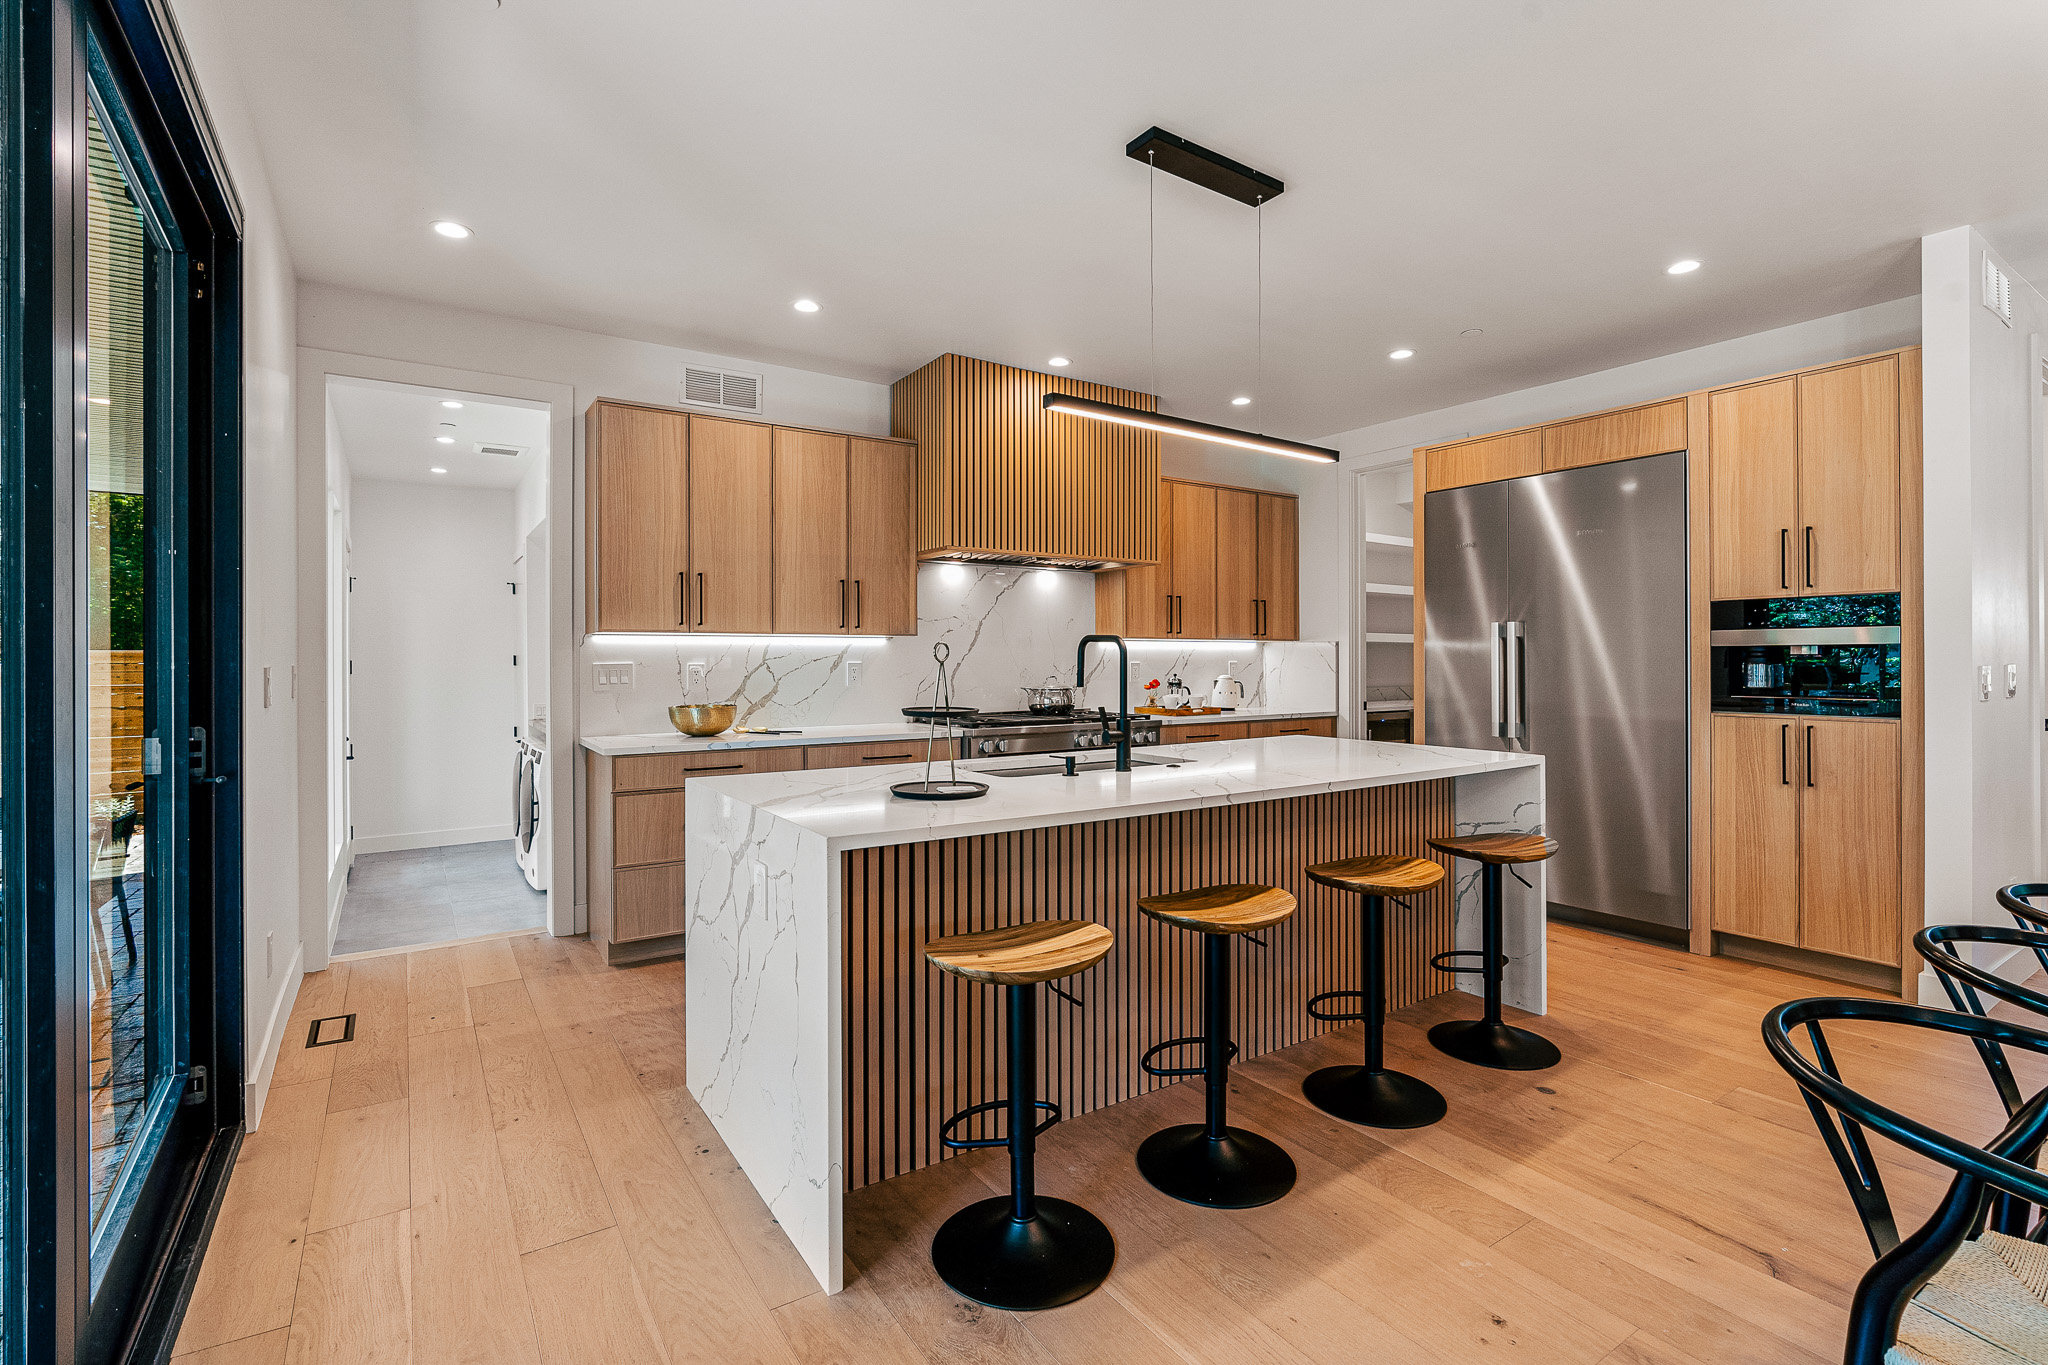
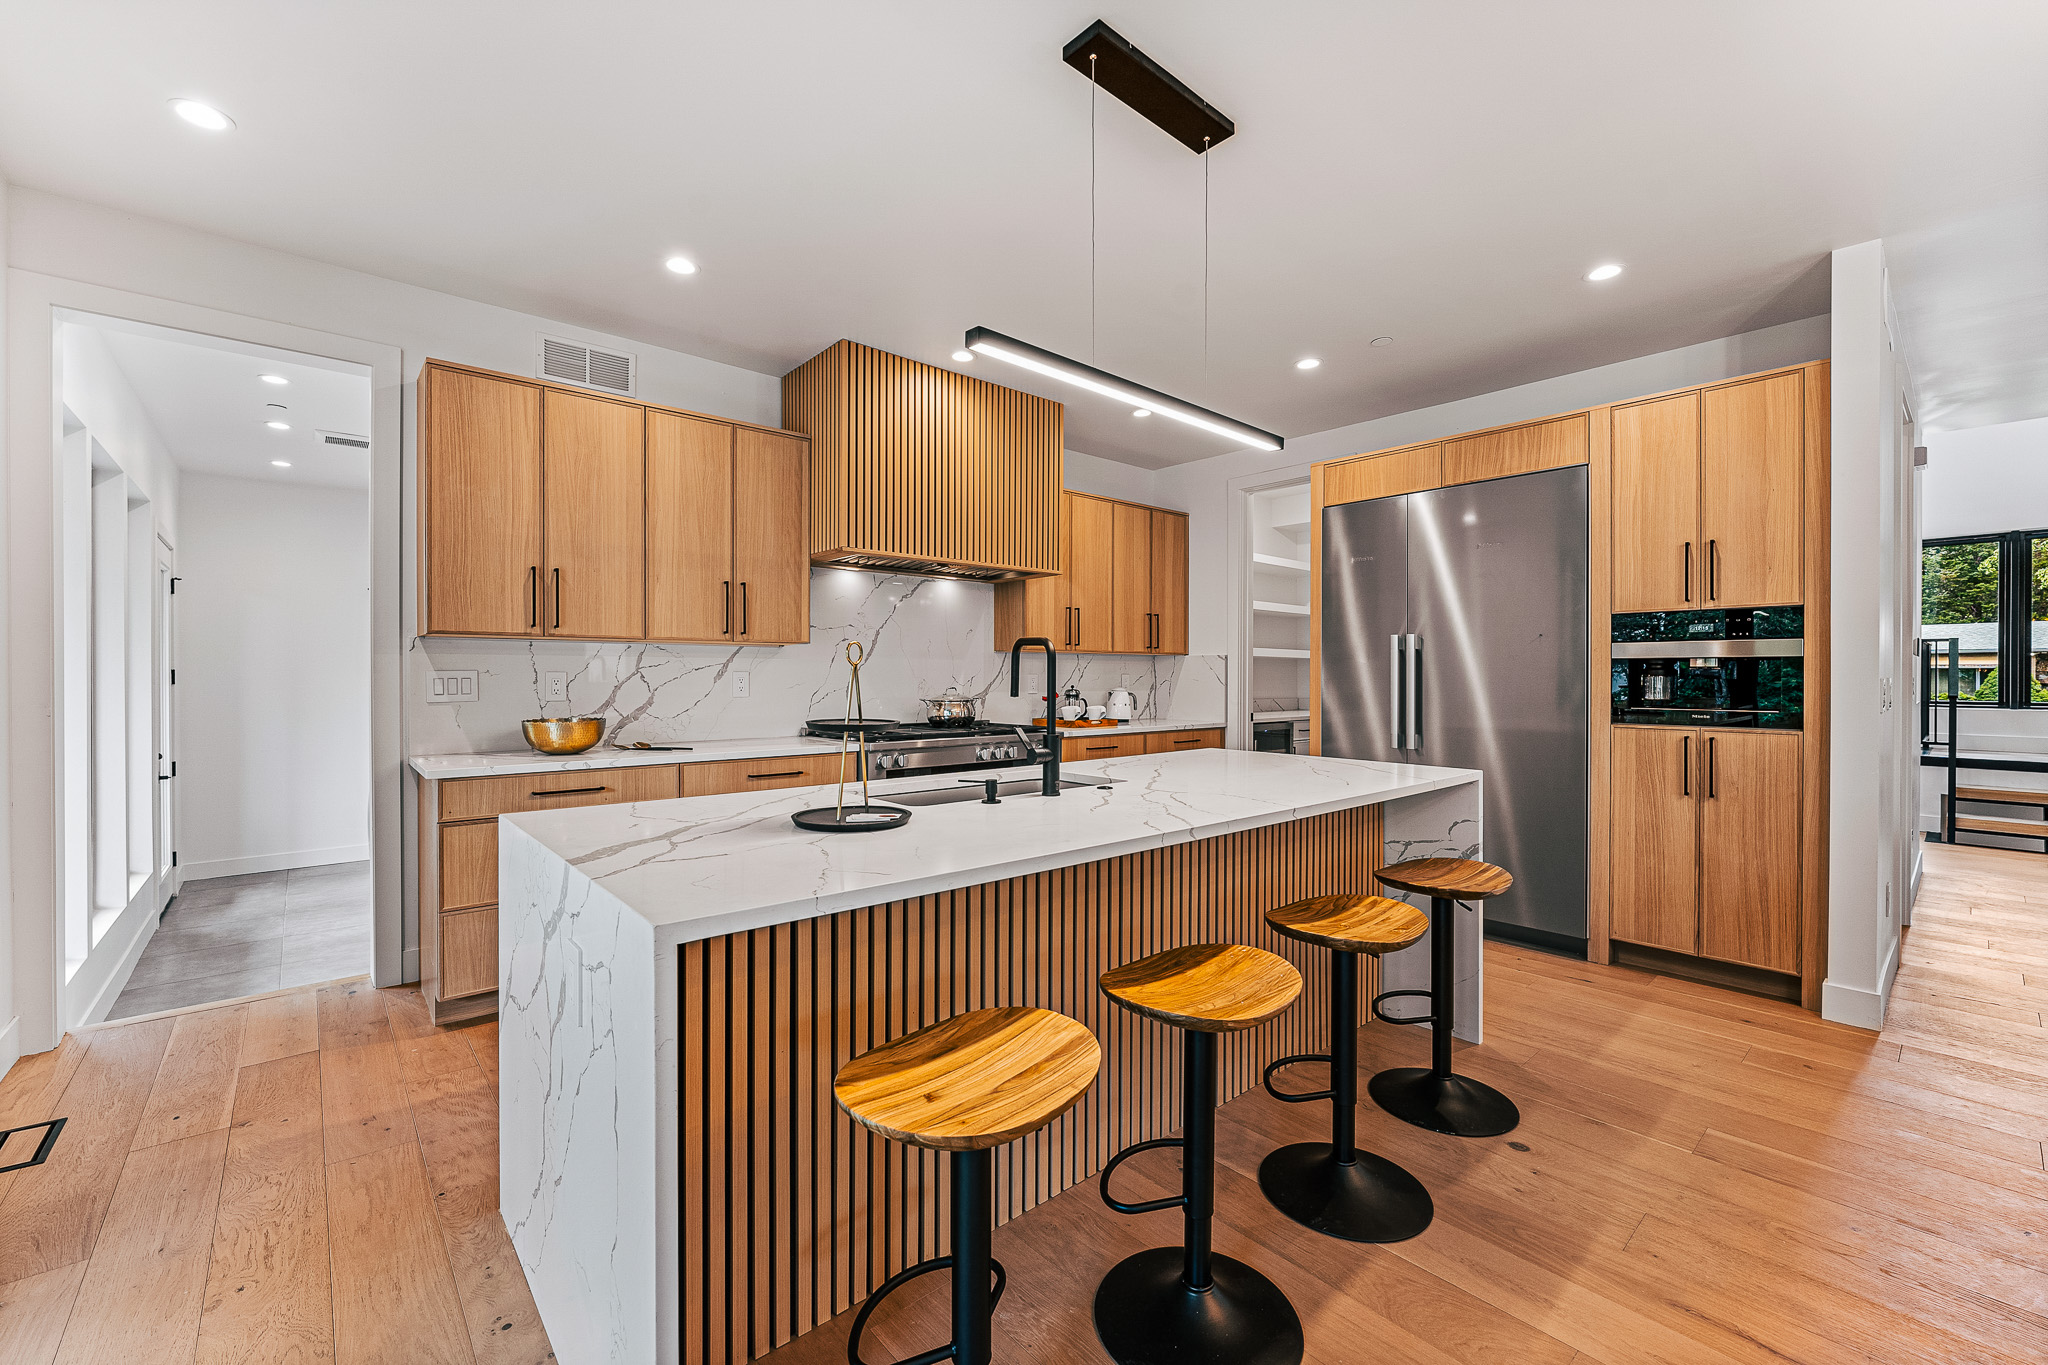
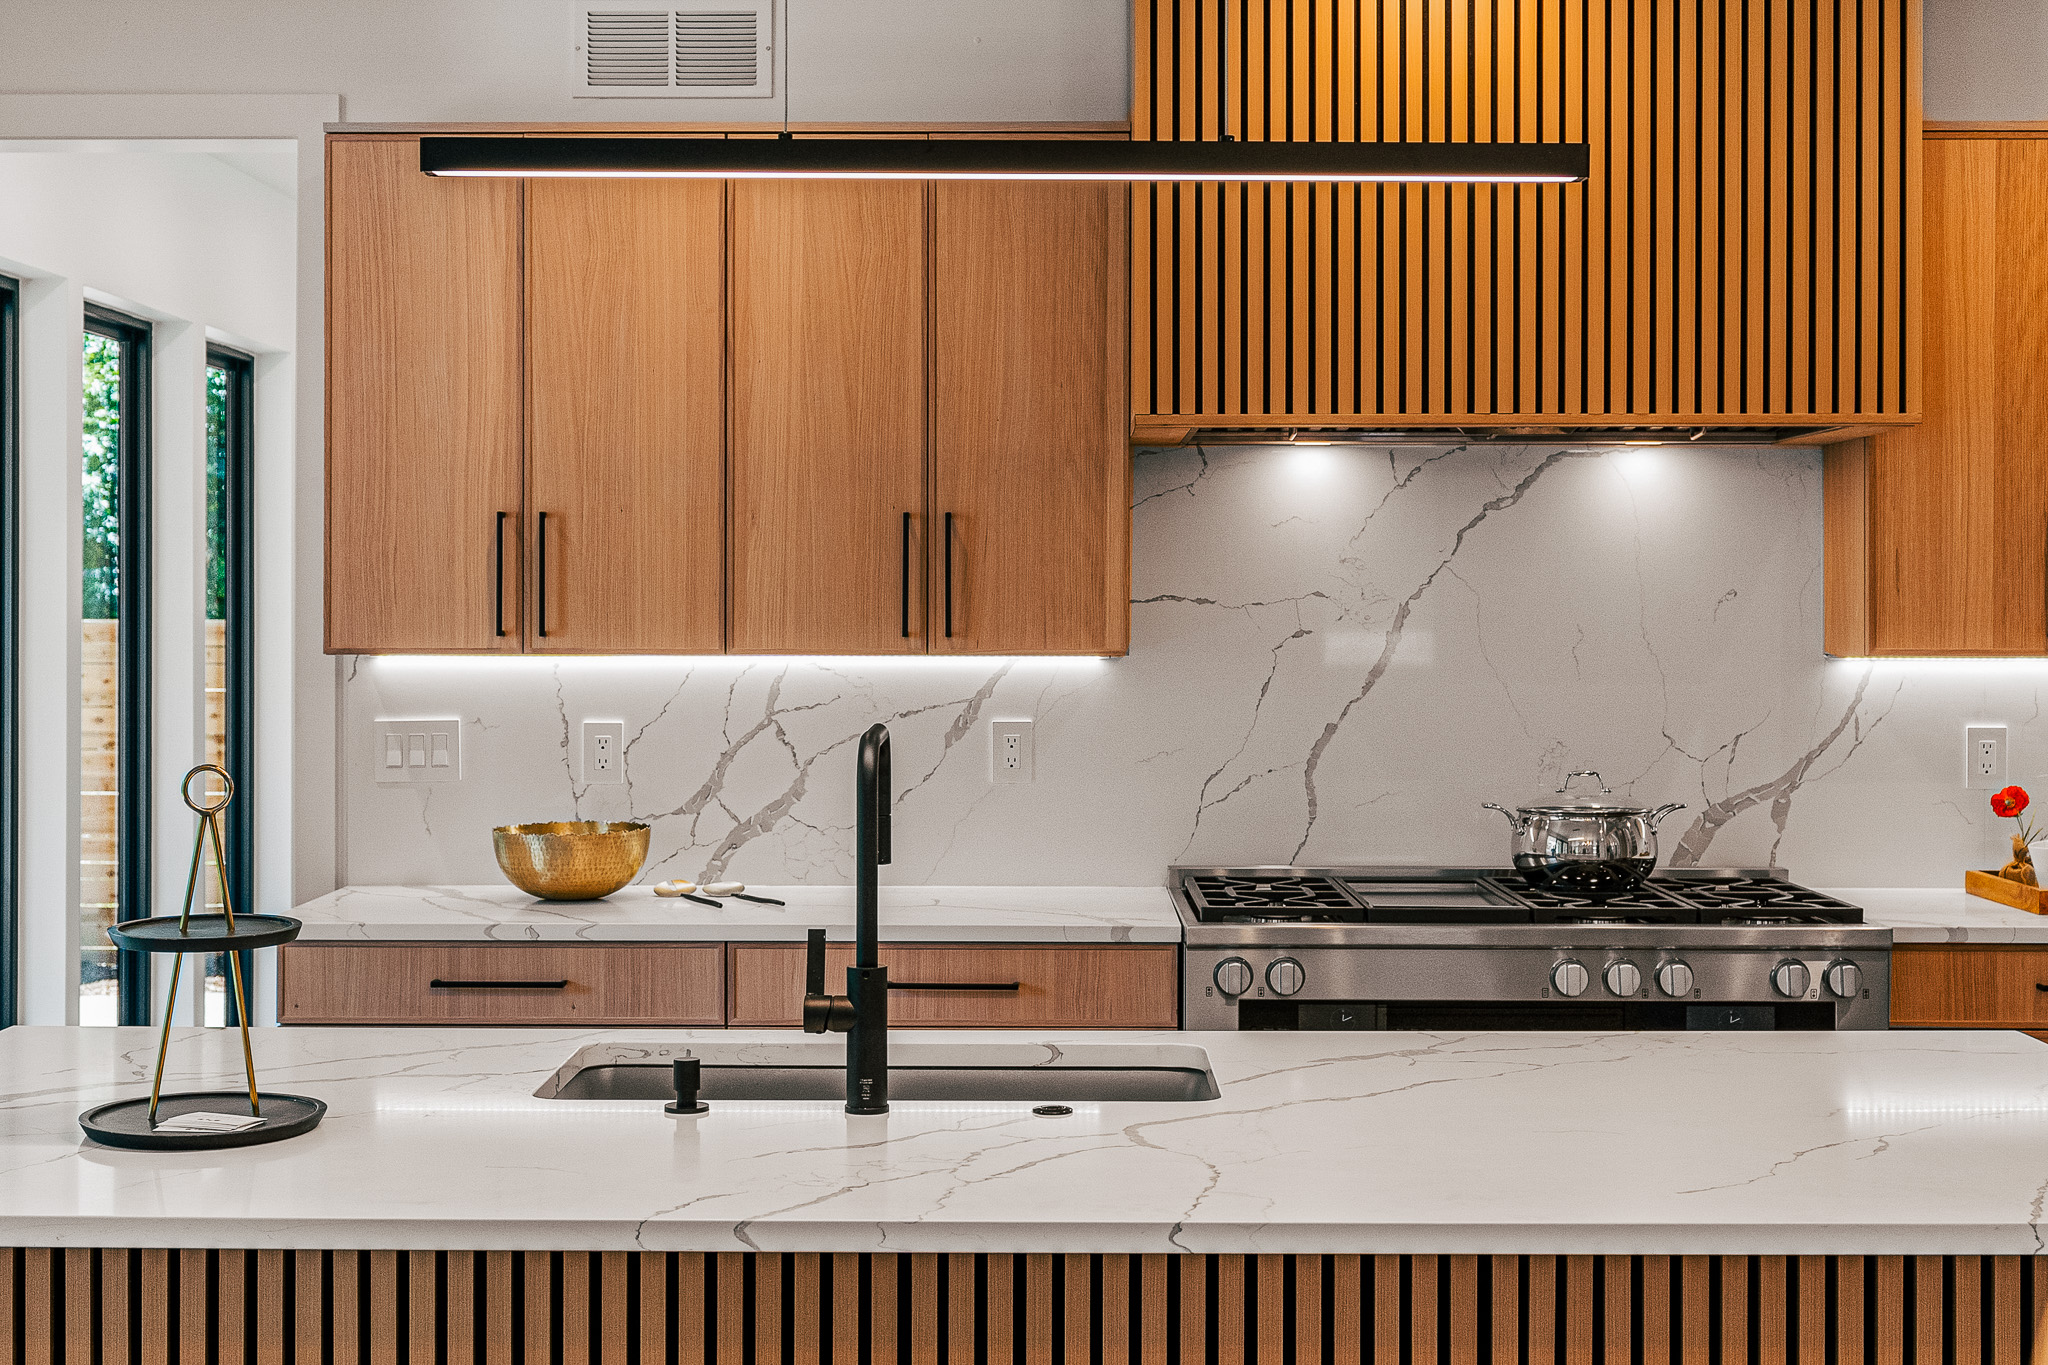
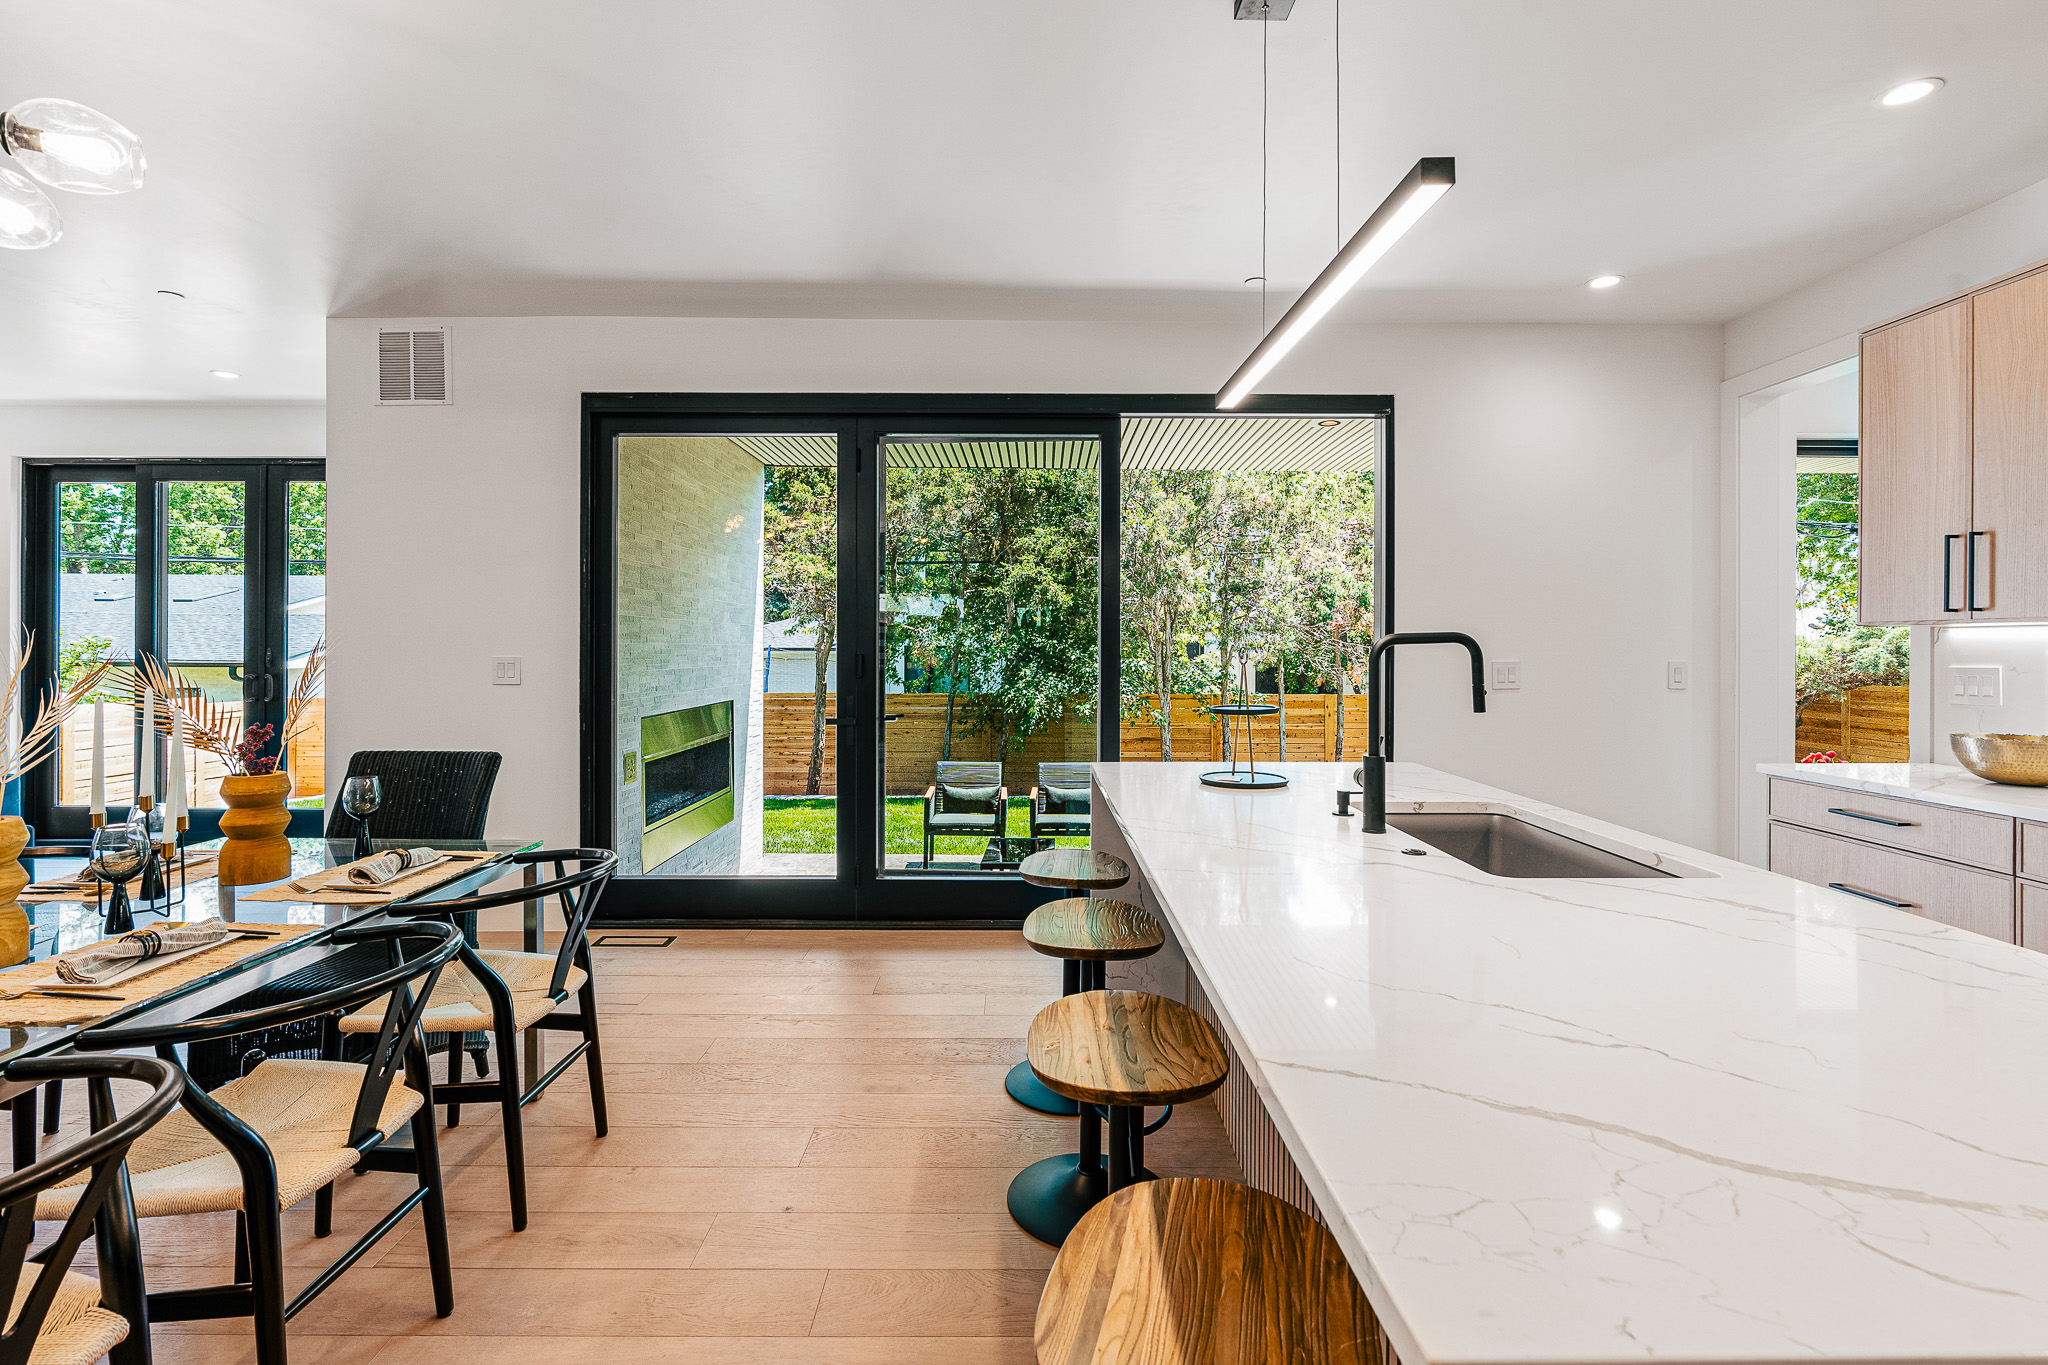
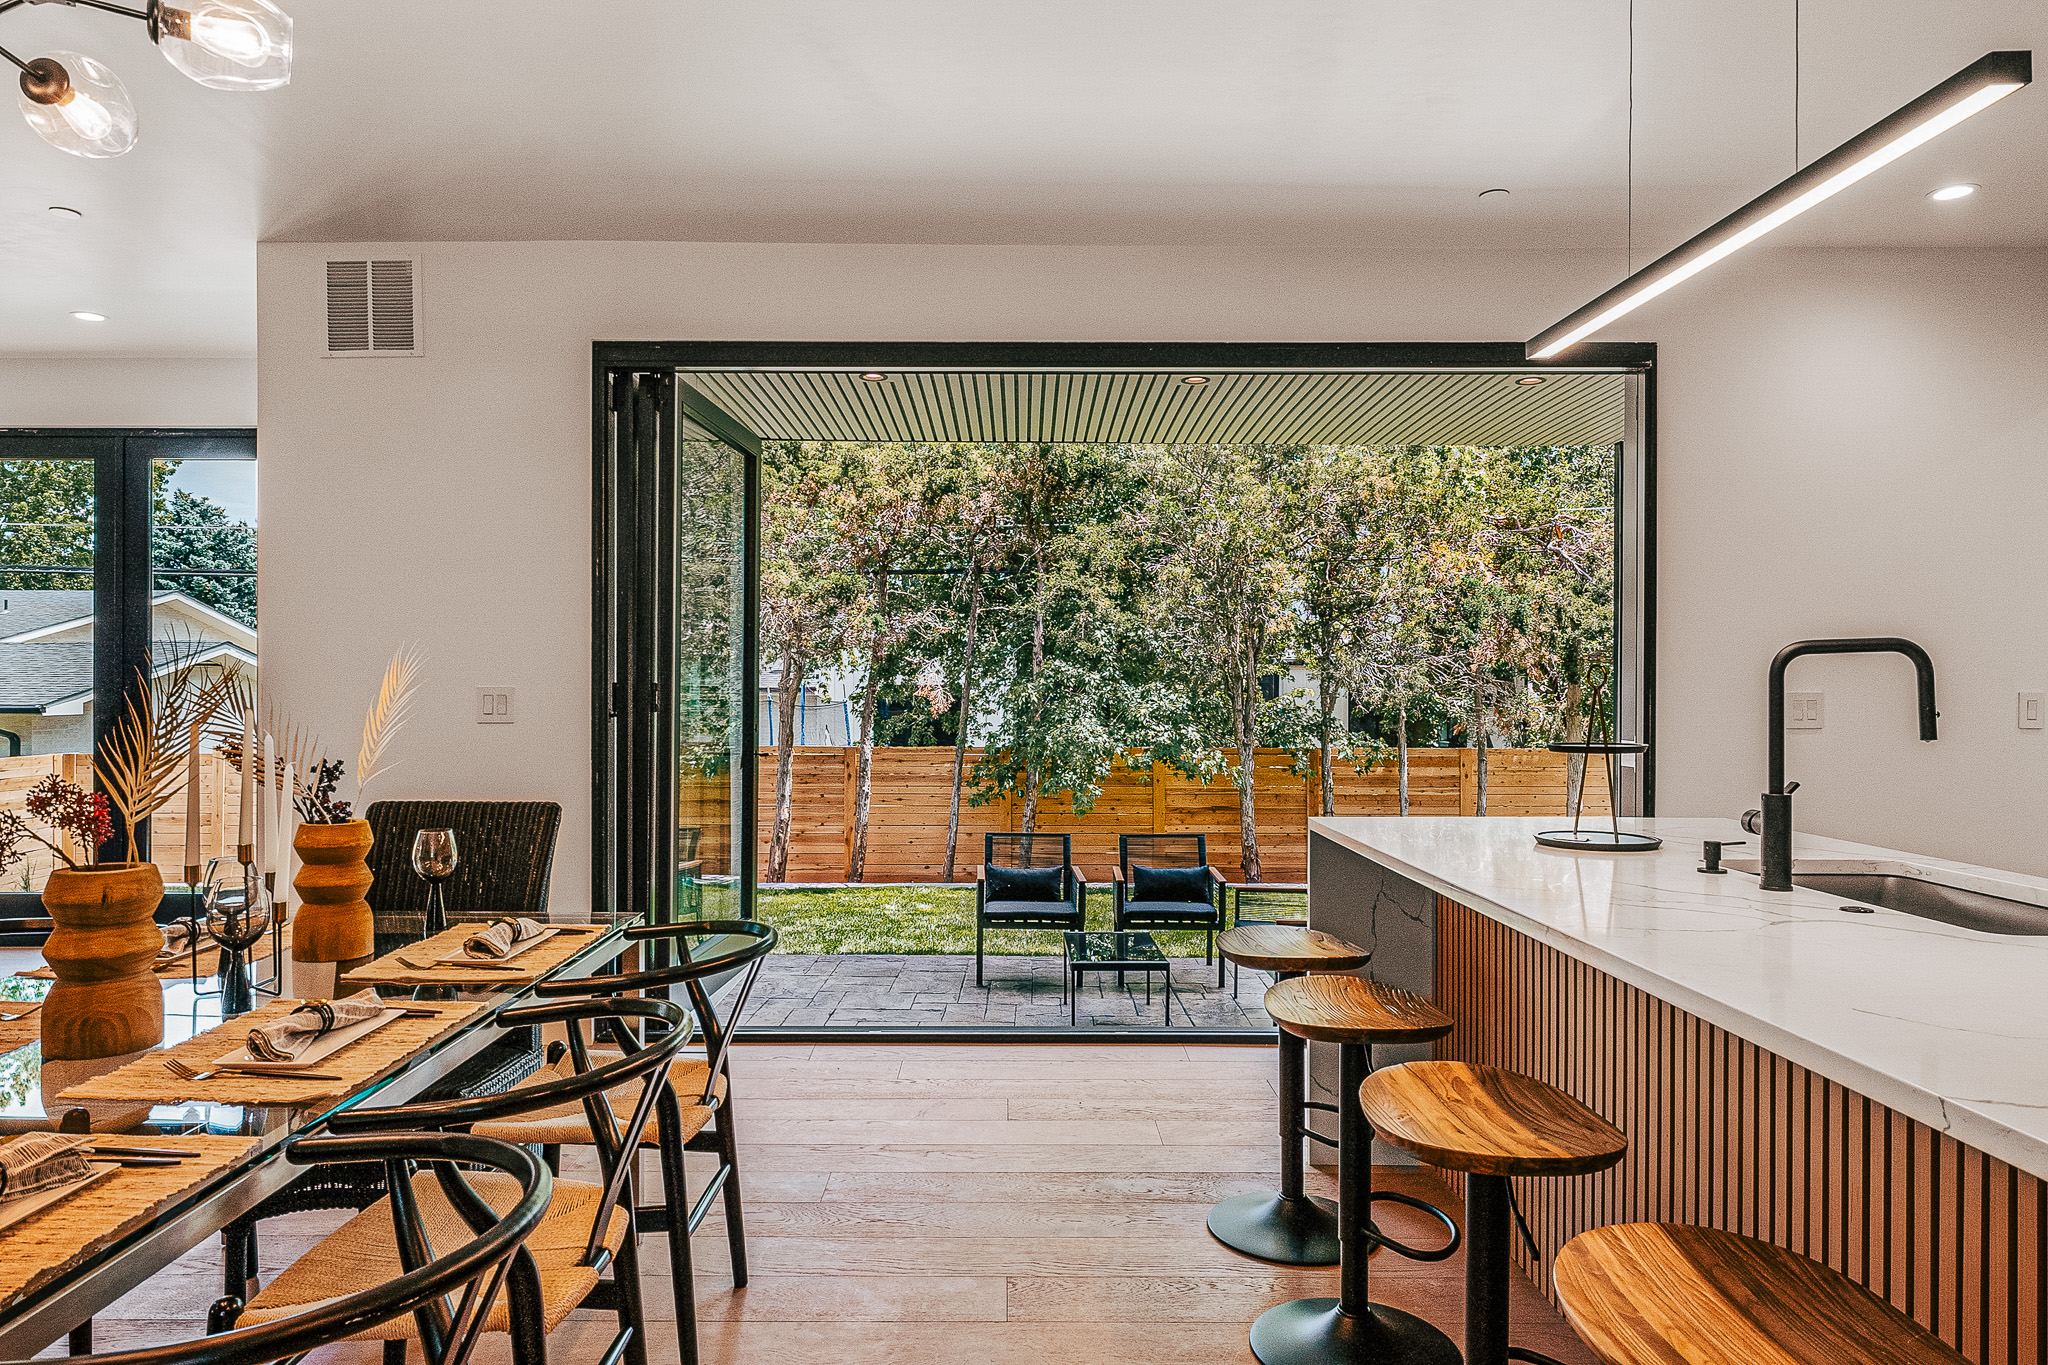
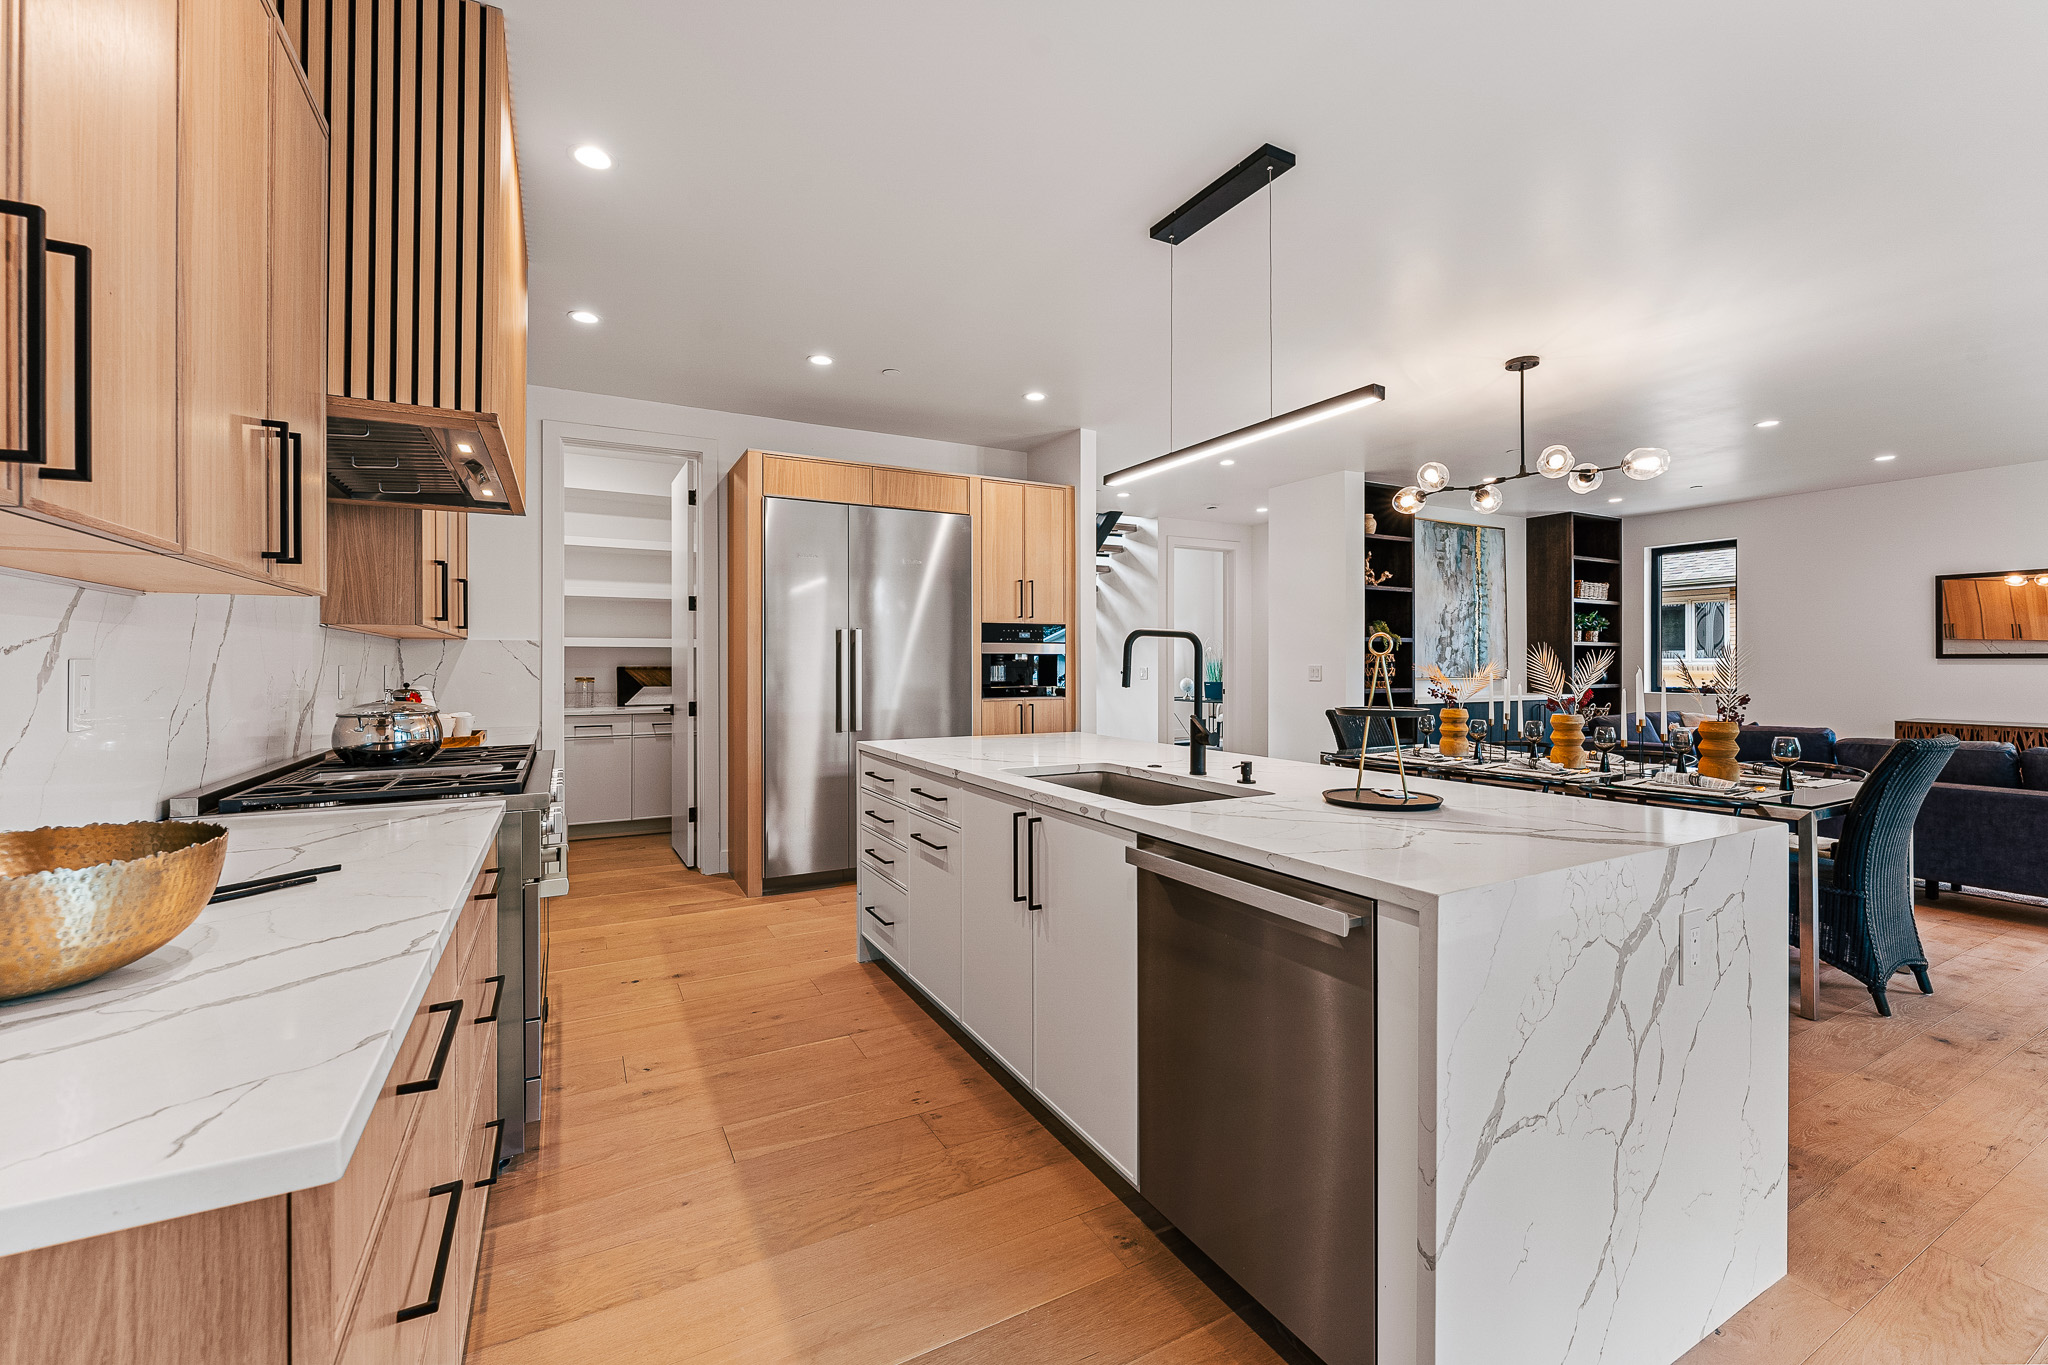
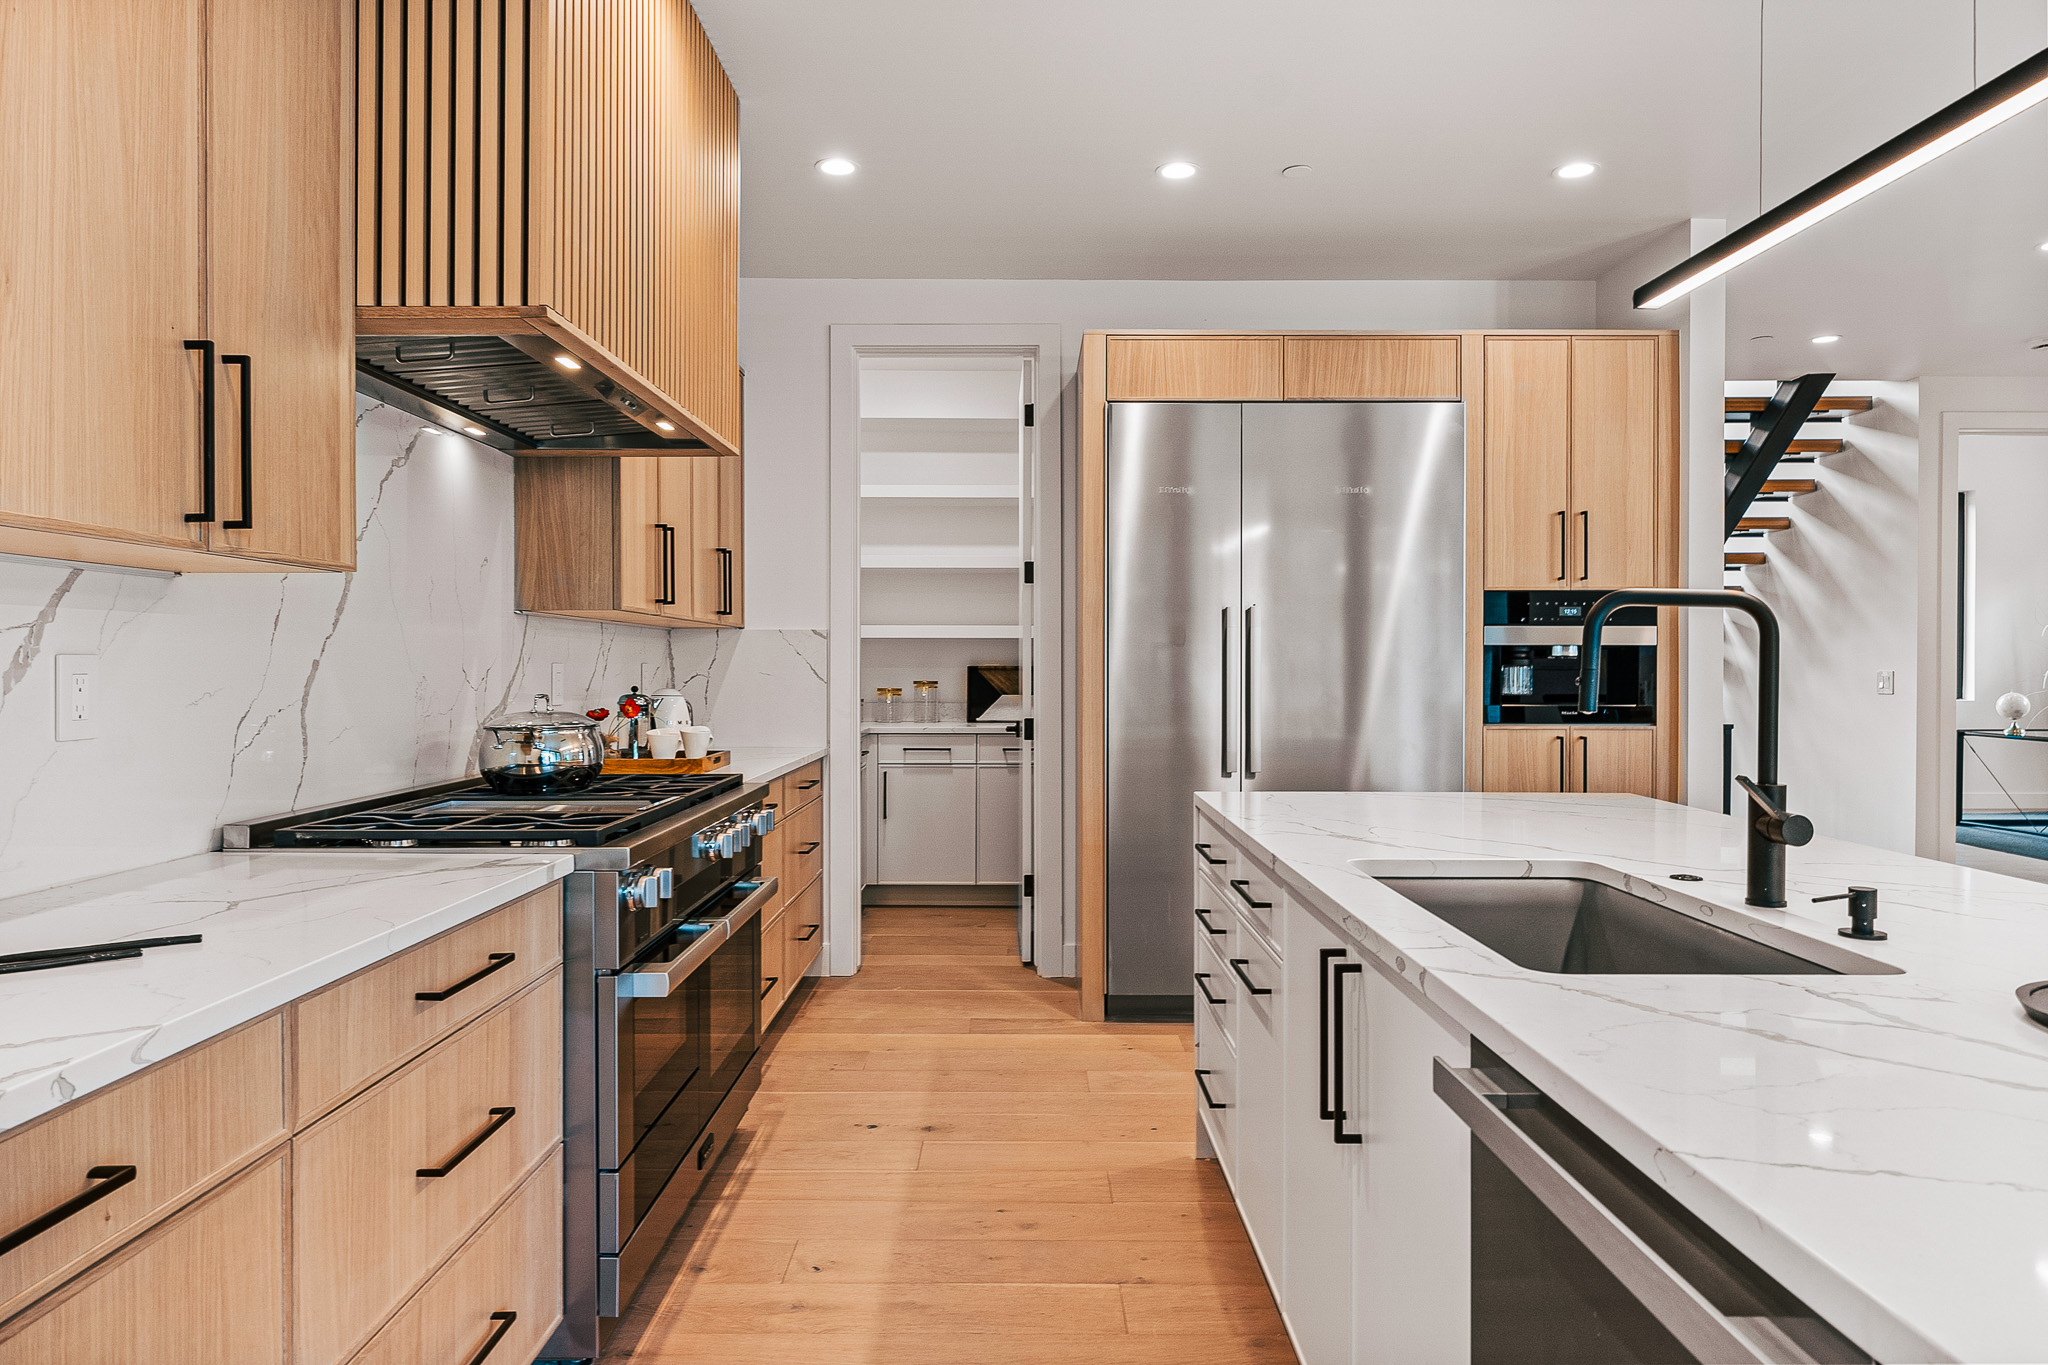
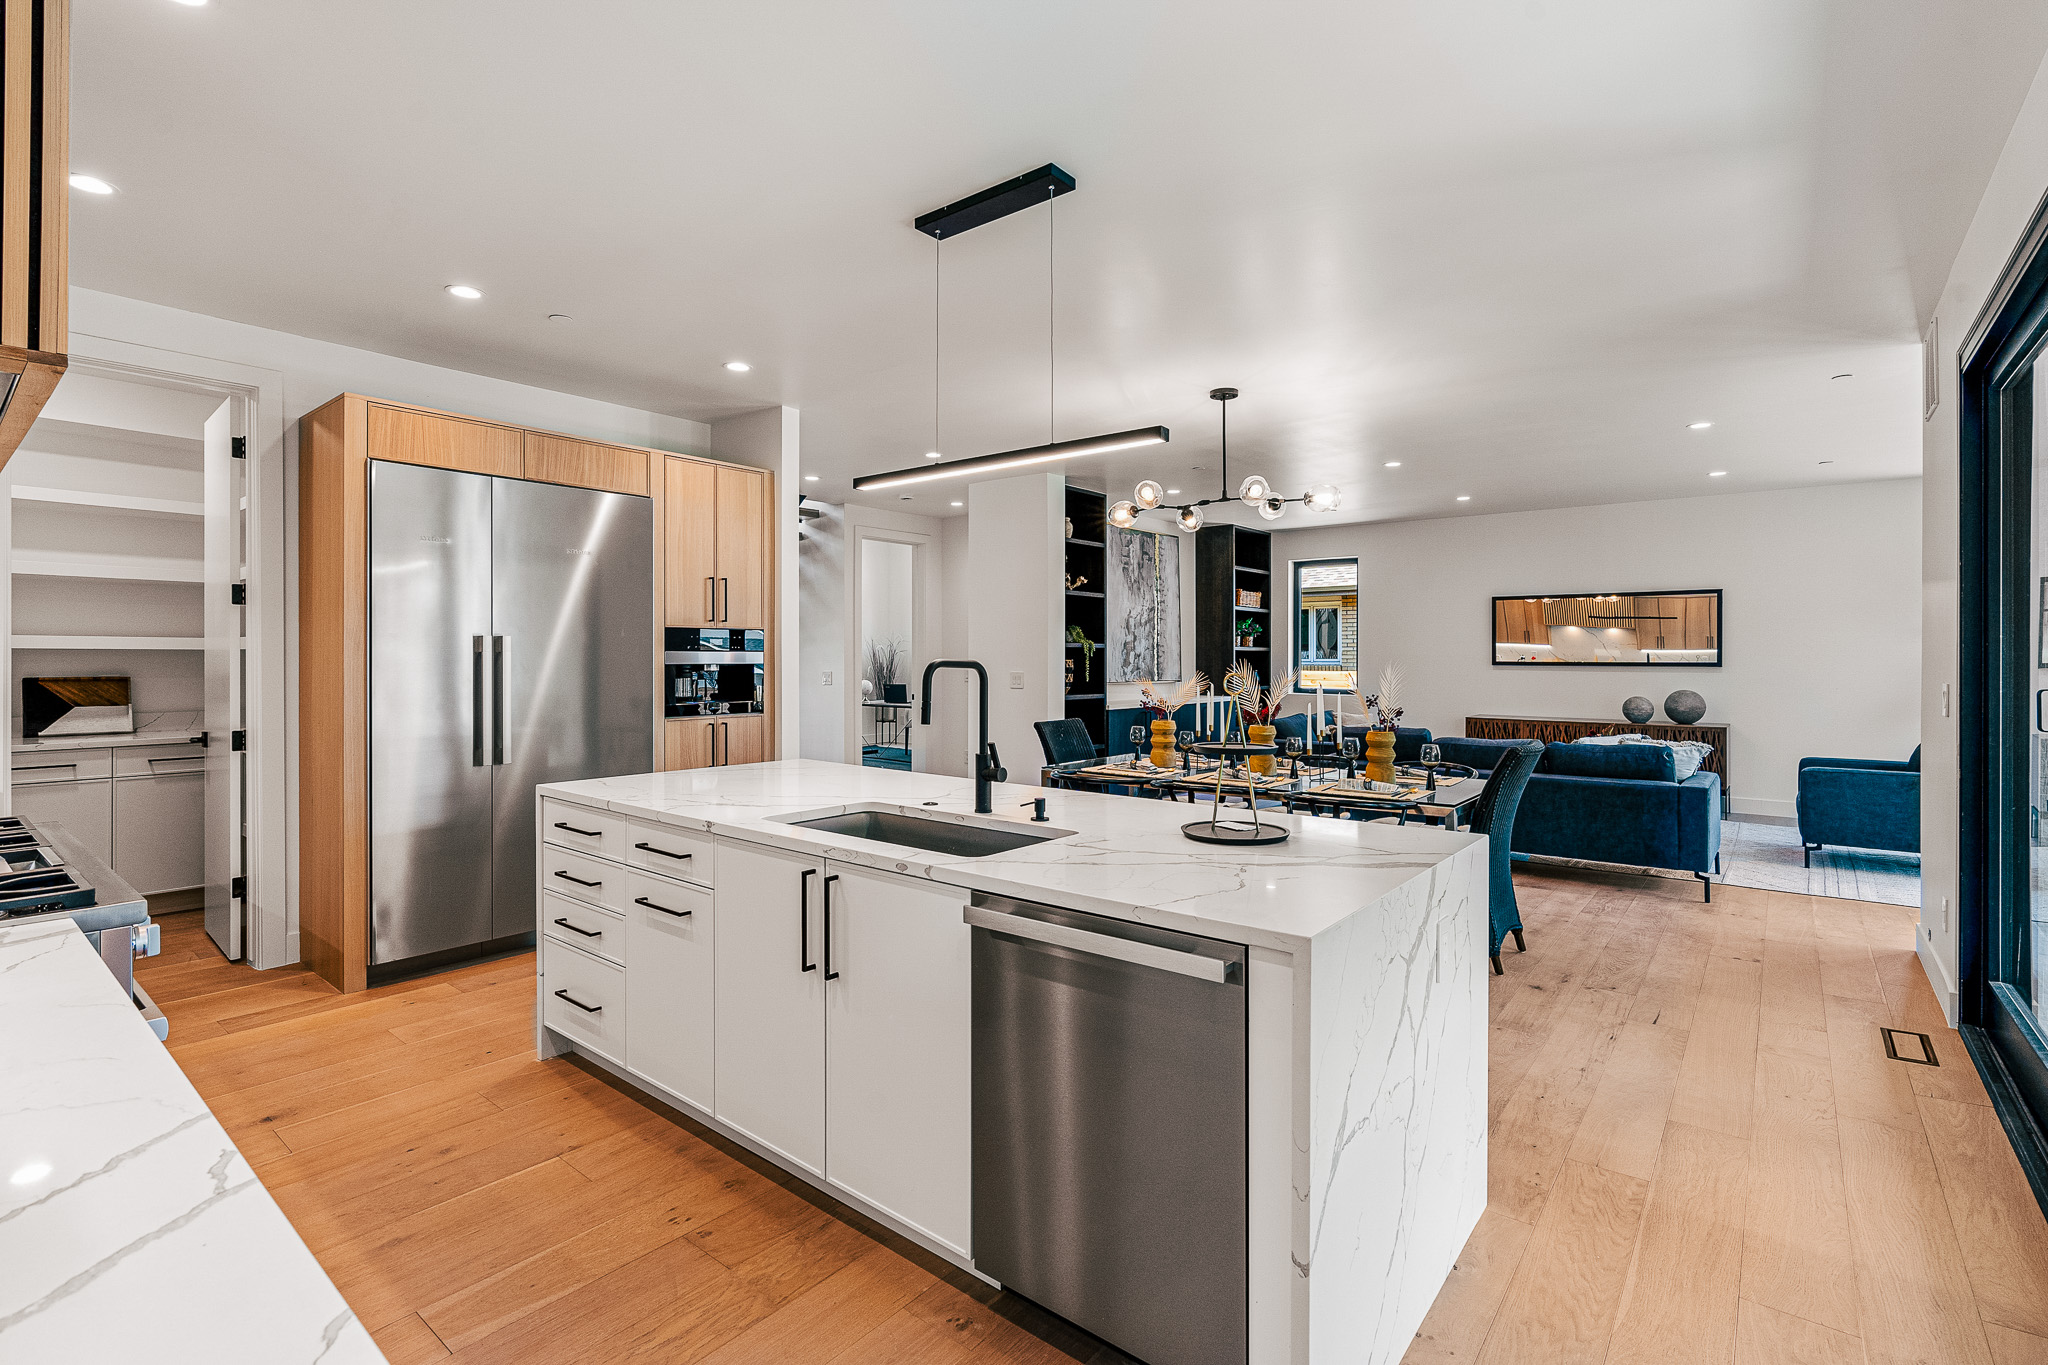
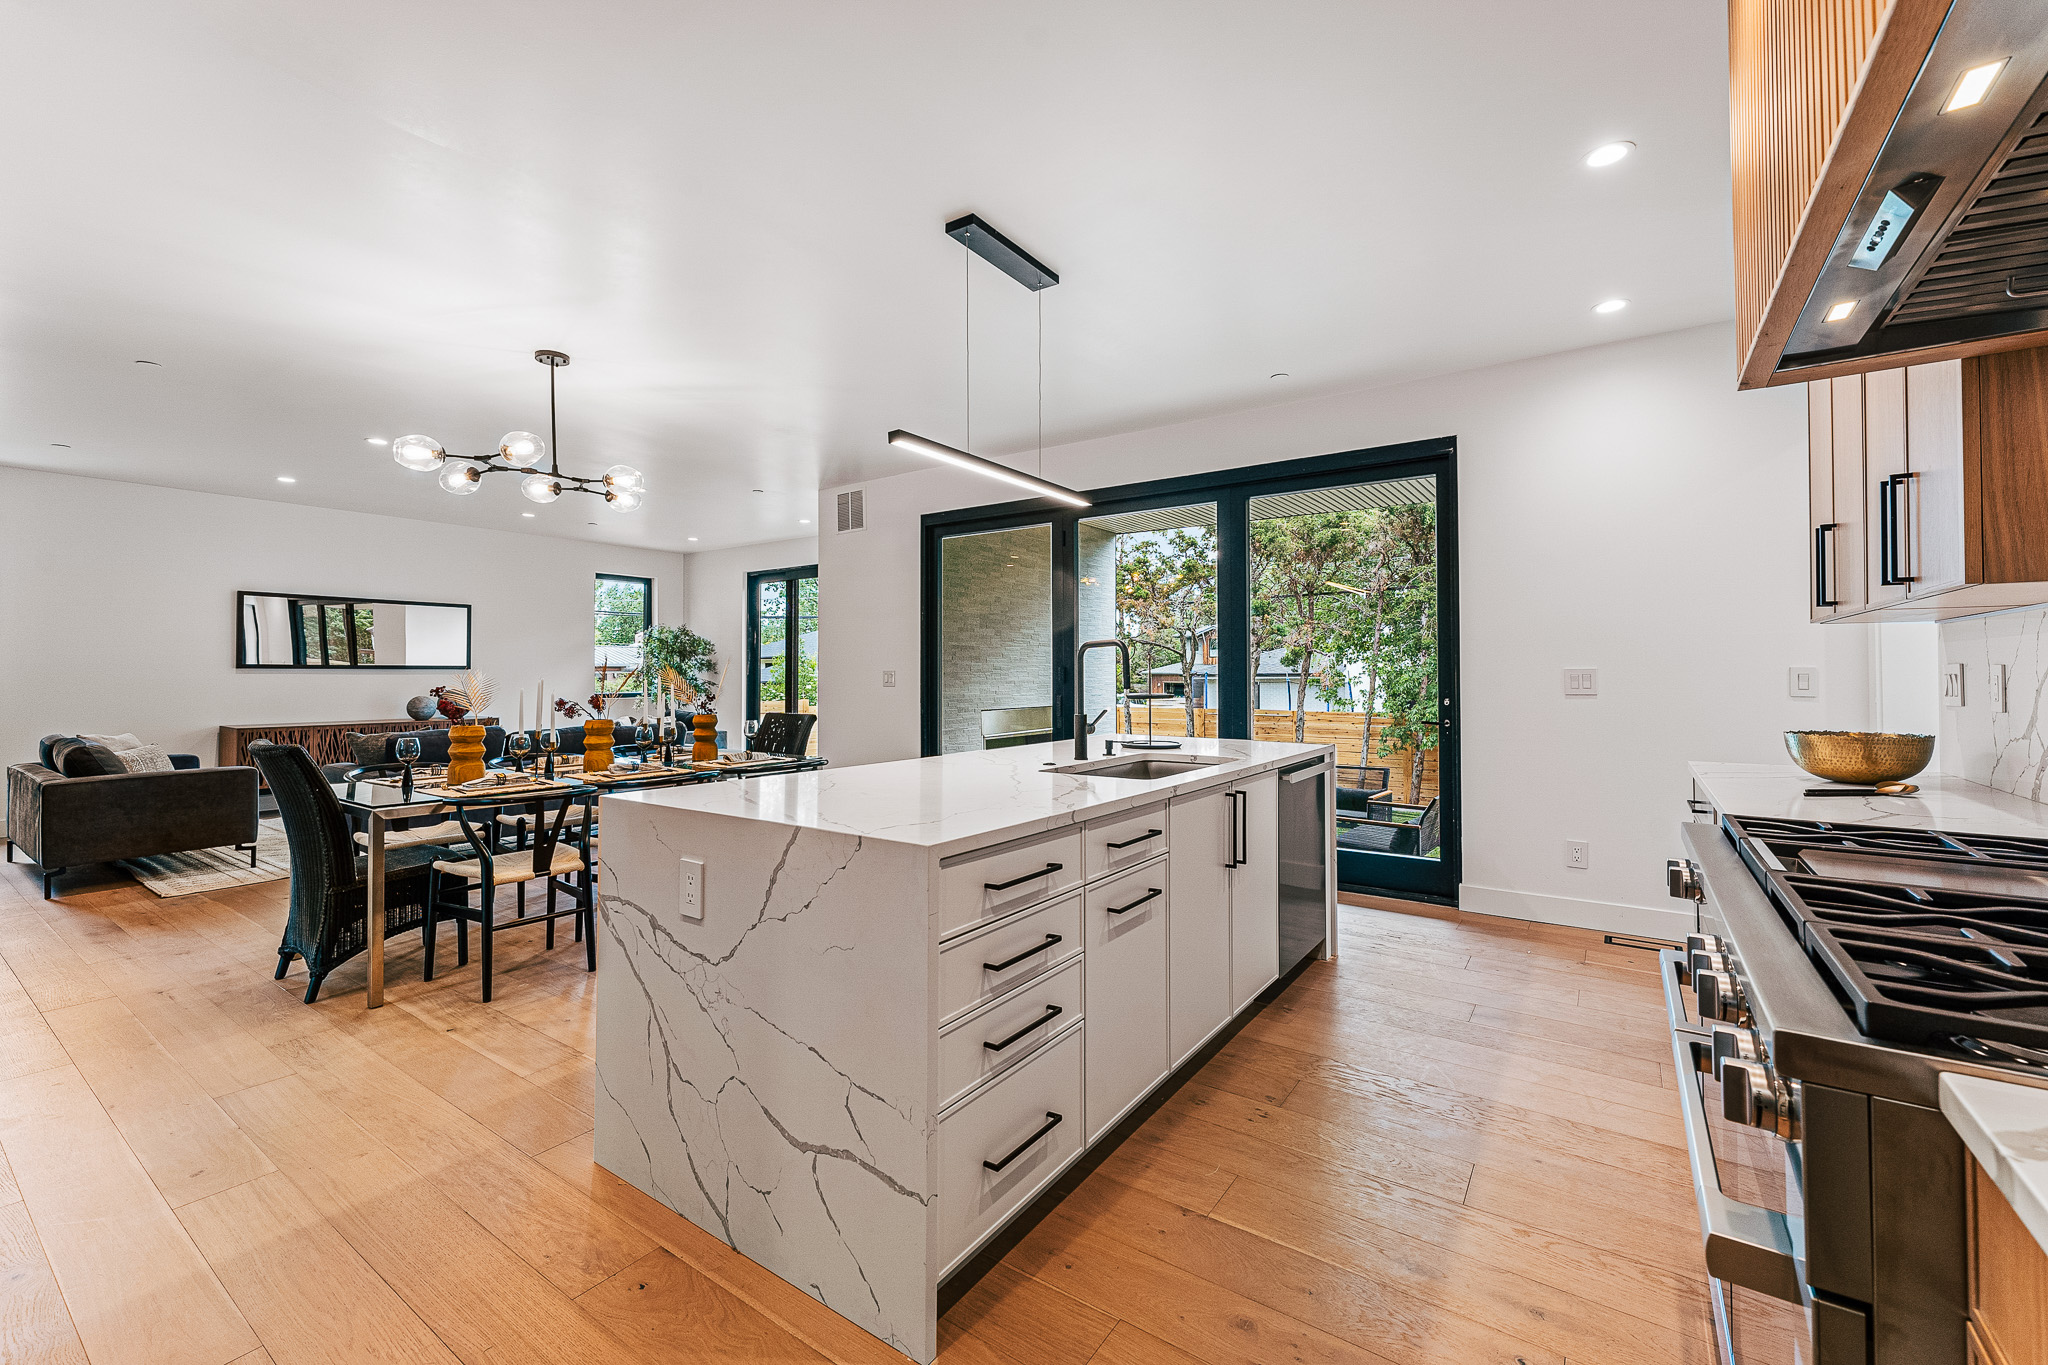
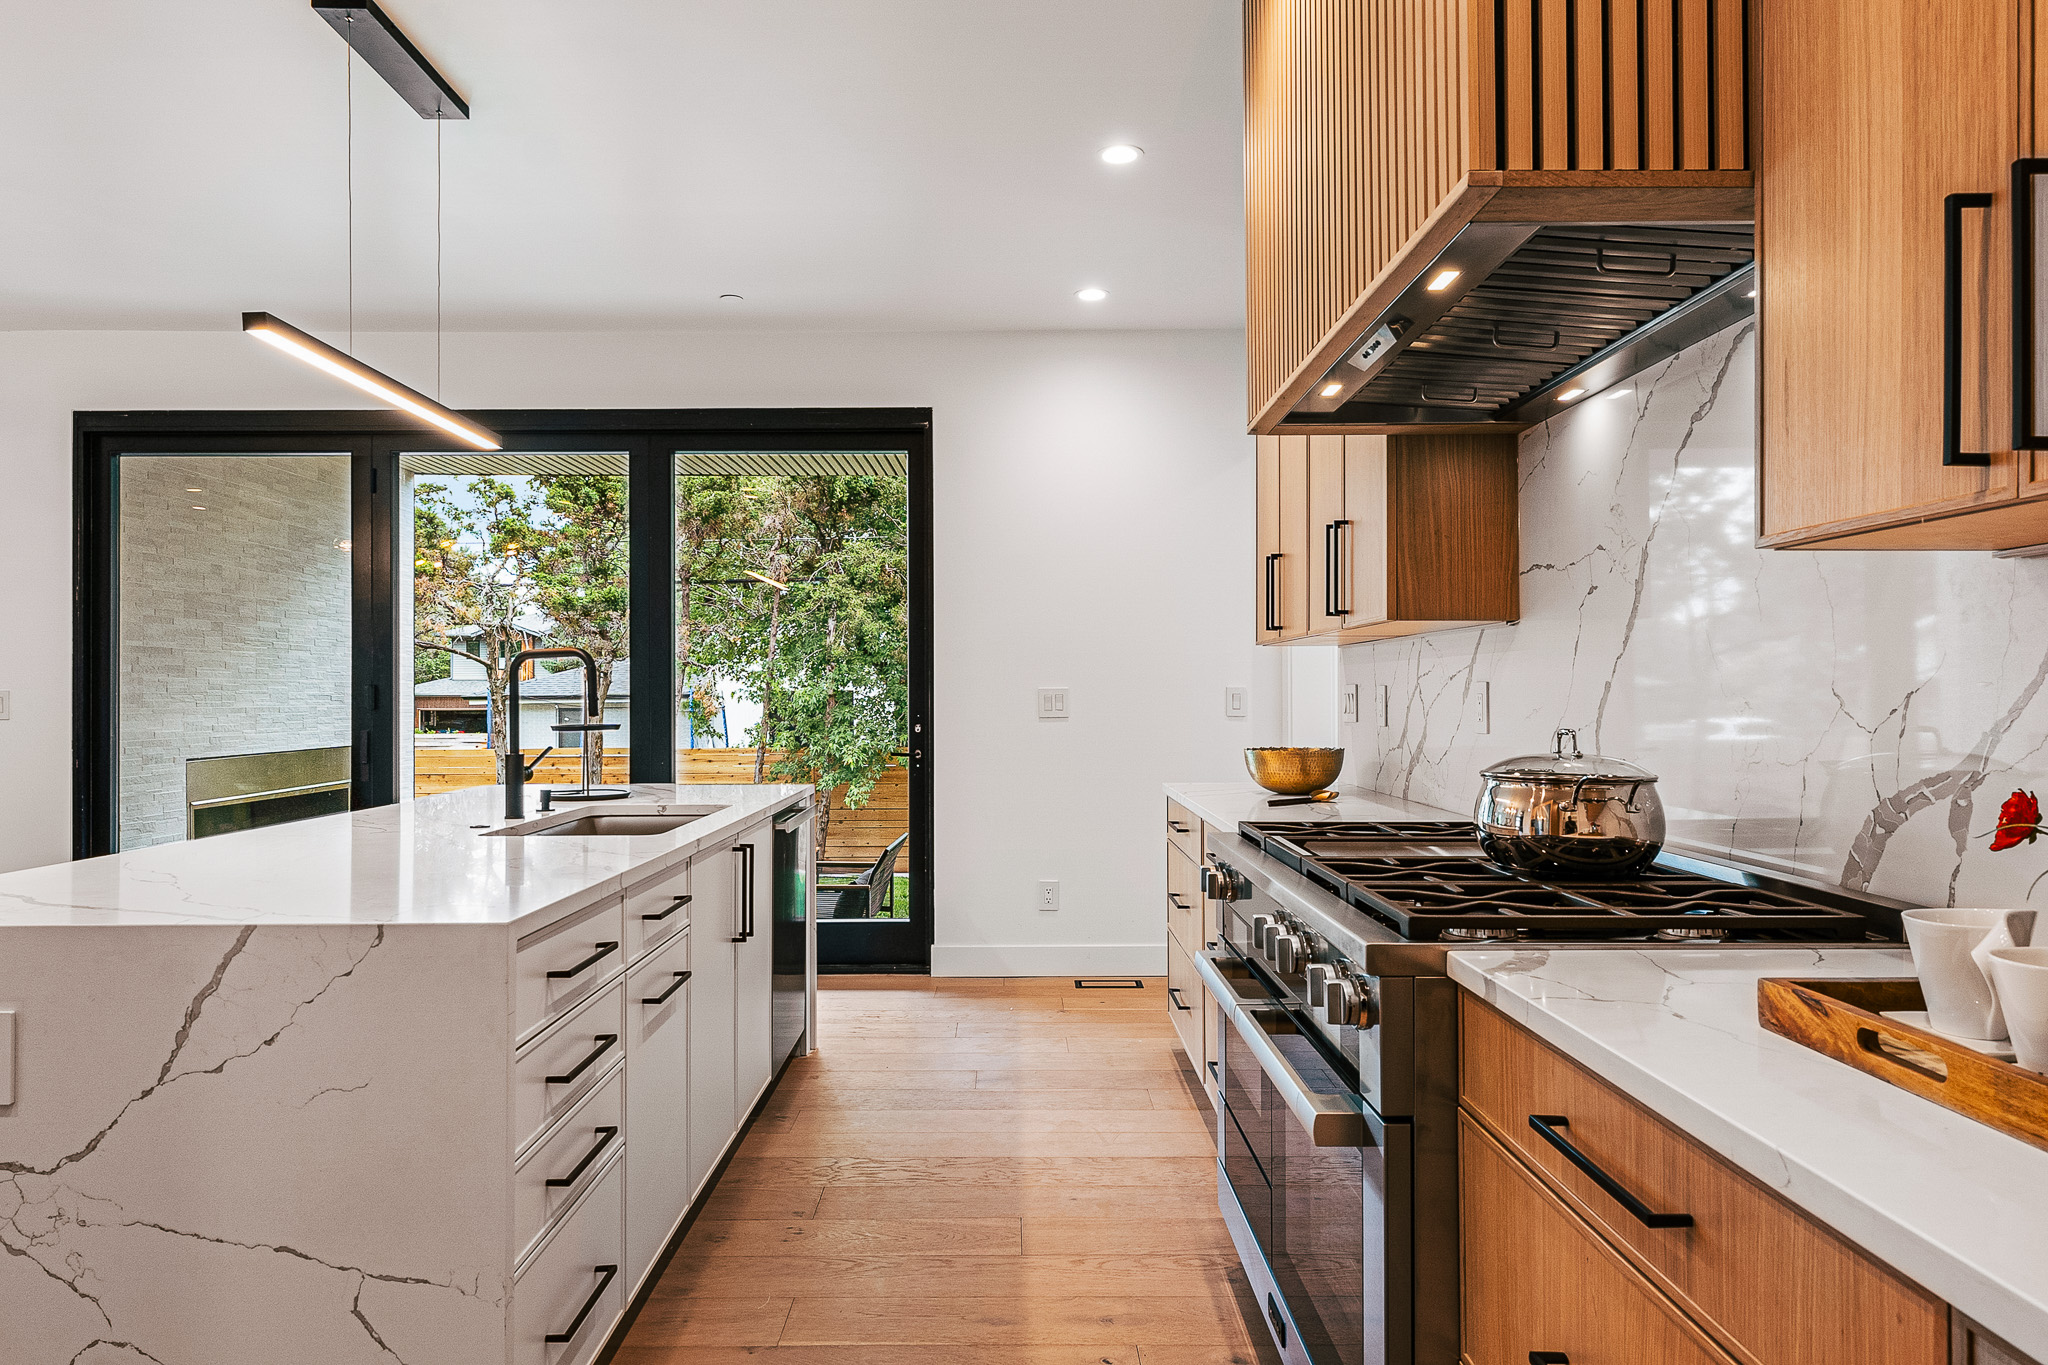
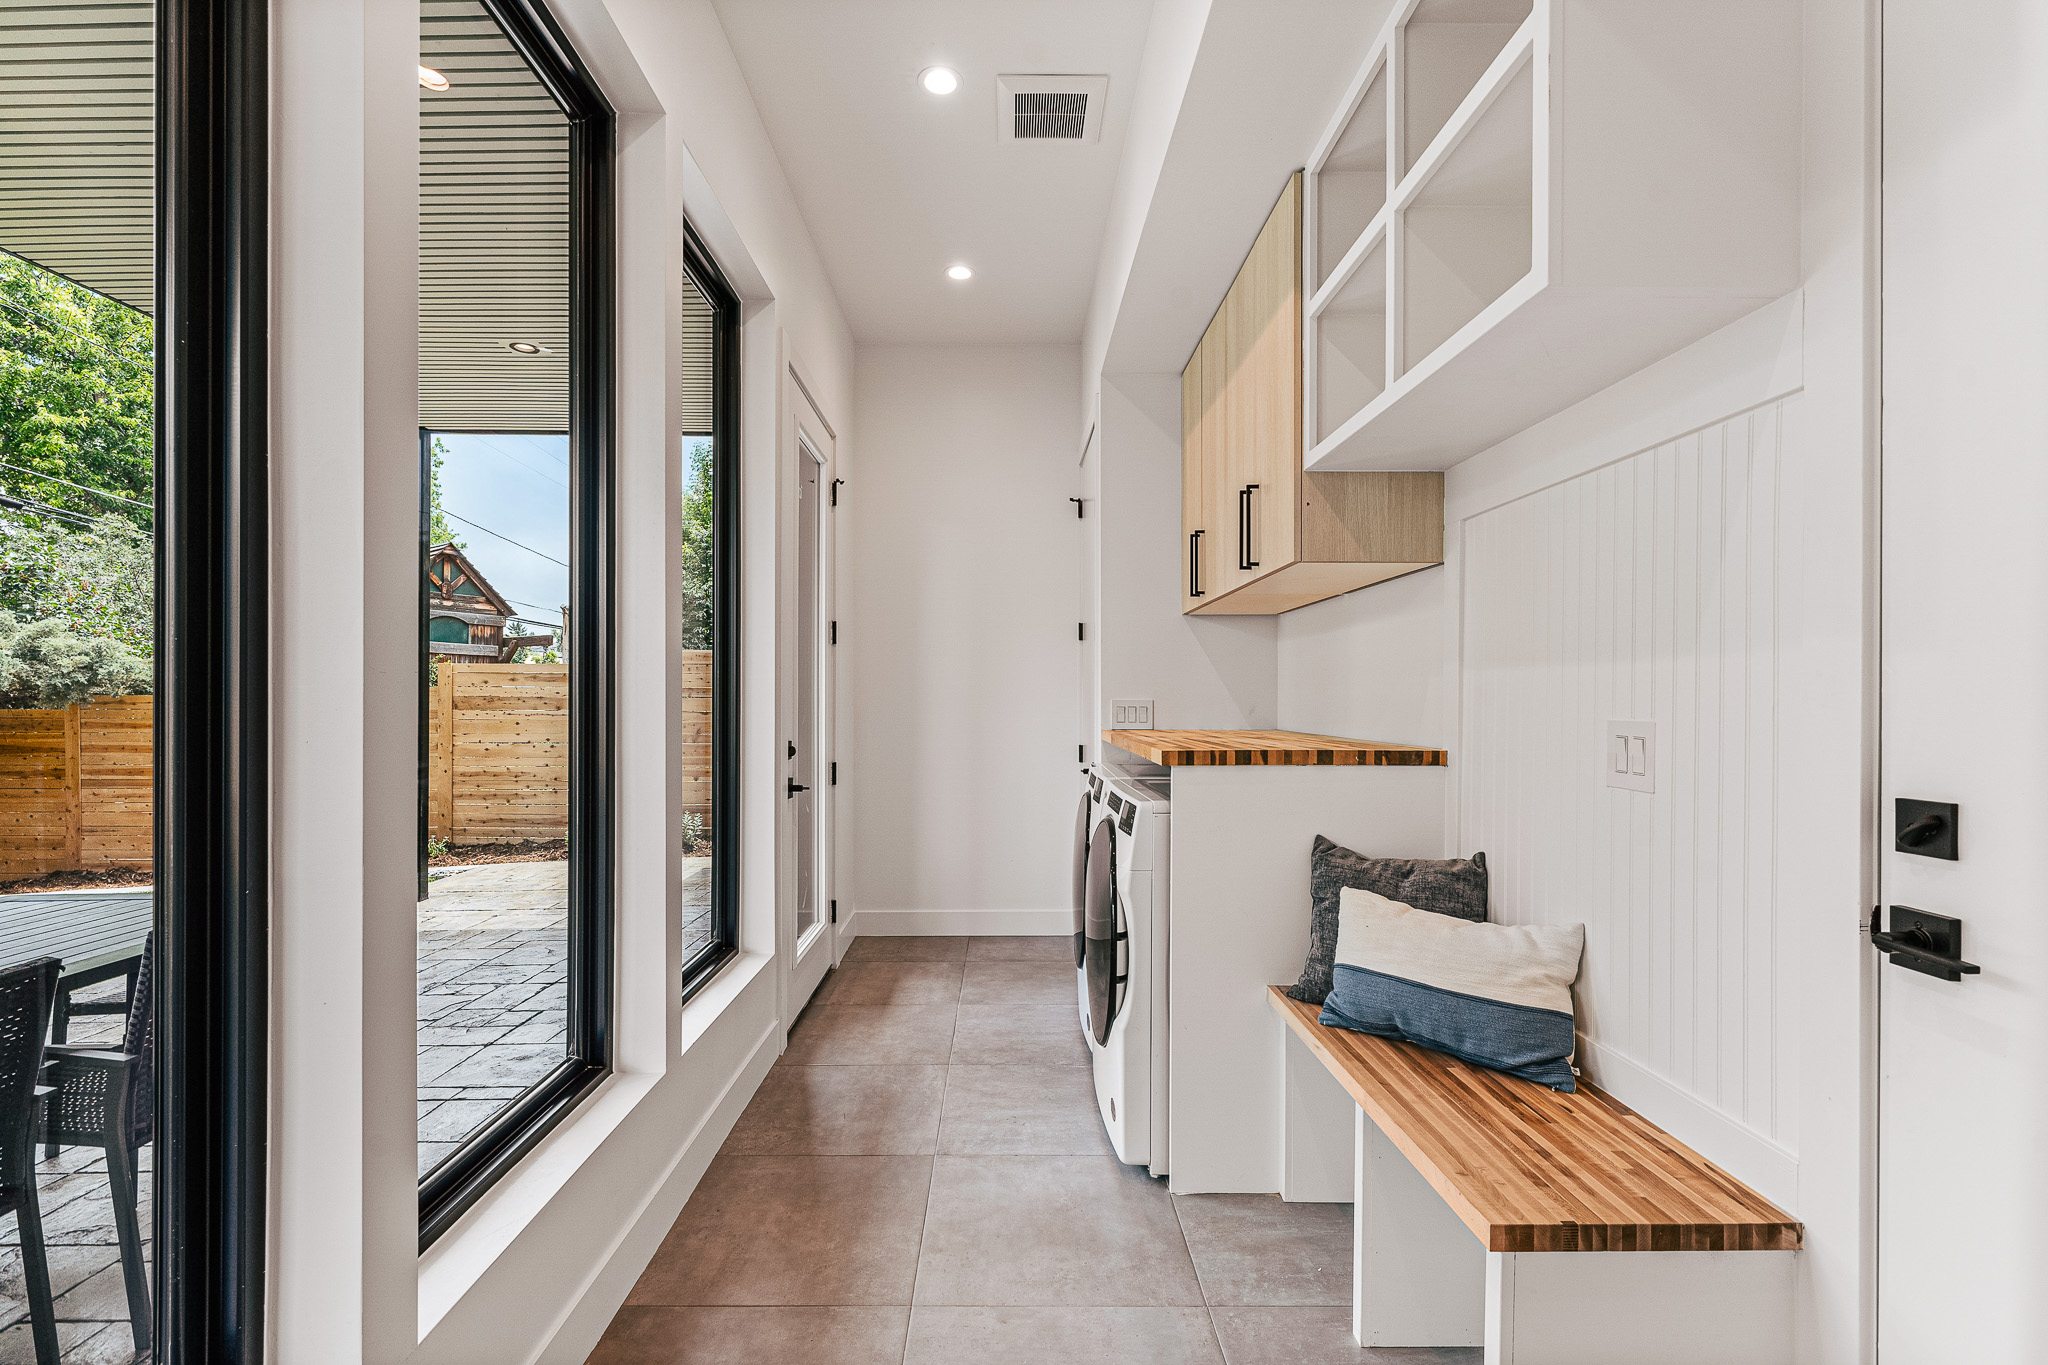
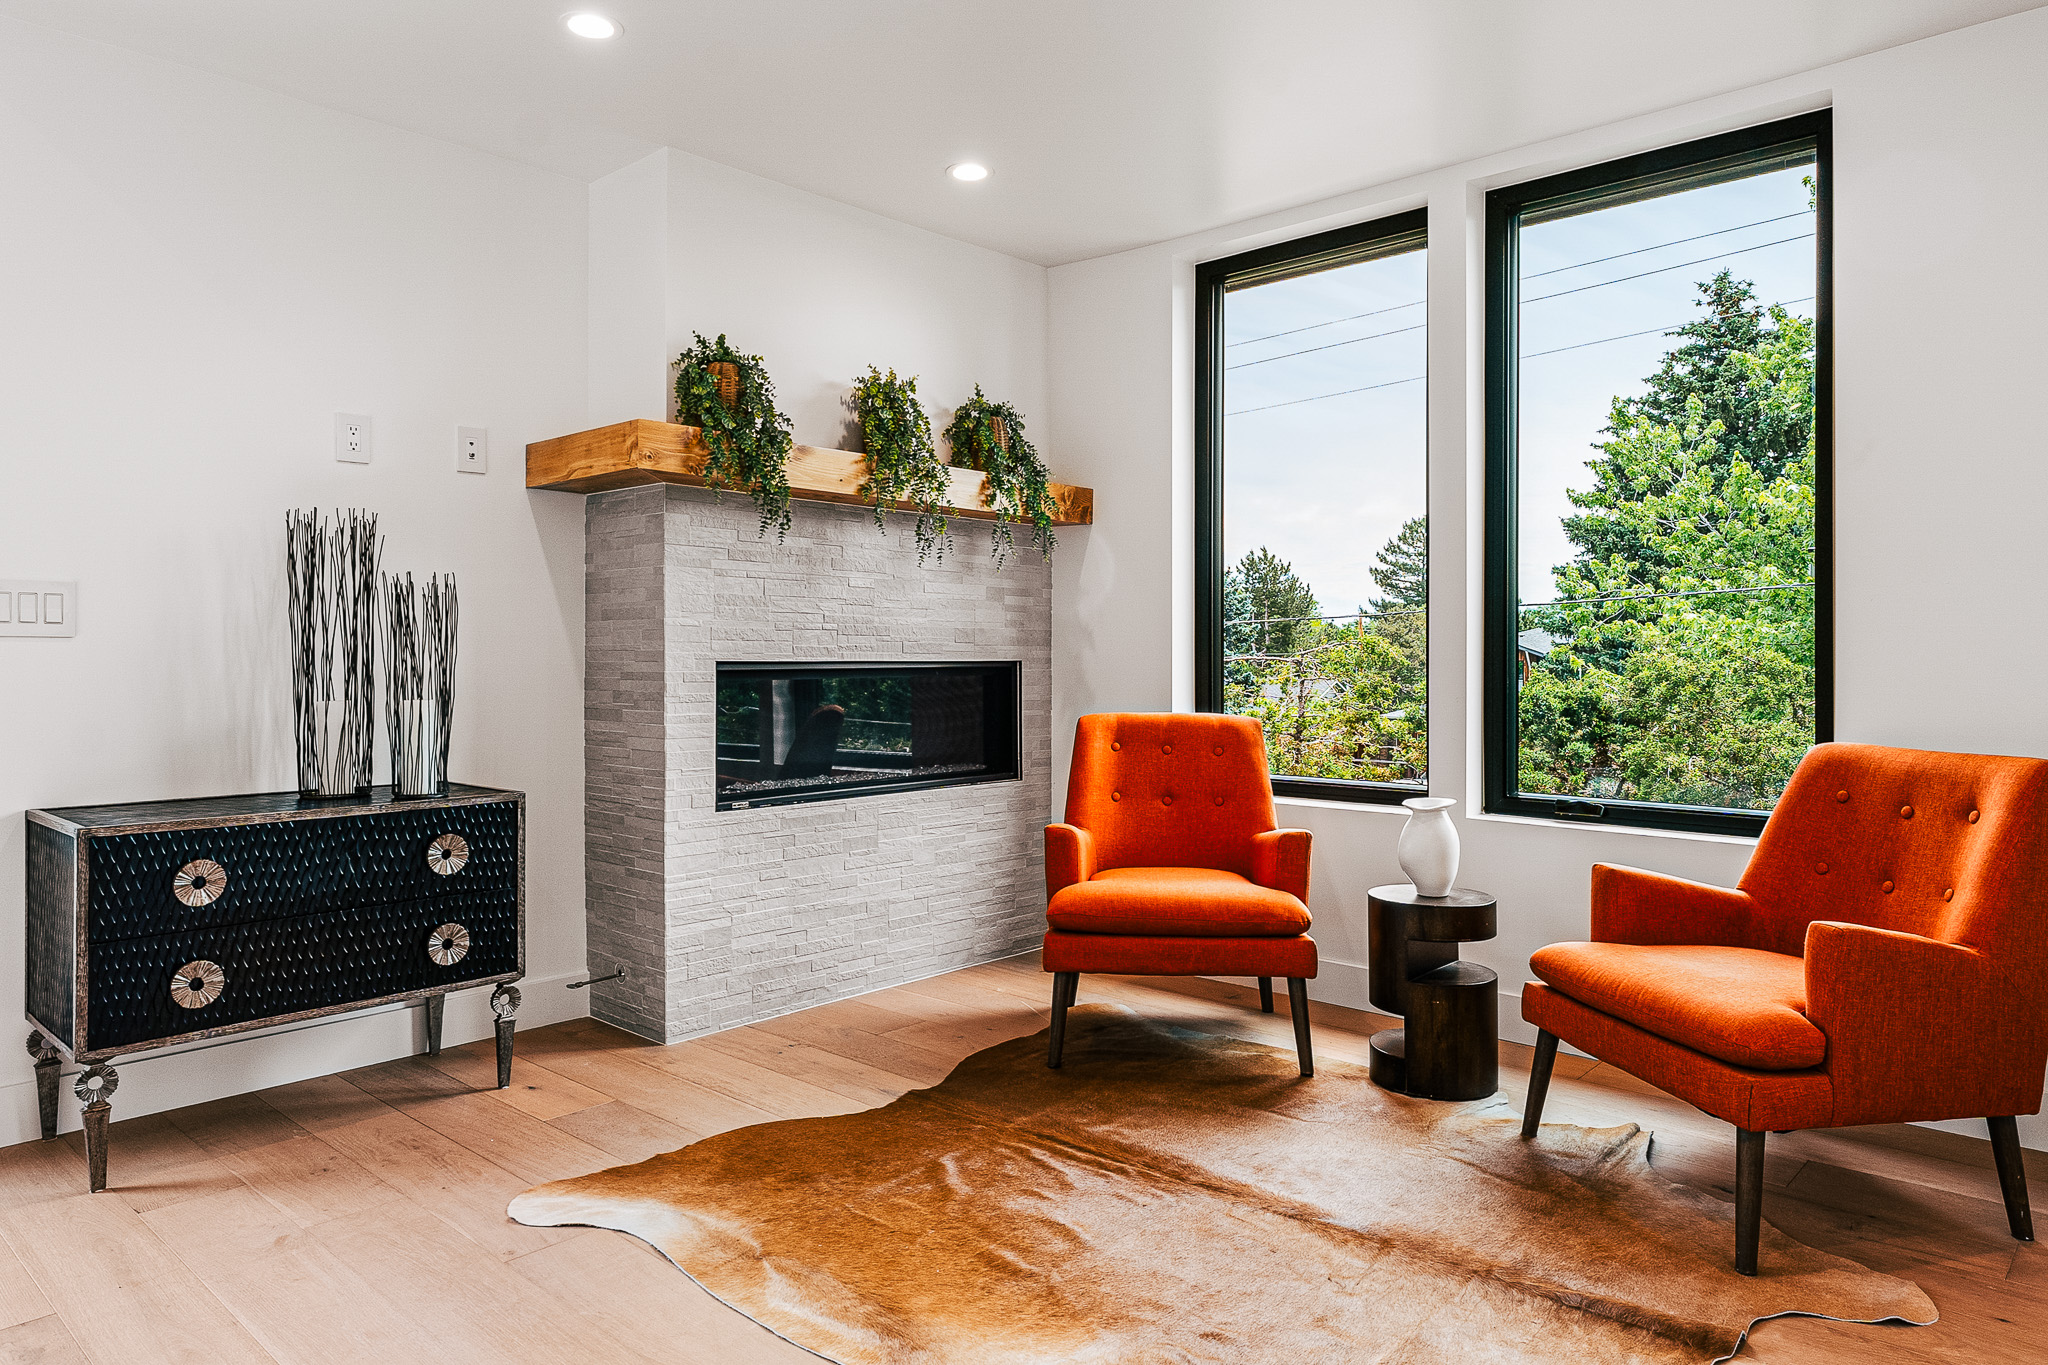
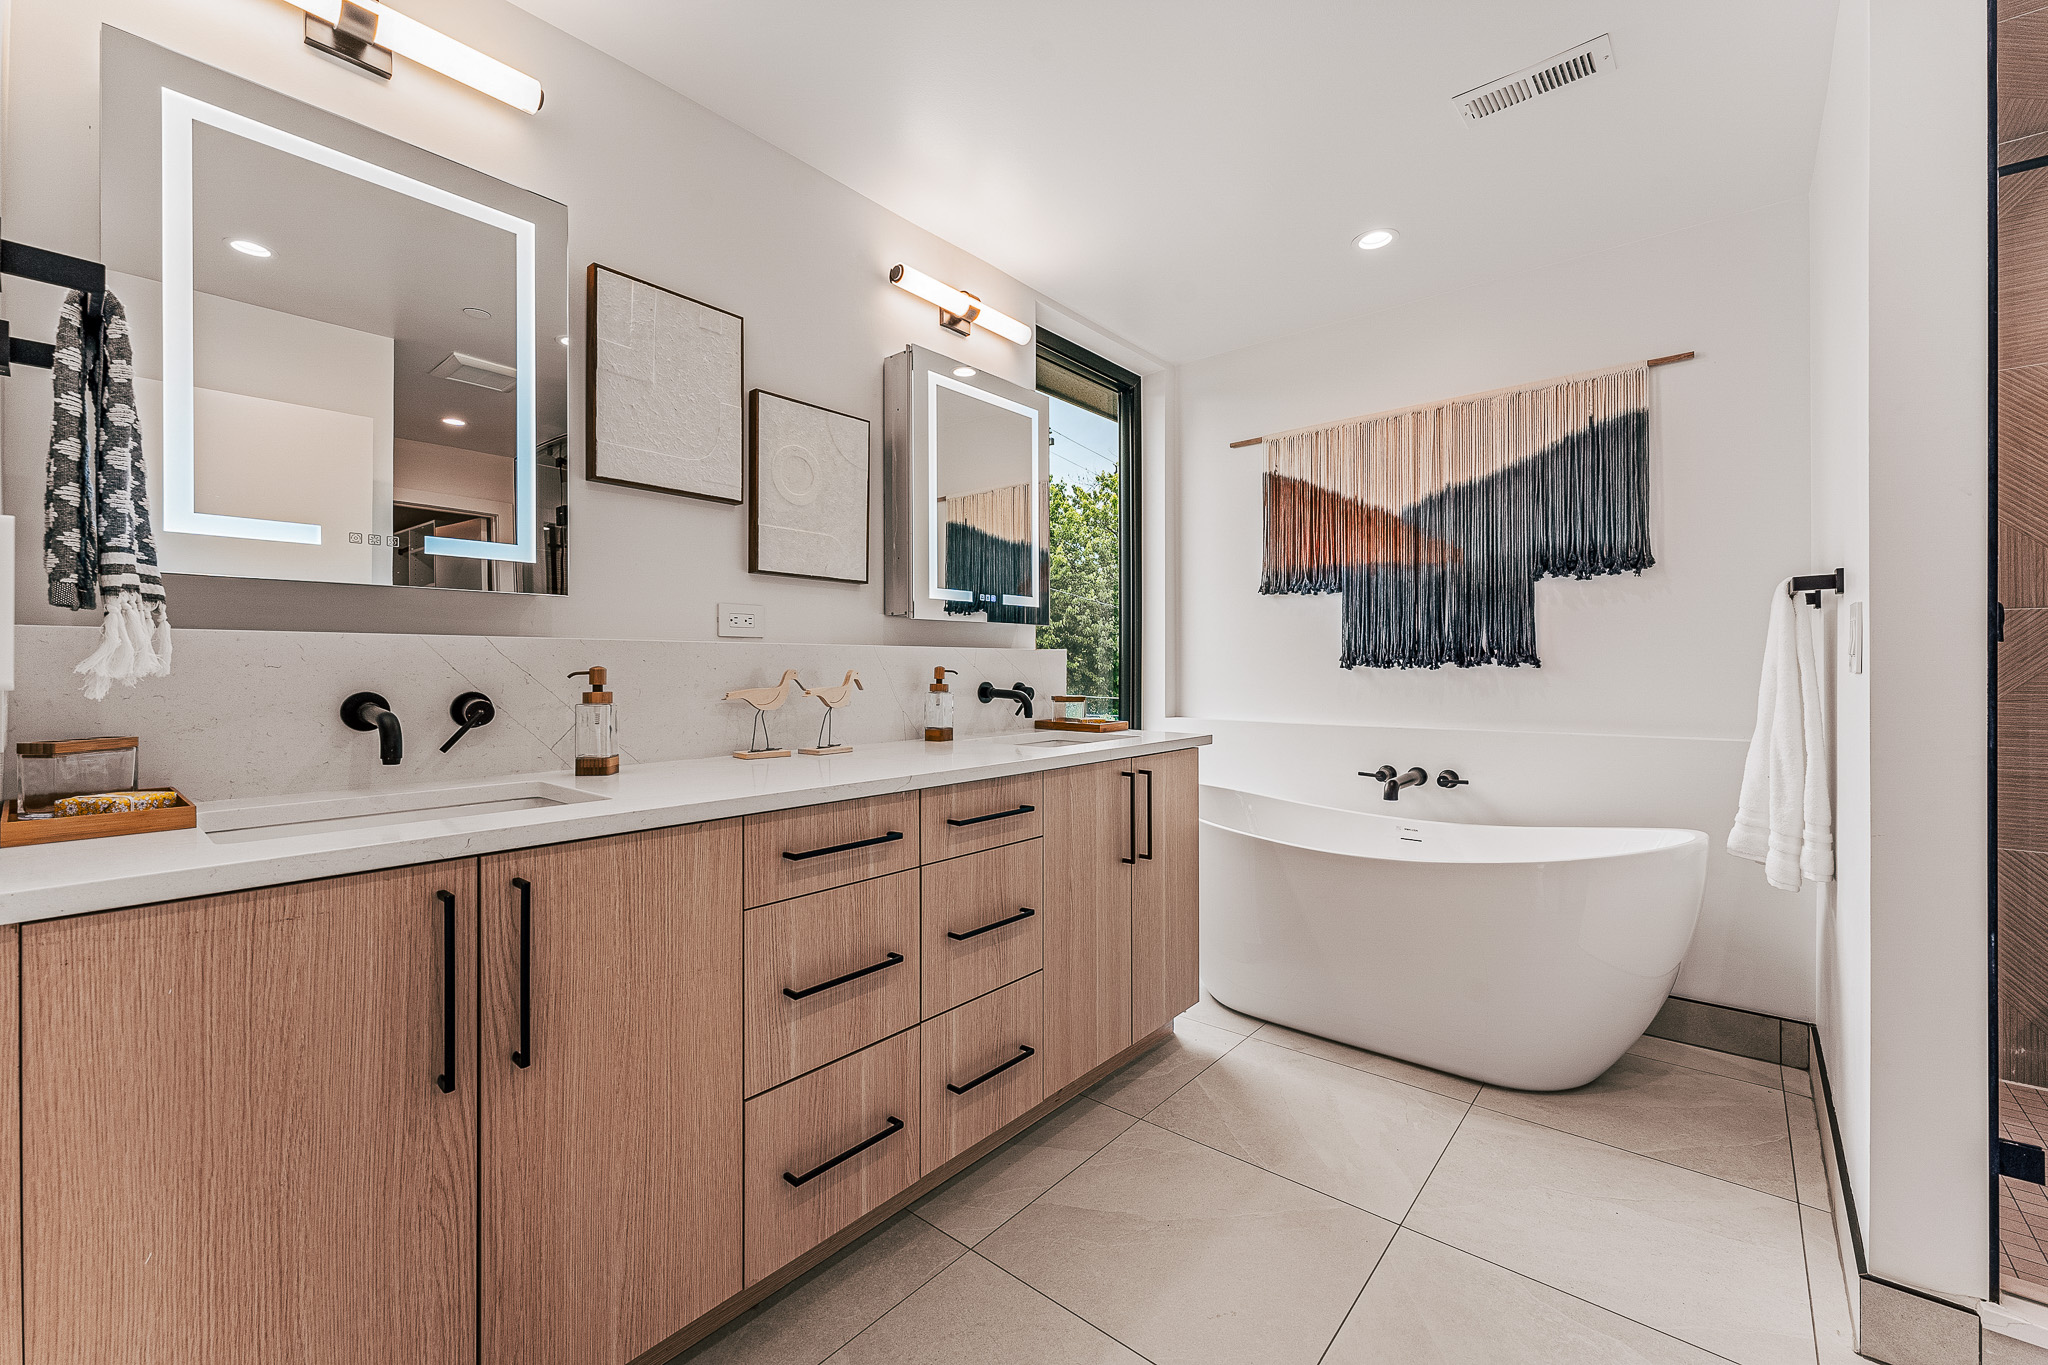
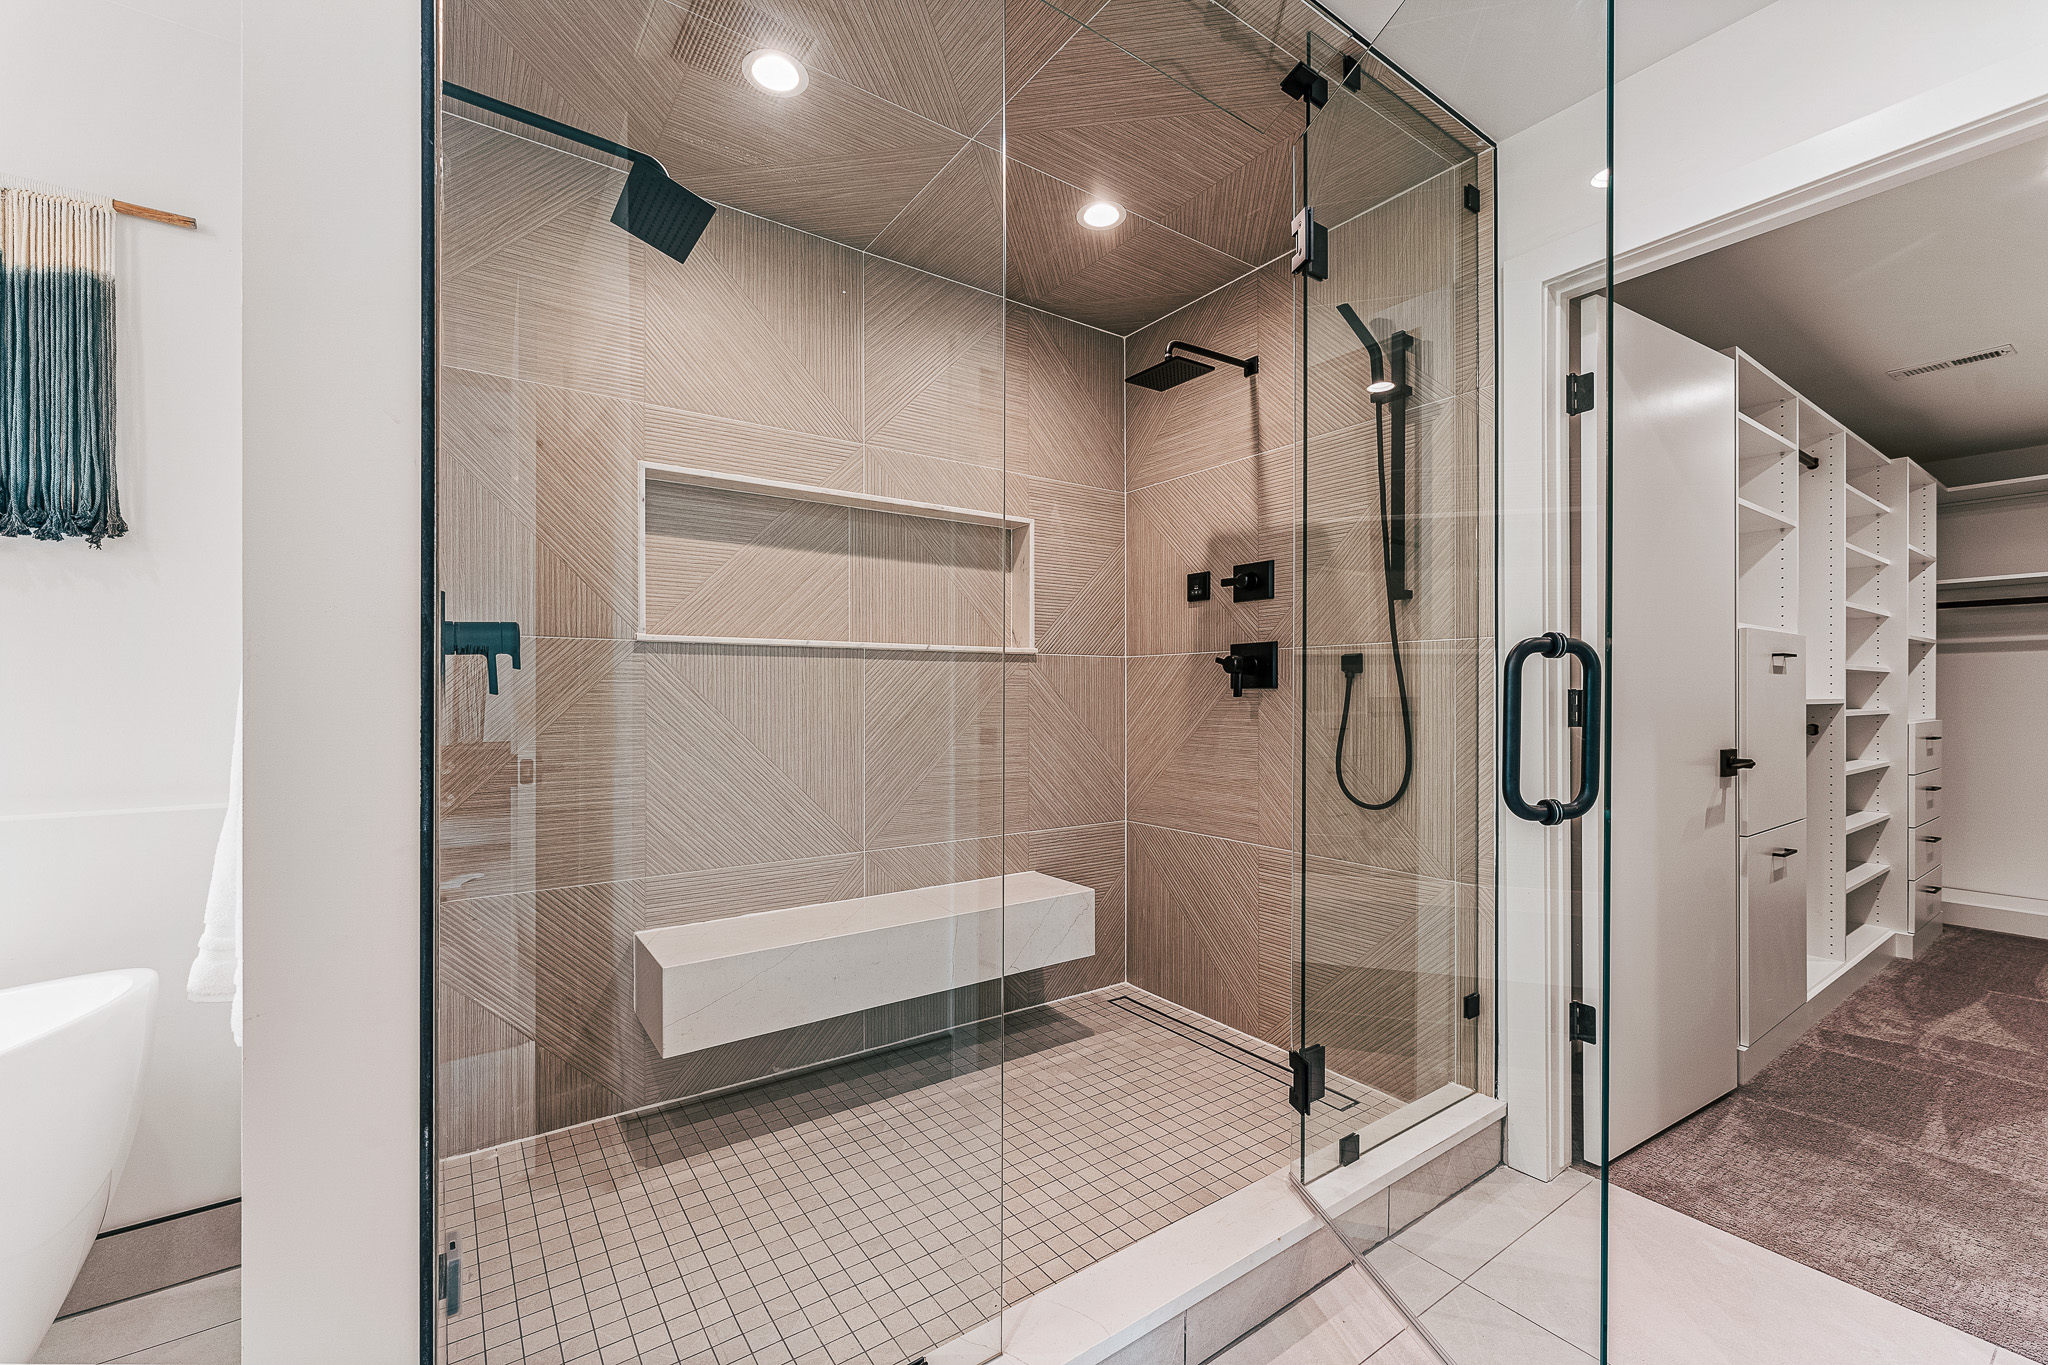
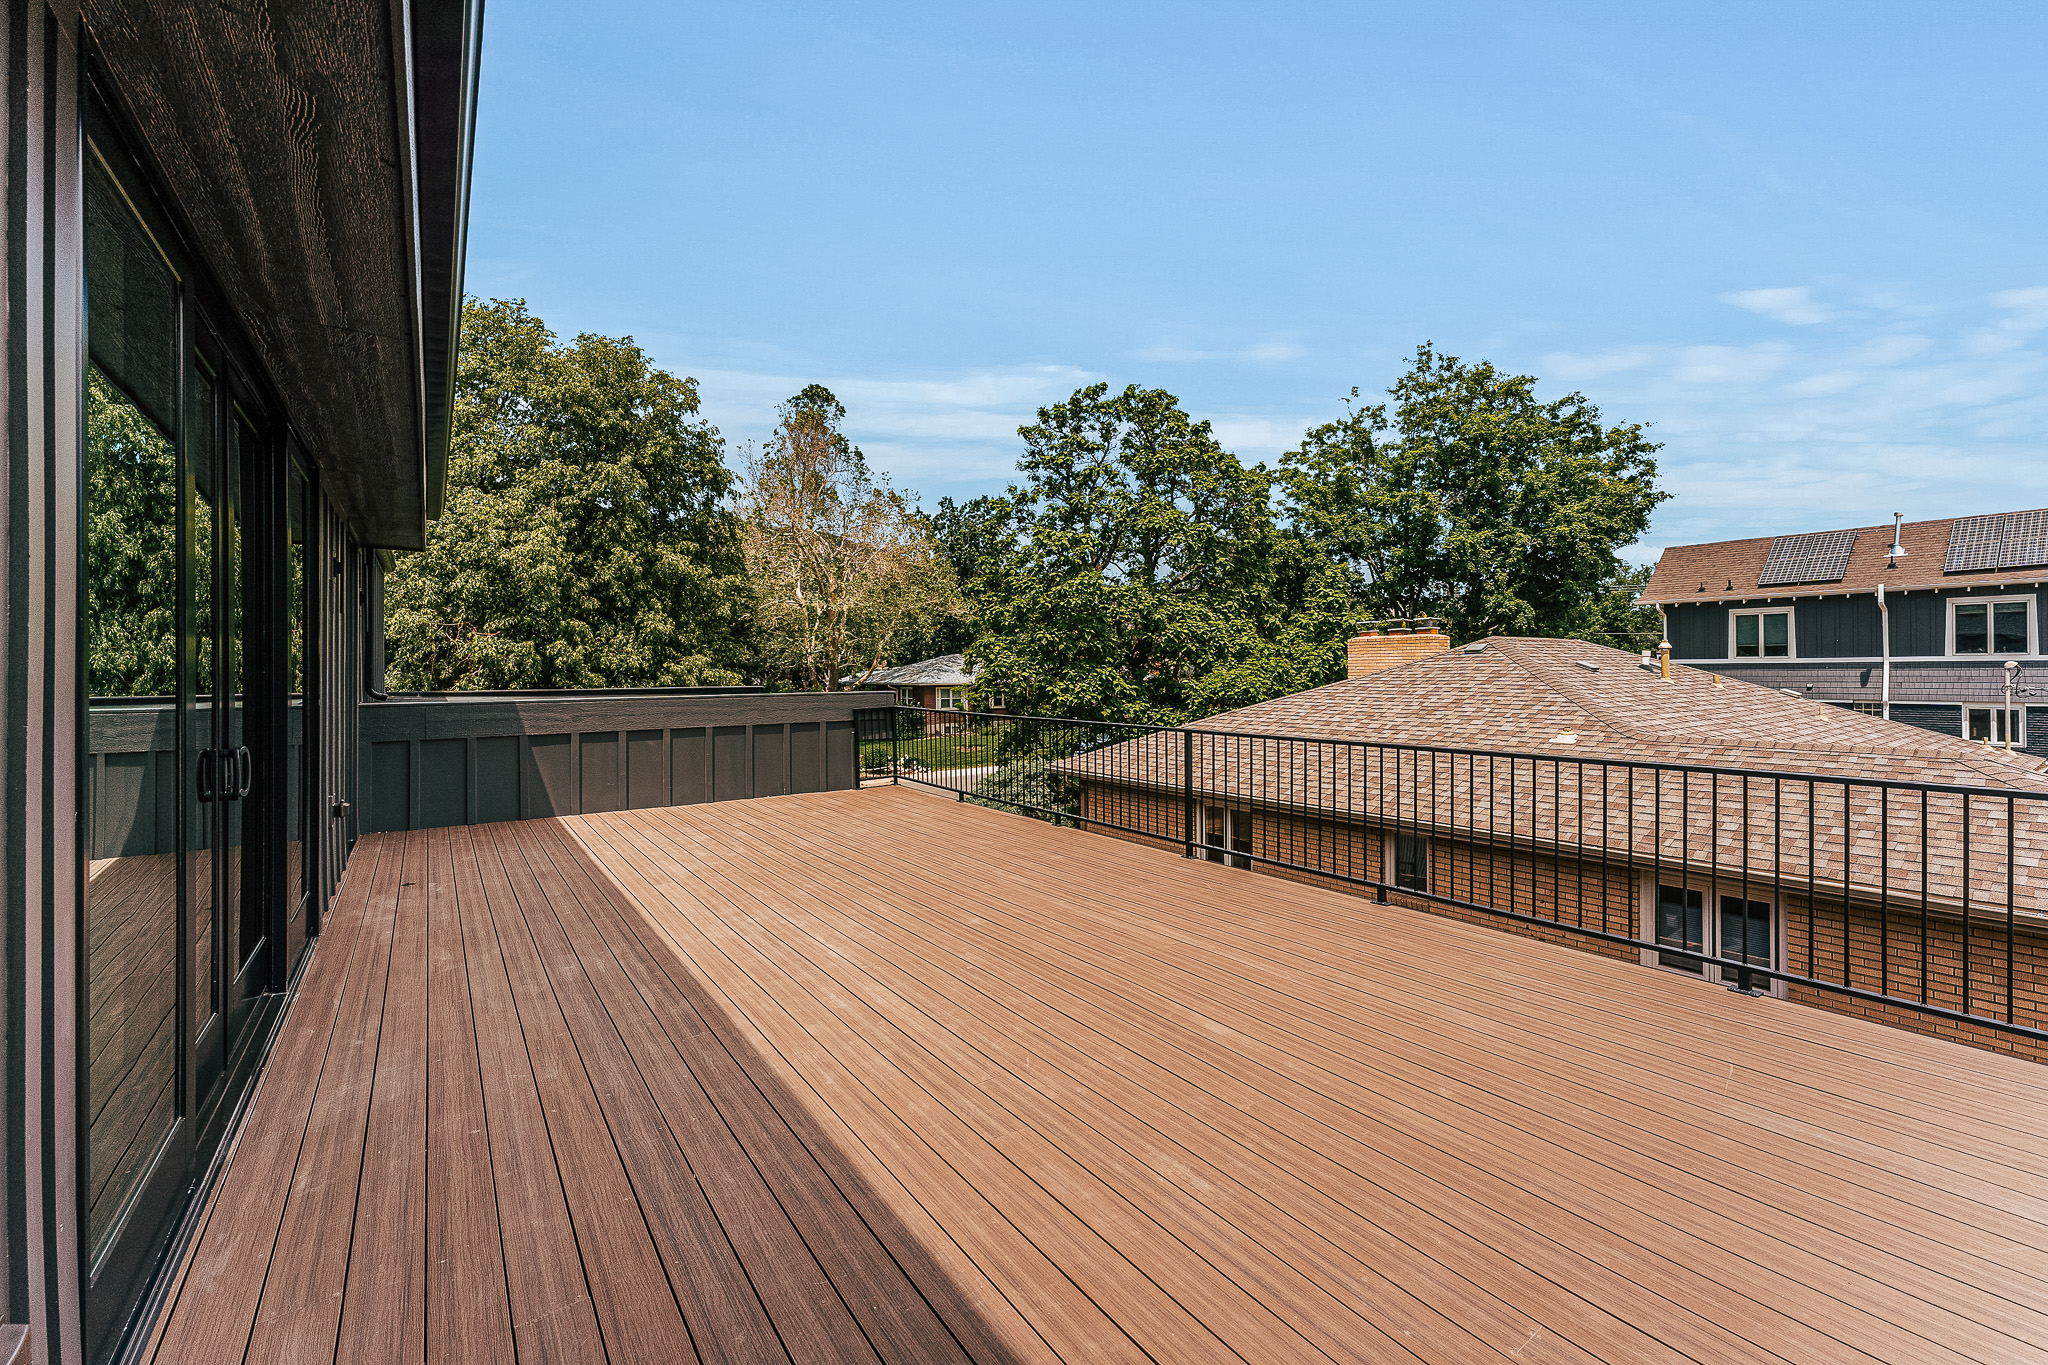
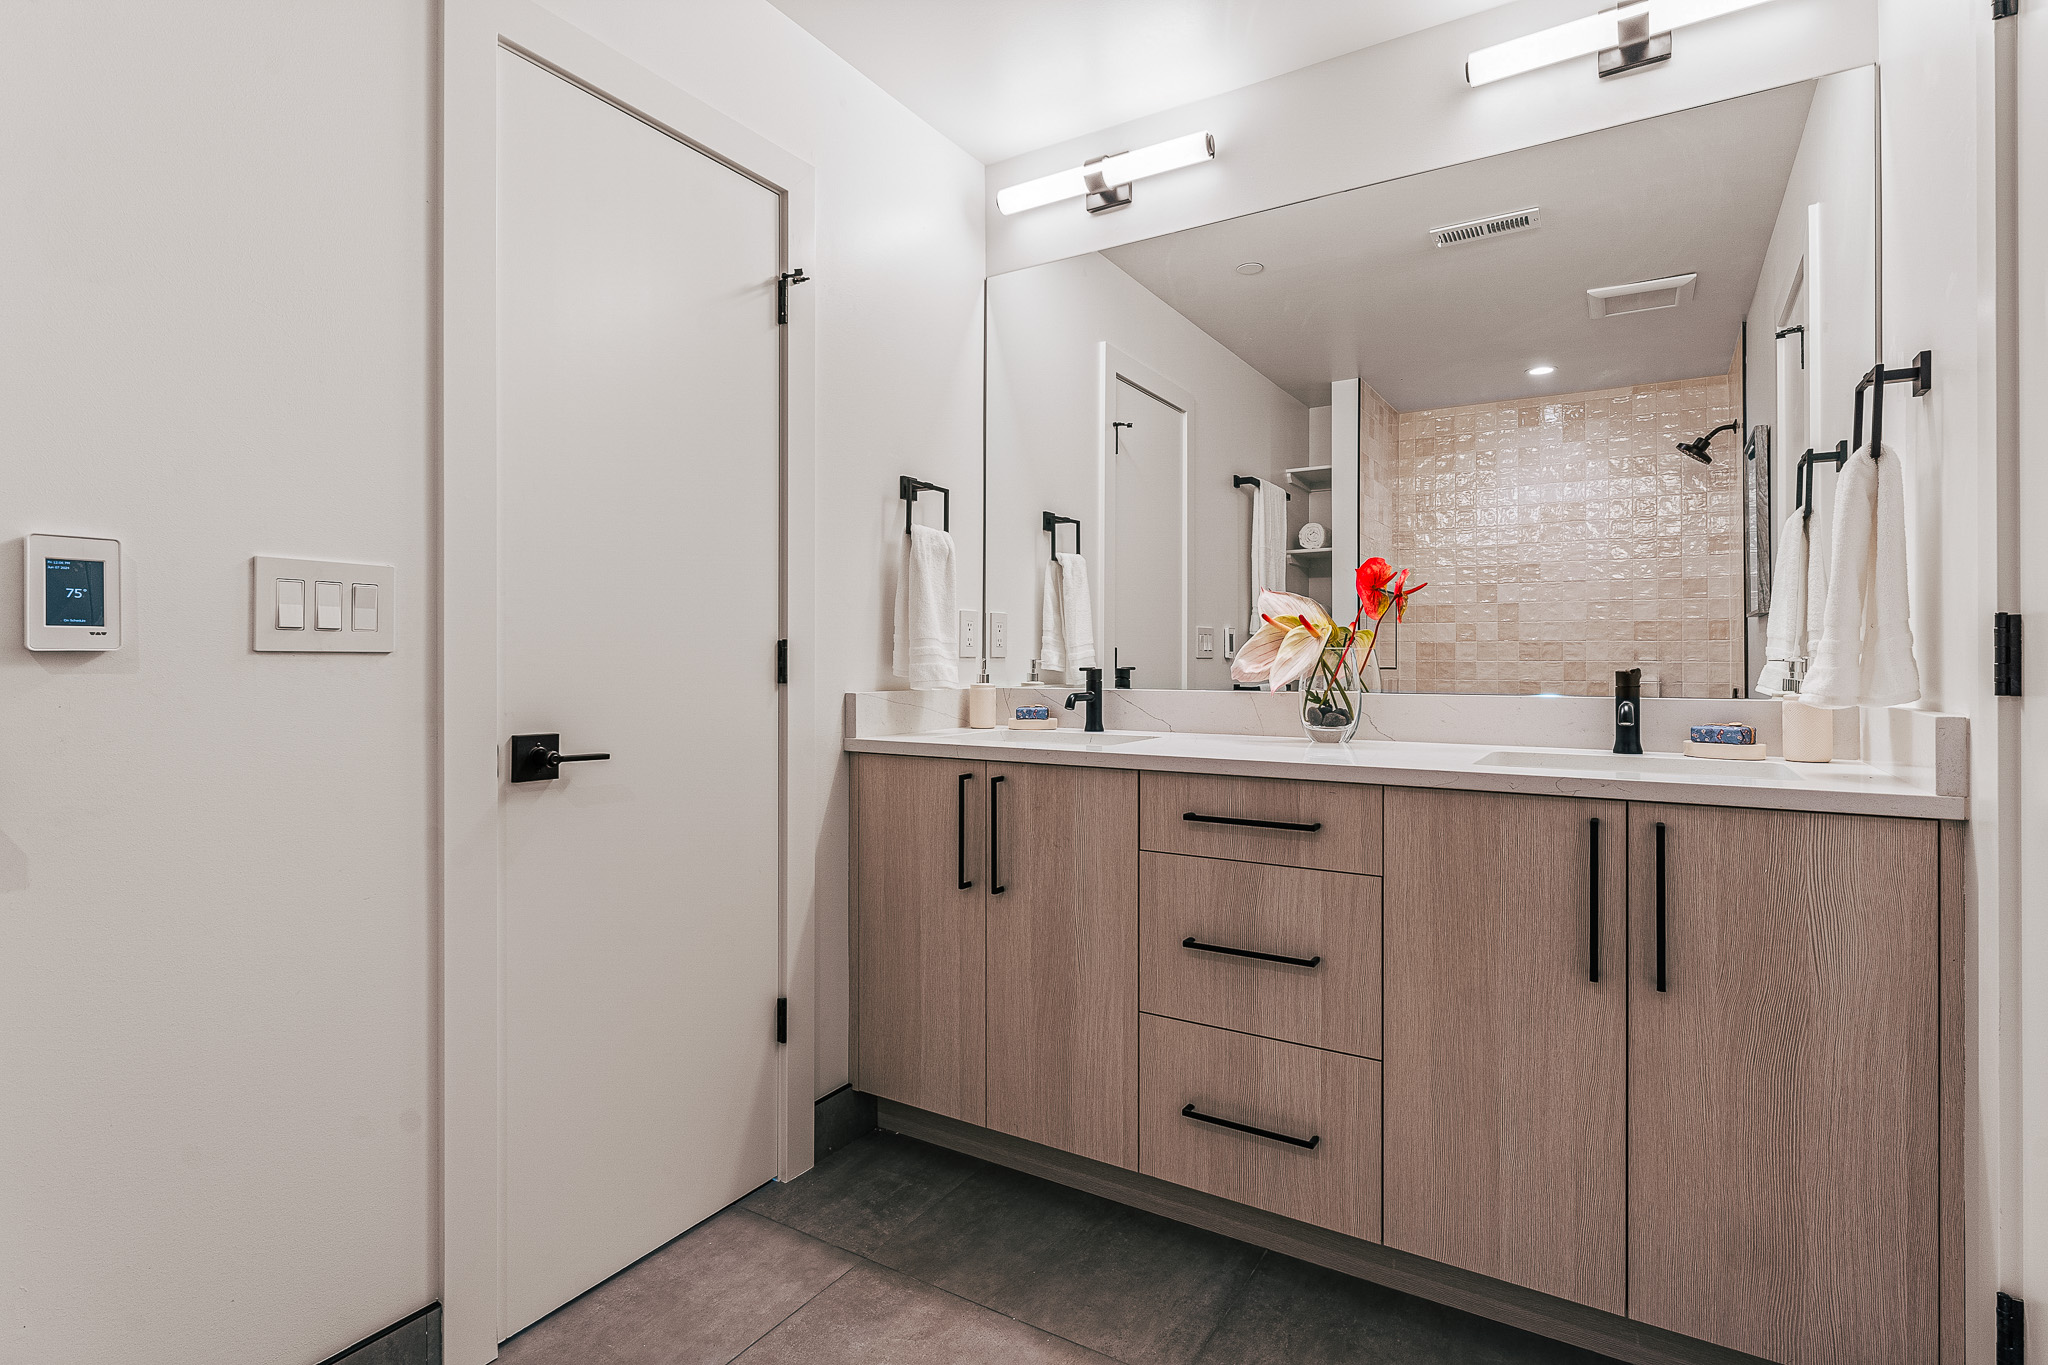
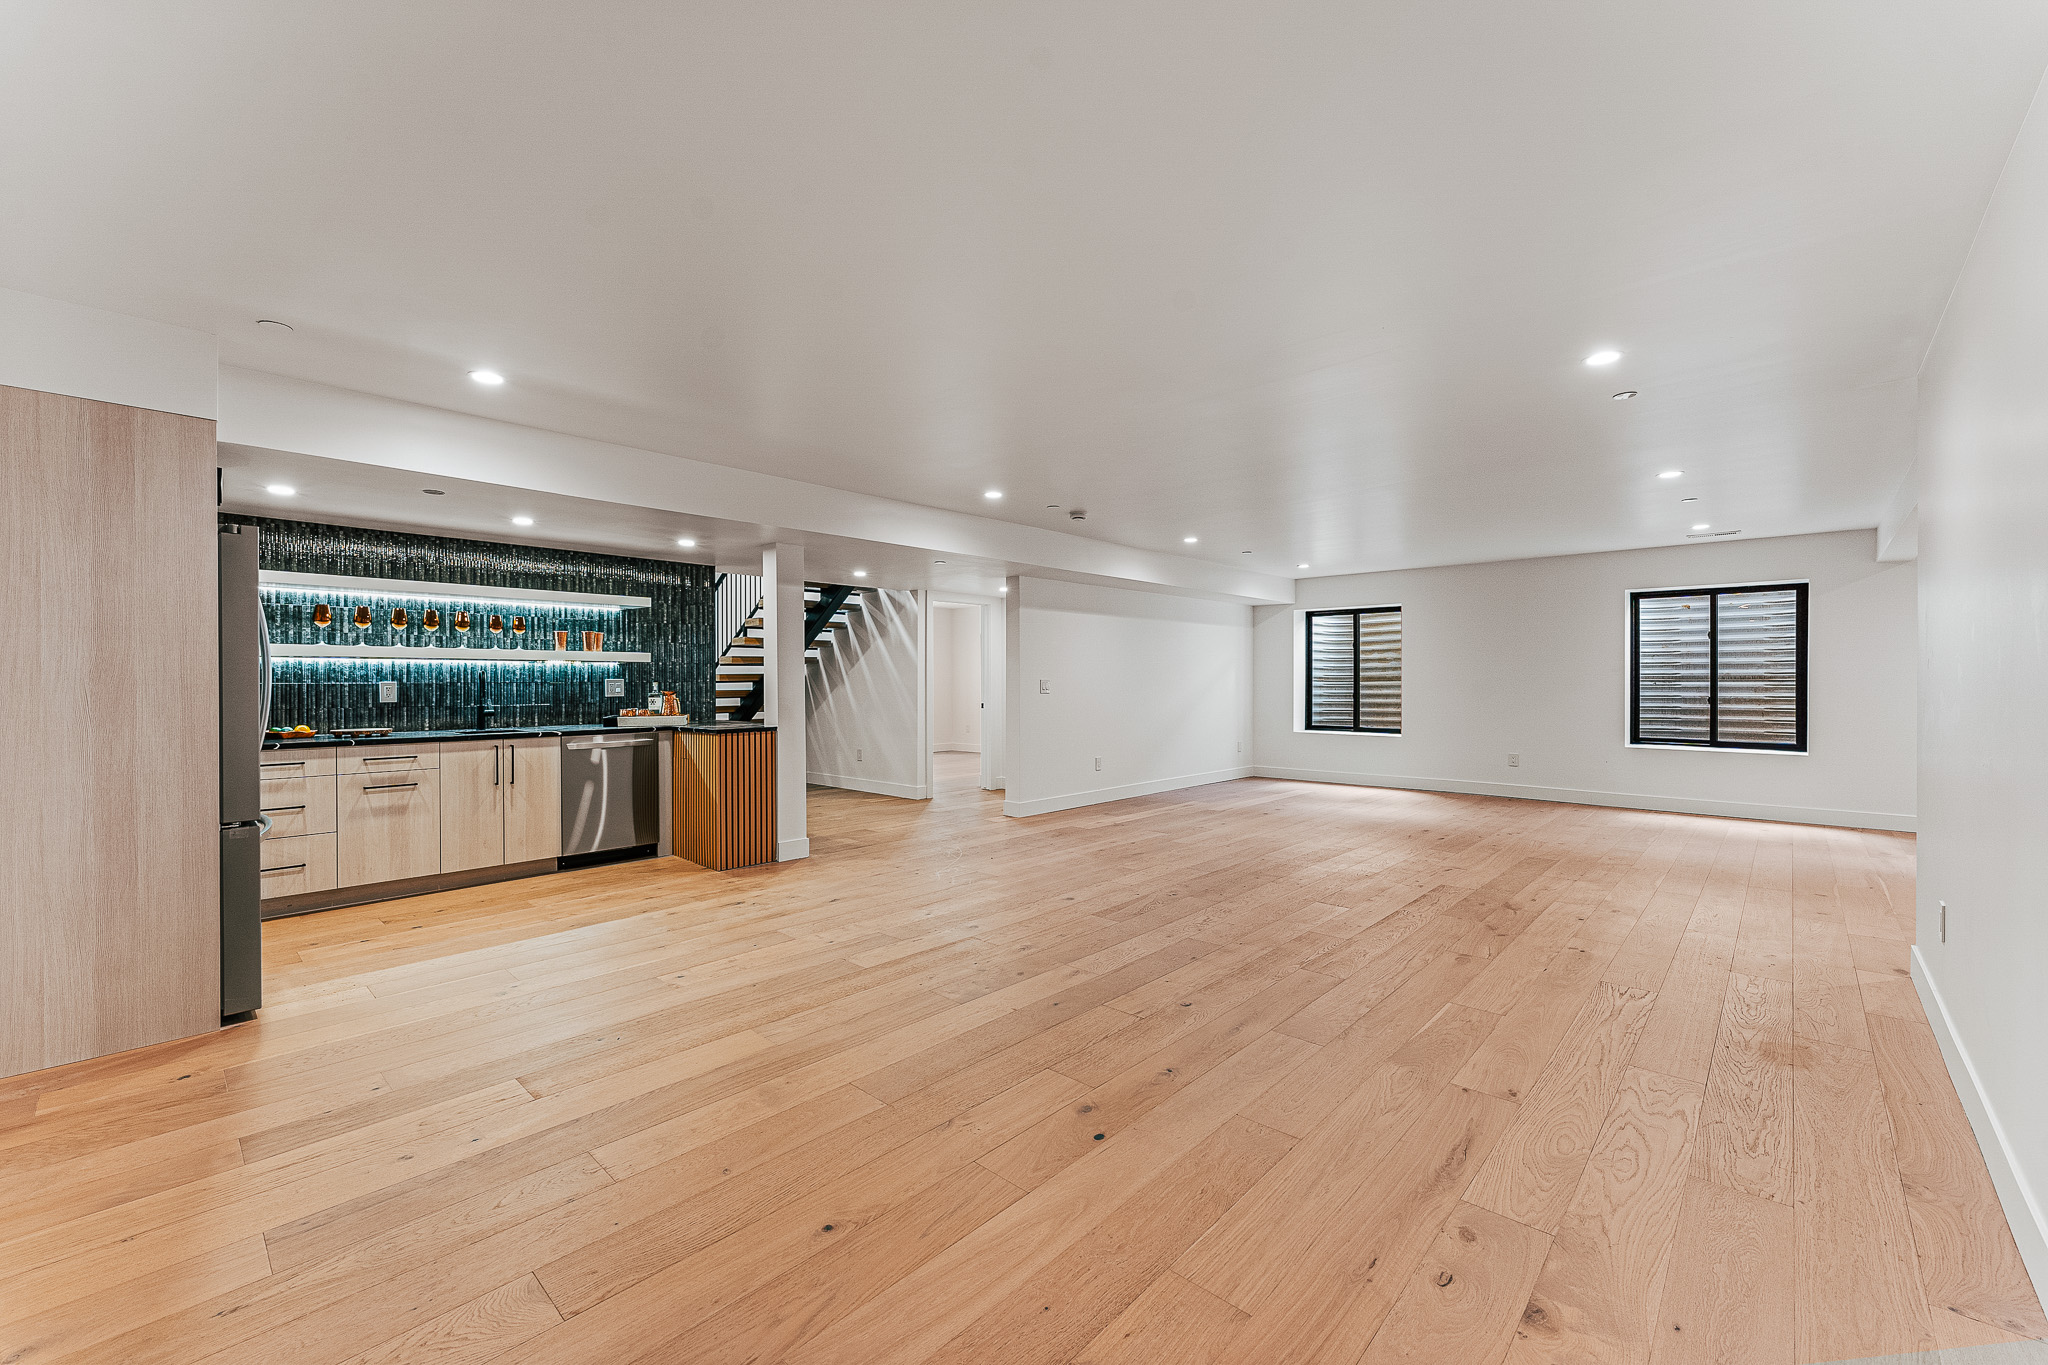
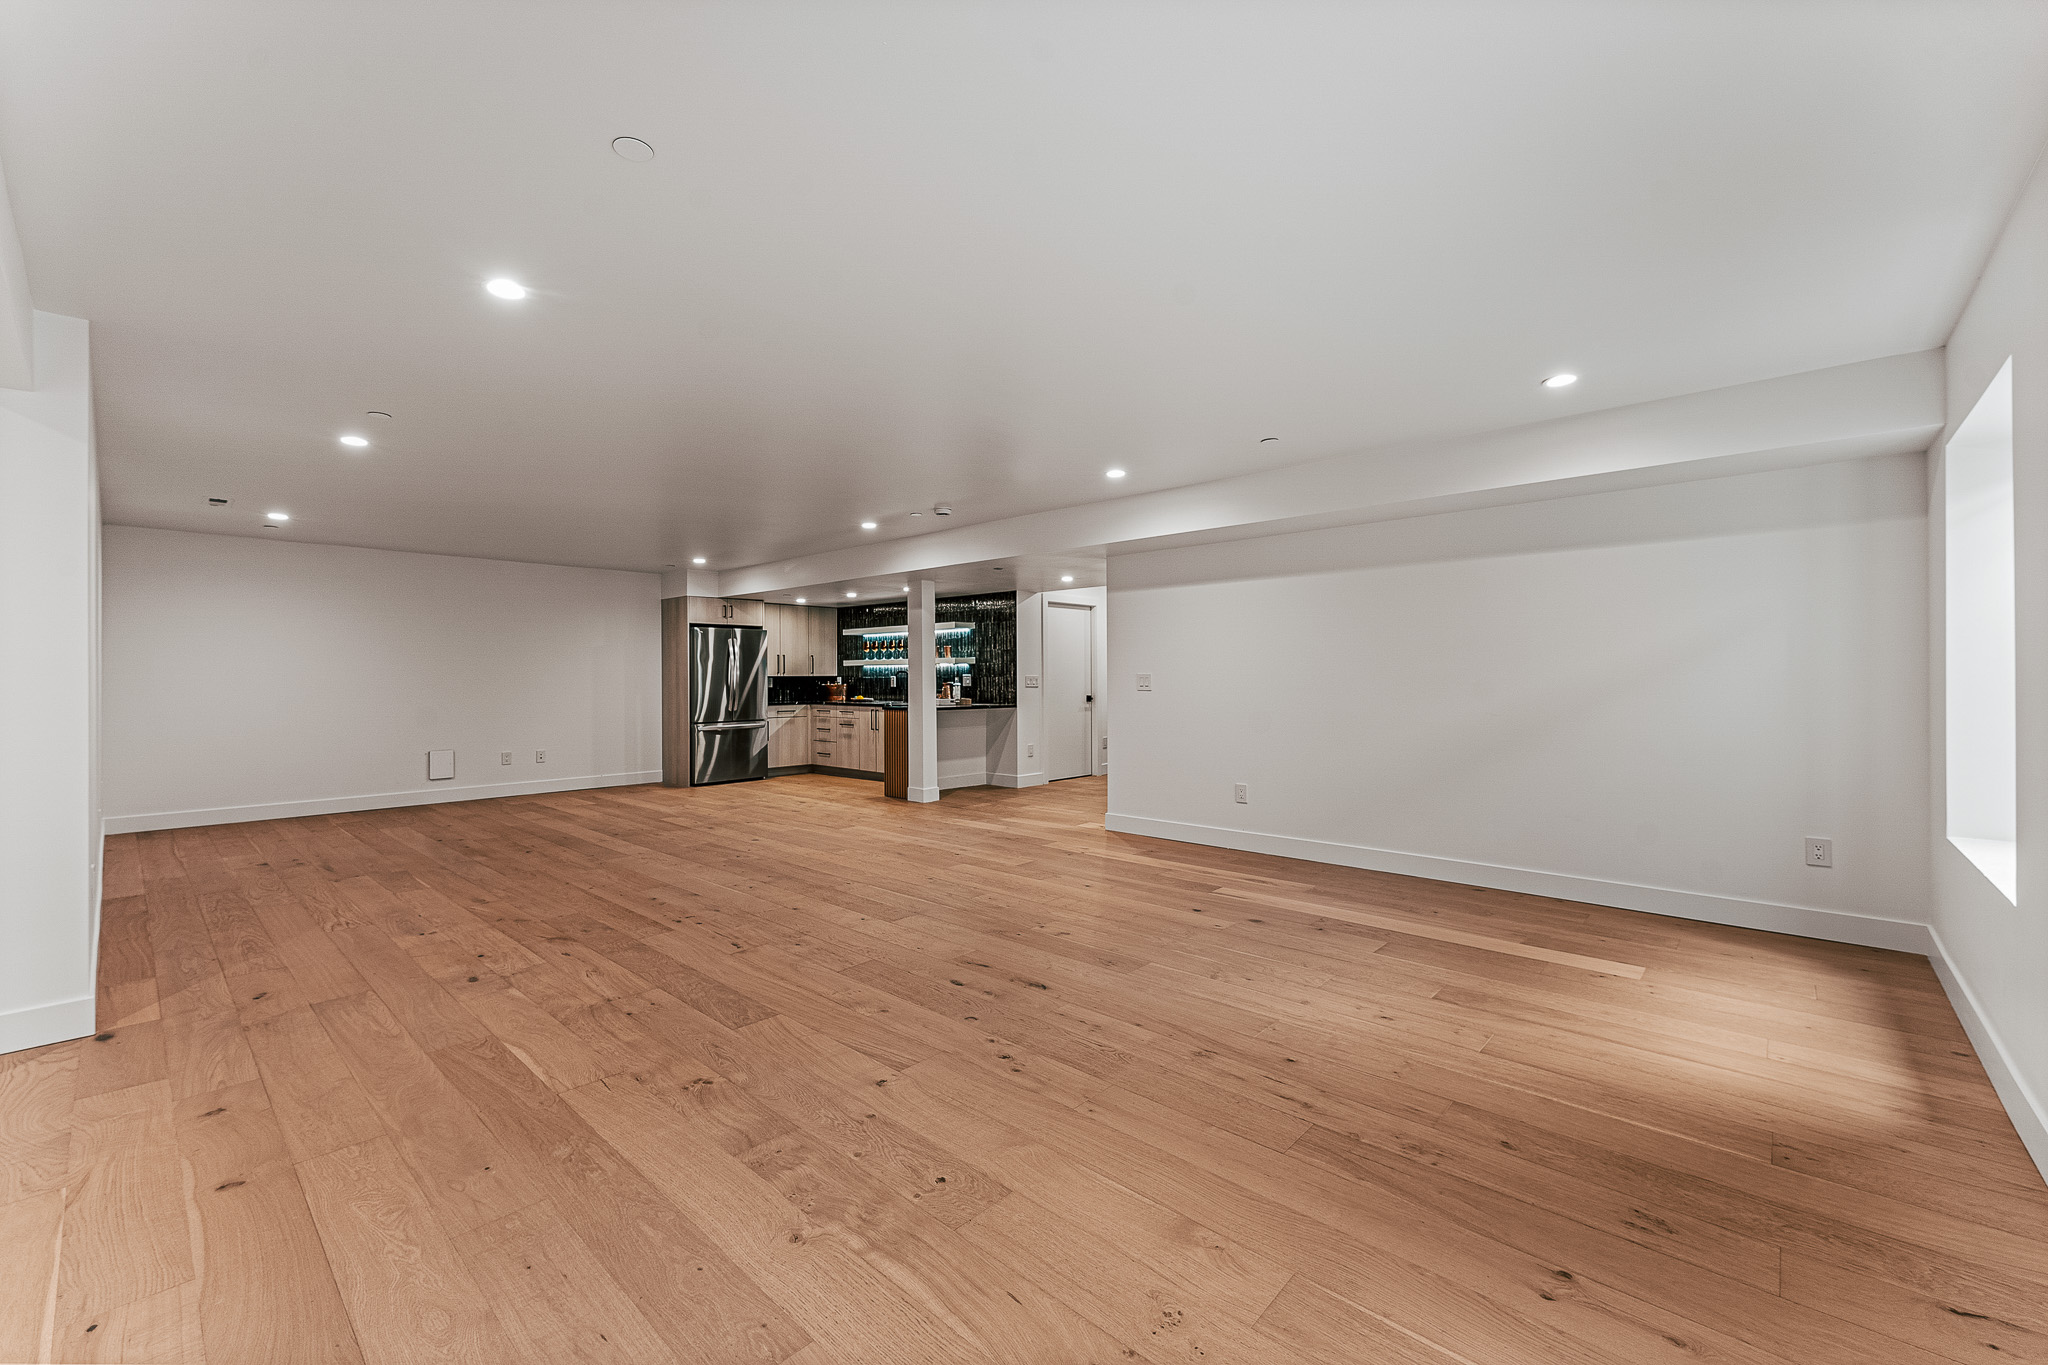
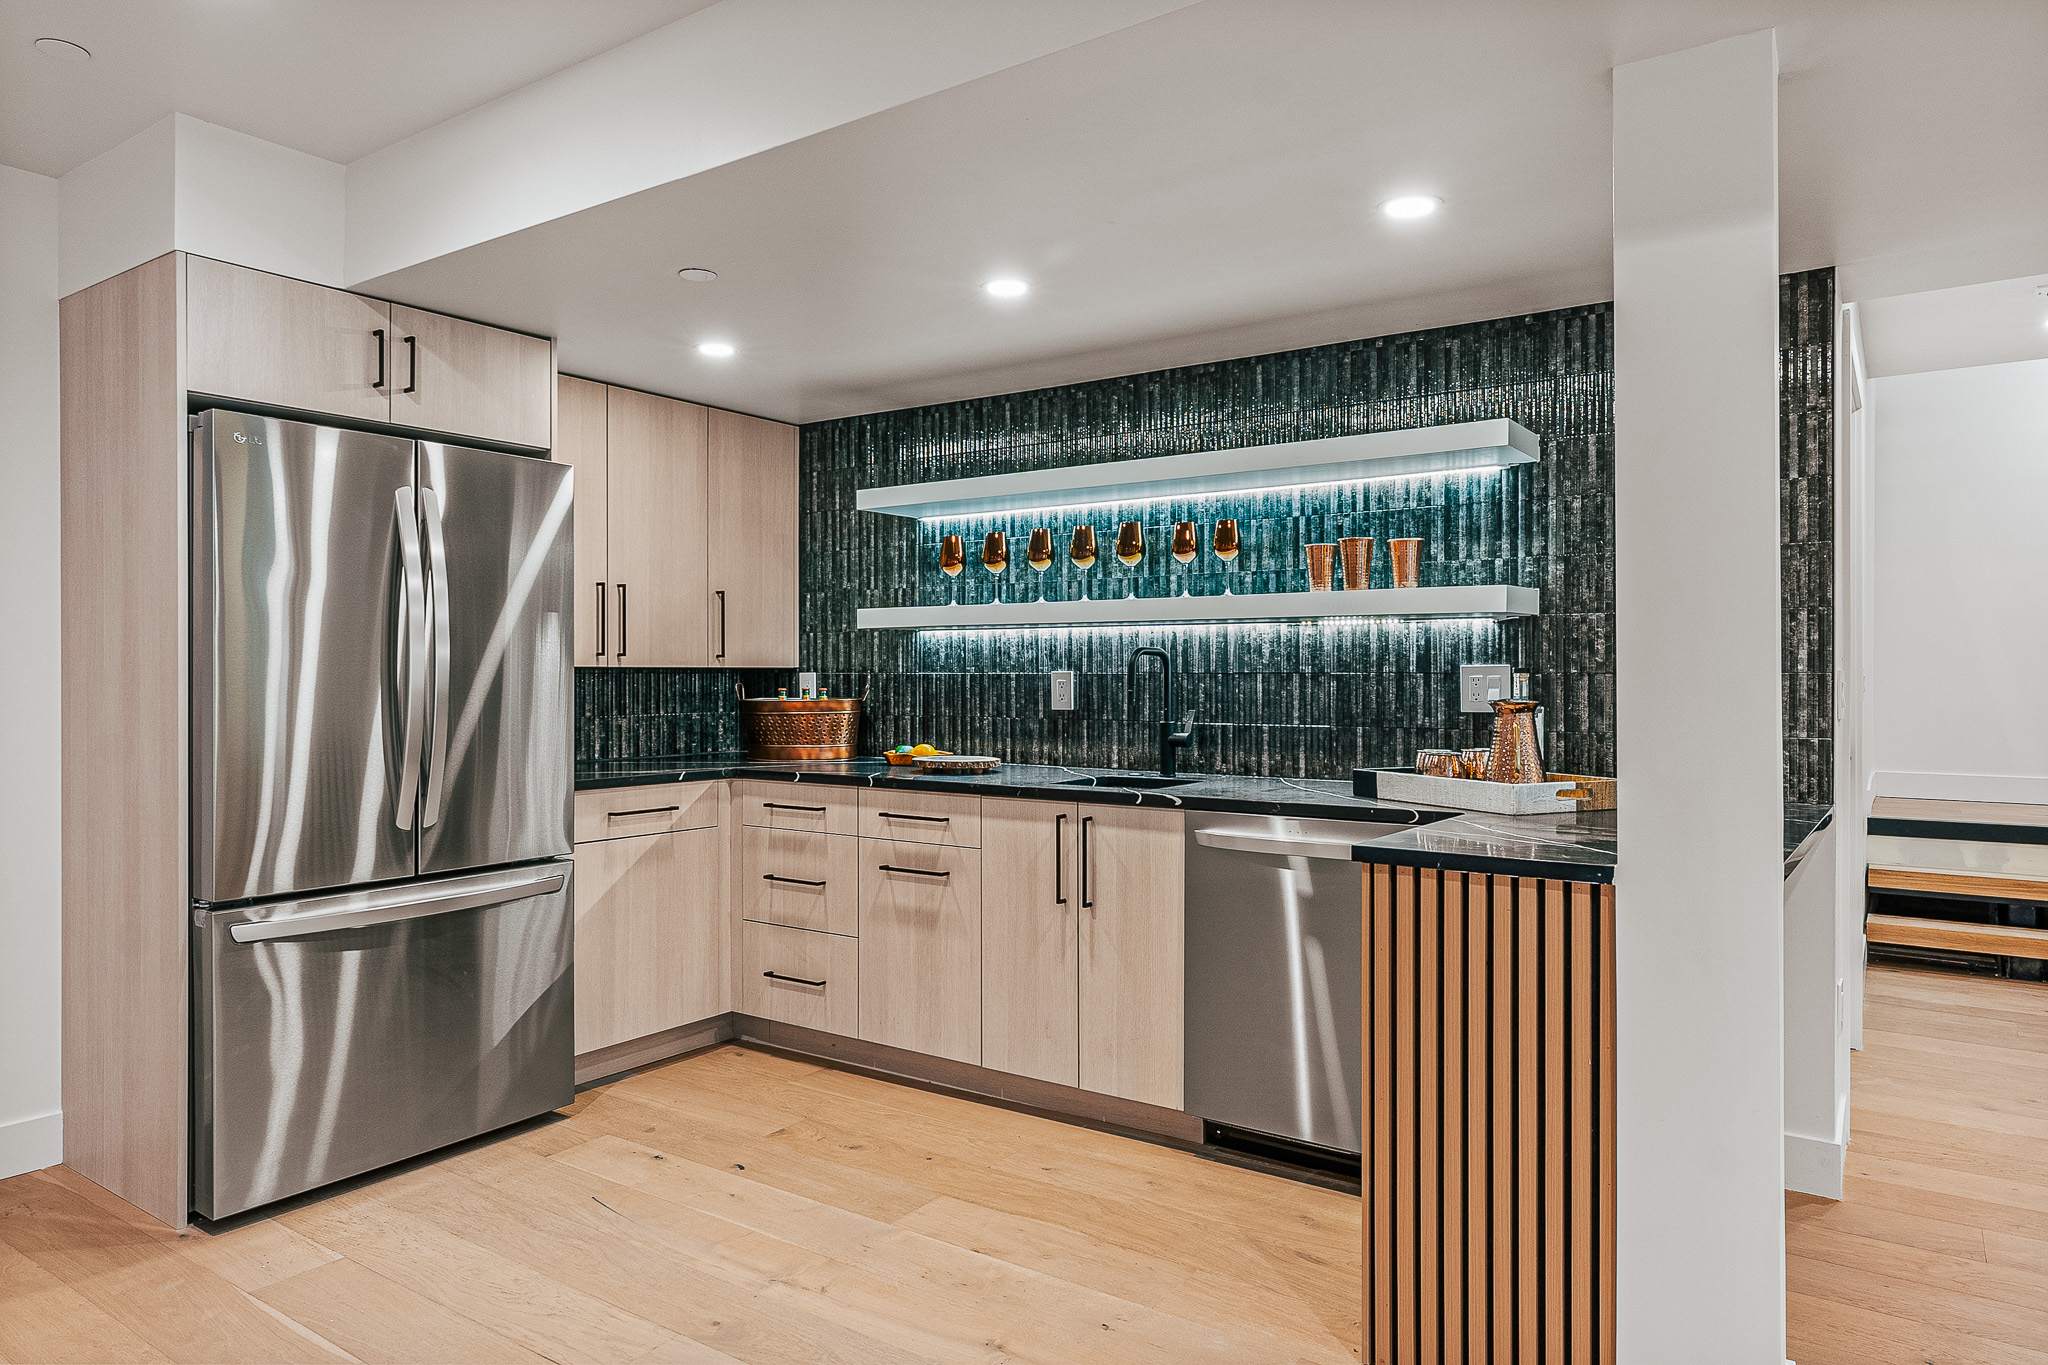
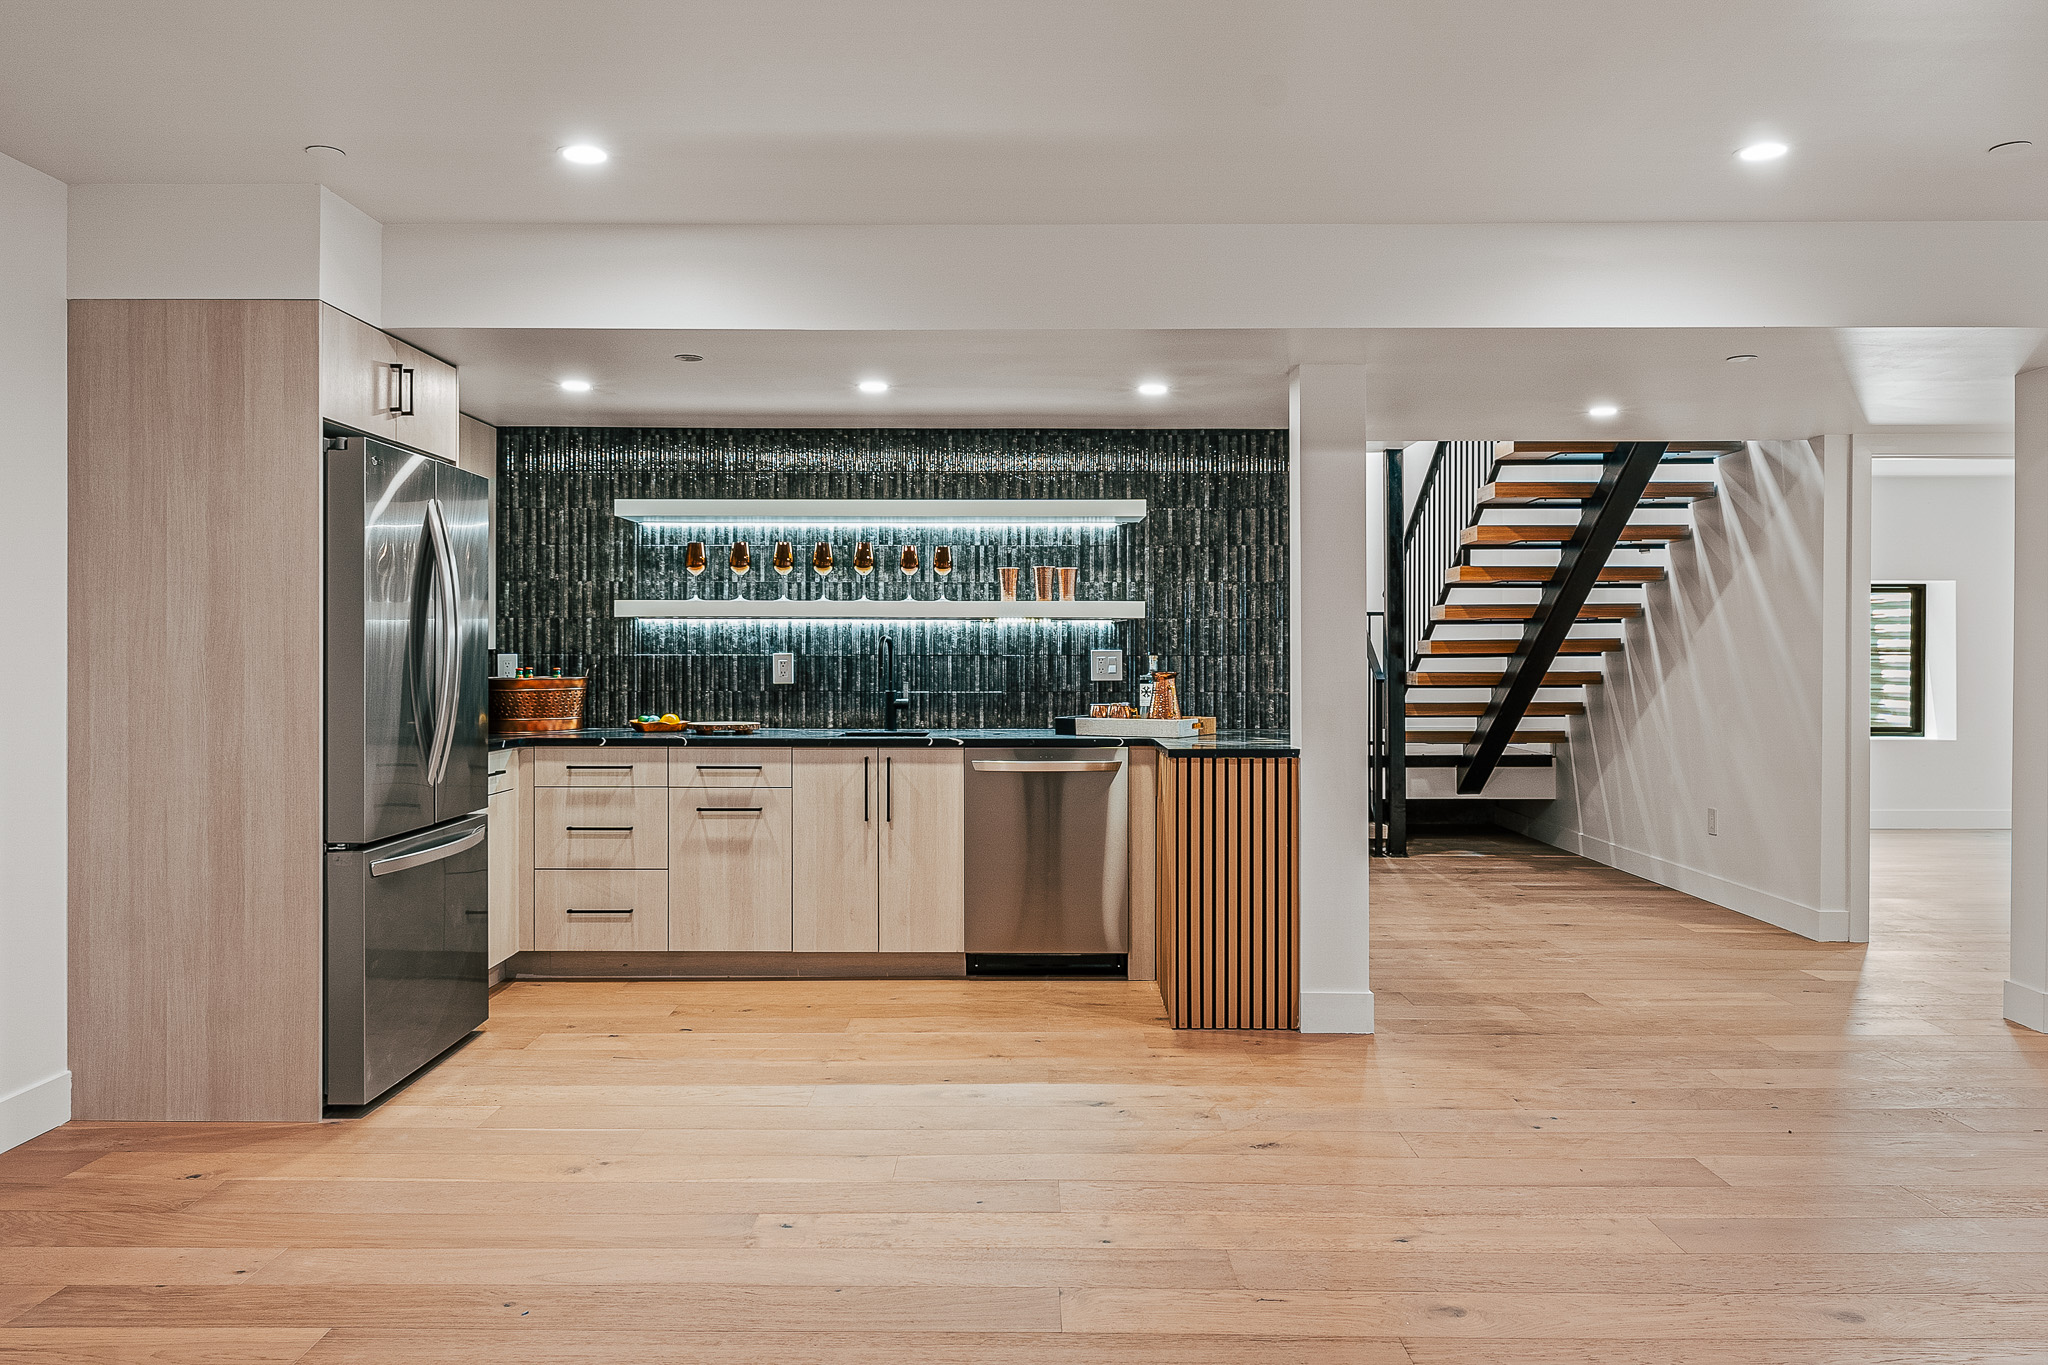
One of our ongoing semi-custom builds in Cheyenne, WY being financed with a VA construction loan
Considerations for Choosing a Builder: Experience with VA Financing, Guaranteed Maximum Prices, and Guaranteed Durations
Getting approved for a VA construction loan is an important first step, but choosing the right builder is even more critical for your project’s success. Not every builder is familiar with or works with VA-financed construction.
Beyond experience with VA financing, how your builder manages your budget and timeline is incredibly important when working with your loan. Your builder needs to provide clarity around the two biggest concerns in construction: cost and completion date.
How We Remove the Uncertainties of Cost & Timelines for Veterans Building With a VA Loan
At PR Builders, we offer cost-plus pricing with a Guaranteed Maximum Price (GMP) and Guaranteed Project Duration on all of our new build projects.
Our cost-plus model provides transparency into where your money is going, while the Guaranteed Maximum Price establishes a clear ceiling on your total investment before construction begins.
We also provide a defined project timeline (Guaranteed Project Duration). Rather than relying on a general estimate, we commit to a schedule based on detailed planning, trade coordination, and the actual requirements of your project—with contractually defined penalties for our team should we fail to meet this timeline.
When choosing a builder for your VA-financed home, look beyond the floor plans, designs, and ideas. Ask how they manage budgets, timelines, and communication throughout construction. More importantly, ask if they are willing to stand behind those promises with a Guaranteed Maximum Price and Guaranteed Project Duration. That commitment by your builder will give you incredible peace of mind when planning one of the largest and most worthwhile investments you’ll ever make.
Is Building a Home with a VA Loan Right for Me?
A VA construction loan is a great option for qualifying veterans who want more control over their home and are willing to plan ahead.
Building (instead of buying) with a VA loan is worth considering if you:
- Want a home specifically designed for your family
- Plan to stay in the home for several years
- Need features that are hard to find in existing homes
- Want to take advantage of VA loan benefits with a brand new home

Discover a Better Way to Build with PR Builders
PR Builders is a custom home builder serving Cheyenne, WY, and Northern Colorado. We work with veterans and homeowners throughout the area to build custom and semi-custom homes backed by the confidence of a Guaranteed Maximum Price and Guaranteed Duration.
If you’re considering building a home in Cheyenne with your VA benefits, reach out to us today to discuss your project, explore your options, and learn more about our home building process.
VA construction loans are available to eligible borrowers through participating lenders. PR Builders is not a lender and cannot guarantee loan approval. Financing terms and eligibility vary by lender. For more information on building in Cheyenne with a VA construction loan or how to get started, please feel free to reach out to us at 970-692-4589.